A Notice of Non-Renewal Due to Lapse in Supporting Agency Coverage is issued when a policyholder fails to maintain the secondary certifications or agency agreements required for primary insurance validity. This formal notification details why the contract will terminate and the steps needed to restore compliance. Understanding these legal requirements is essential for maintaining continuous protection. Below are some ready to use templates.
Image cover: Official Notice of Non-Renewal: Termination of Coverage Due to Agency Lapse
Letter Samples List
- Notice of Non-Renewal Letter Due to Lapse in Supporting Agency Coverage
- Standard Insurance Agency Non-Renewal Letter for Lapsed Supporting Policy
- Commercial Umbrella Non-Renewal Letter Due to Underlying Coverage Lapse
- Personal Lines Notice of Non-Renewal Letter for Unmaintained Supporting Policies
- Agency to Insured Non-Renewal Letter Regarding Dropped Supporting Coverage
- Notice of Policy Non-Renewal Letter Due to Inactive Companion Policy
- Excess Liability Non-Renewal Letter for Lapsed Primary Agency Coverage
- Carrier Mandated Non-Renewal Letter for Missing Supporting Coverage
- Brokerage Non-Renewal Letter Due to Expiration of Supporting Agency Policy
- Automated Agency Non-Renewal Letter for Discontinued Underlying Coverage
- Formal Notice of Non-Renewal Letter Regarding Supporting Policy Lapse
- Final Notice Non-Renewal Letter for Termination of Linked Agency Coverage
Notice of Non-Renewal Letter Due to Lapse in Supporting Agency Coverage
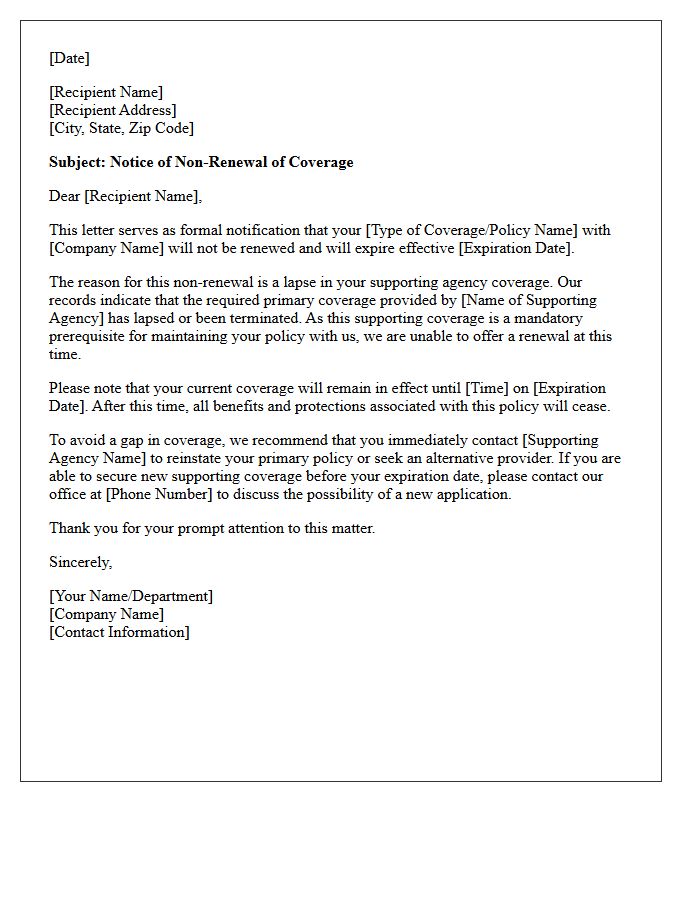
A Notice of Non-Renewal due to a lapse in supporting agency coverage occurs when your primary policy terminates, triggering the cancellation of secondary or umbrella insurance. Maintaining continuous underlying coverage is mandatory to satisfy secondary policy requirements. If your base insurance expires, the carrier will issue this formal notice to end your contract. To prevent a permanent loss of protection, you must immediately secure a replacement policy and provide proof to your insurer to ensure your risk exposure remains fully covered without any legal or financial gaps.
Standard Insurance Agency Non-Renewal Letter for Lapsed Supporting Policy
A standard non-renewal letter notifies policyholders that their insurance coverage will terminate due to a lapsed supporting policy. Many insurers require multi-policy bundling to maintain specific eligibility or discounts. If a primary account, such as auto insurance, is cancelled or fails to renew, the secondary supporting policy often faces automatic non-renewal. To prevent a lapse in protection, you must reinstate the underlying coverage immediately or secure an alternative carrier before the expiration date listed in the formal notice to ensure continuous risk mitigation.
Commercial Umbrella Non-Renewal Letter Due to Underlying Coverage Lapse
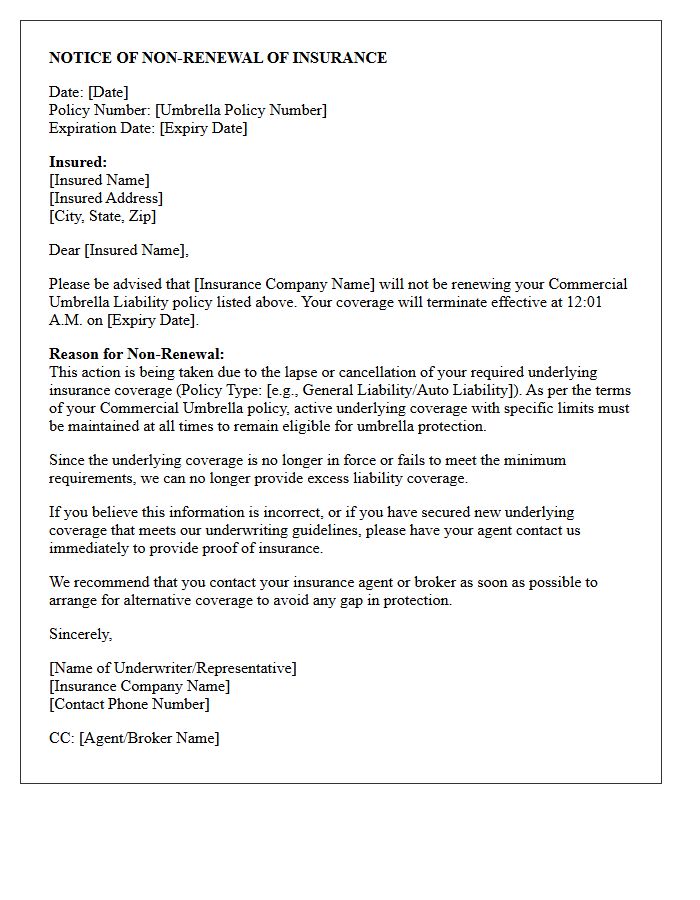
A commercial umbrella non-renewal letter issued due to an underlying coverage lapse signifies a critical protection gap. Umbrella policies require active primary insurance, such as general liability or auto, to remain in force. If these foundational policies expire or are cancelled, the follow-form nature of the umbrella is compromised, leading to automatic non-renewal. To maintain business continuity, you must immediately reinstate primary layers to satisfy the underlying limit requirements. Failing to address this results in significant financial exposure, as the secondary layer cannot function without a valid primary policy base.
Personal Lines Notice of Non-Renewal Letter for Unmaintained Supporting Policies
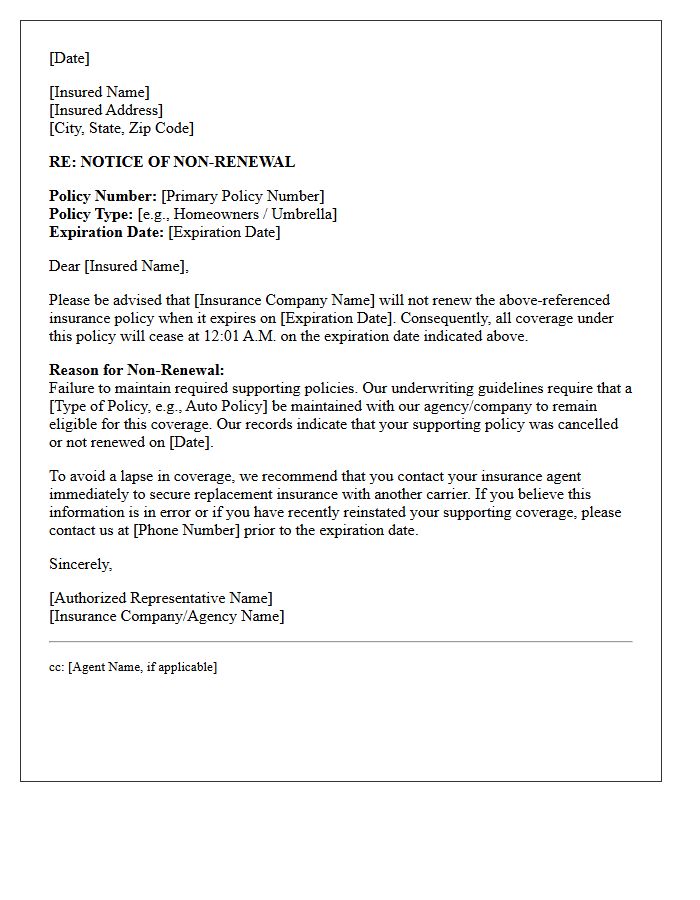
A Personal Lines Notice of Non-Renewal is a formal legal notification issued by insurers when a policy will not be extended. A common reason involves unmaintained supporting policies, which occurs when a client cancels secondary coverage required for a multi-policy discount or package eligibility. To maintain active coverage, policyholders must ensure all linked accounts remain in good standing. Failure to rectify these gaps may lead to a total loss of protection, making it essential to review underwriting requirements immediately upon receipt of such a notice.
Agency to Insured Non-Renewal Letter Regarding Dropped Supporting Coverage
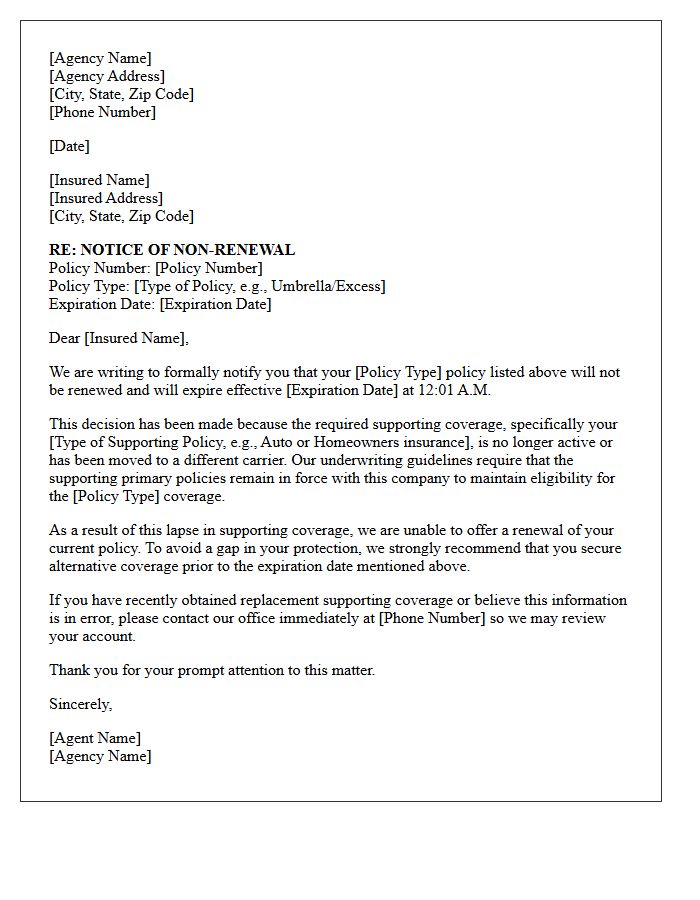
When an agency sends a non-renewal letter because a client dropped supporting coverage, it signifies the loss of a multi-policy requirement. Many insurers mandate bundling to maintain eligibility for specific primary policies. If a secondary line is canceled, the carrier may no longer accept the underlying risk, leading to a mandatory non-renewal notice. Policyholders must act quickly to secure alternative replacement coverage or reinstate the necessary supporting policies to satisfy underwriting guidelines and avoid a lapse in protection.
Notice of Policy Non-Renewal Letter Due to Inactive Companion Policy
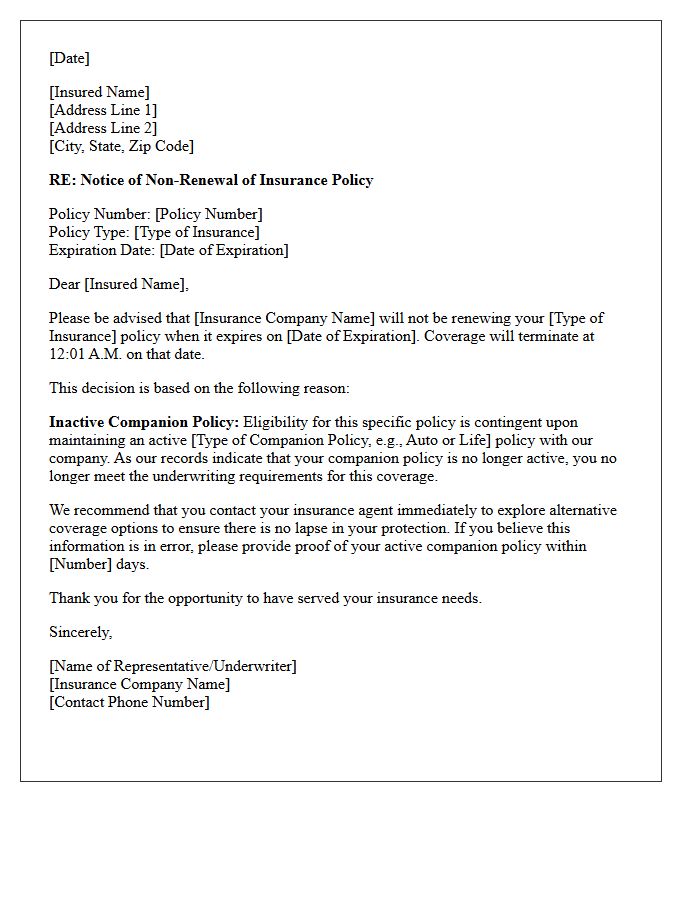
A notice of non-renewal occurs when an insurer terminates coverage because you cancelled a companion policy, such as auto or life insurance, that was required for eligibility. Insurance companies often use bundling requirements to manage risk and provide discounts. If the secondary policy becomes inactive, the primary policy no longer meets underwriting guidelines. To maintain protection, you must quickly secure alternative coverage or reinstate the linked policy before the expiration date noted in the letter to avoid a dangerous lapse in coverage.
Excess Liability Non-Renewal Letter for Lapsed Primary Agency Coverage
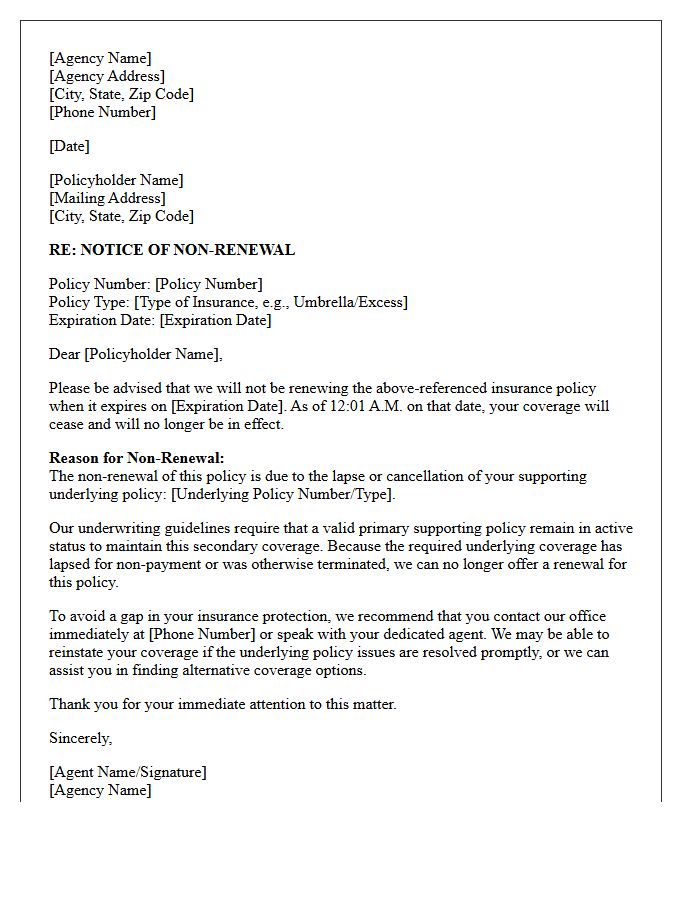
Receiving an Excess Liability Non-Renewal Letter following lapsed primary coverage is a critical warning. Excess policies are contingent upon maintaining active underlying insurance; if your primary agency coverage expires, the secondary layer loses its foundation. This notice signifies that the carrier will terminate your extended protection due to a breach of policy conditions. To maintain asset security and avoid unprotected risk exposure, you must immediately reinstate your primary underlying limits and provide proof of coverage to the excess provider to prevent a permanent loss of coverage.
Carrier Mandated Non-Renewal Letter for Missing Supporting Coverage
A Carrier Mandated Non-Renewal Letter for Missing Supporting Coverage is a formal notice that your insurance policy will terminate. This typically occurs because the insurer requires supporting coverage, such as an active property policy, to maintain an umbrella or secondary line. If the primary underlying policy is canceled or moved to a different provider, the carrier may issue a mandatory non-renewal. To prevent a lapse, you must secure a qualifying primary policy that meets the carrier's binding requirements before the expiration date listed in the notification.
Brokerage Non-Renewal Letter Due to Expiration of Supporting Agency Policy
A brokerage non-renewal letter notifies clients that their coverage will terminate because the supporting agency policy has expired. This typically occurs when a primary master agreement or underlying contract ends, making the secondary brokerage agreement unsustainable. It is crucial to review the expiration date immediately to avoid protection gaps. Policyholders should seek alternative coverage or a new broker promptly, as this notice of non-renewal confirms that the current intermediary can no longer legally or contractually service the account once the foundational policy ceases to exist.
Automated Agency Non-Renewal Letter for Discontinued Underlying Coverage
An automated agency non-renewal letter notifies policyholders when an insurer stops offering specific underlying coverage. This process is essential for compliance with state regulations, ensuring clients receive timely legal notice before their policy expires. Automation minimizes manual errors, streamlining the discontinuation workflow for agencies. It is crucial to clearly state the reason for non-renewal and provide options for replacement coverage to maintain trust and protect the agency from errors and omissions (E&O) risks during the transition period.
Formal Notice of Non-Renewal Letter Regarding Supporting Policy Lapse
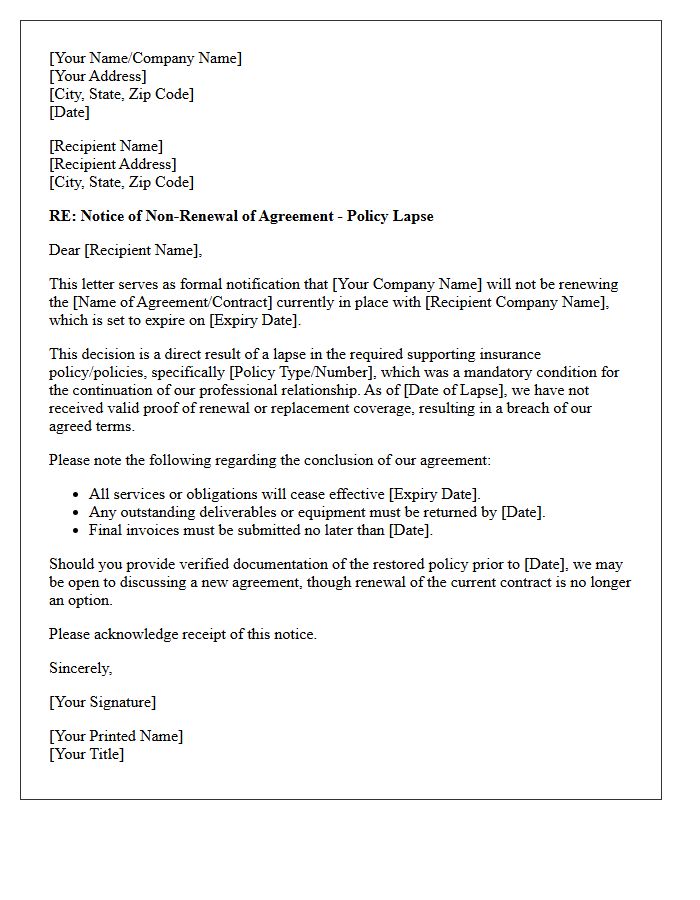
A formal notice of non-renewal is a critical legal document informing a policyholder that their coverage will terminate at the expiration date. To prevent a supporting policy lapse, it is essential to review the specific termination date and the stated reasons for non-renewal. This notice serves as a mandatory warning, allowing the insured time to secure alternative protection. Failure to act promptly can result in a dangerous gap in coverage, increased premiums, or future insurability issues. Always verify the notification period required by local regulations to ensure your rights are protected.
Final Notice Non-Renewal Letter for Termination of Linked Agency Coverage
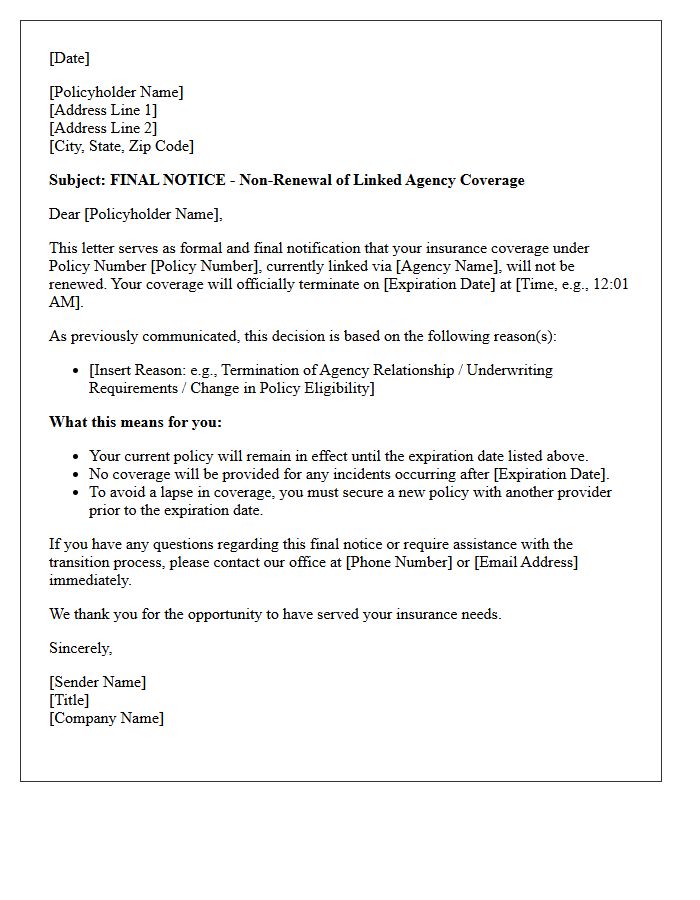
A Final Notice Non-Renewal Letter serves as the definitive legal notification that your insurance policy will not be extended past its current expiration date. This document confirms the termination of linked agency coverage, meaning the relationship between the insurer and the agent is ending. It is crucial to review the effective date immediately to avoid a lapse in protection. Upon receipt, you must secure a new policy through a different provider or agency to ensure continuous risk management and compliance with legal or mortgage requirements.
What is a Notice of Non-Renewal Due to Lapse in Supporting Agency Coverage?
This notice is a formal communication from an insurance carrier stating that your policy will not be renewed because the independent agency or supporting organization originally managing your coverage no longer has an active contract or appointment with the carrier.
Why did I receive a non-renewal notice if I paid my premiums on time?
Non-renewal due to a lapse in agency coverage is typically administrative rather than behavioral; it occurs when the legal relationship between your insurance company and your agent ends, leaving no authorized representative to service your policy under current terms.
Can I maintain my insurance policy if I switch to a different agency?
In many cases, you can avoid a lapse in protection by requesting a "Broker of Record" change to move your policy to a new agency that is actively appointed with the carrier, provided this is done before the non-renewal effective date.
How much time do I have to find new coverage after receiving this notice?
State insurance laws generally require carriers to provide 30 to 60 days of advance notice before the policy expiration date, giving you a specific window to secure a new policy or transition to a new agent.
Will a non-renewal due to agency lapse affect my insurance score or future rates?
No, a non-renewal based on an agency's status is considered a "non-fault" action and does not reflect your risk profile, meaning it should not negatively impact your insurance score or your ability to get competitive rates elsewhere.
Comments