An Audit Response Opinion Letter is a formal legal document provided by an attorney to an auditor regarding a client's pending litigation and liabilities. This crucial communication ensures financial transparency and regulatory compliance during the annual reporting process. Understanding the specific terminology and disclosure requirements is essential for legal accuracy. To assist your firm, below are some ready to use templates.
Image cover: Professional Templates and Samples for Audit Response Opinion Letters
Letter Samples List
- Standard Audit Response Opinion Letter
- Pending Litigation Audit Response Letter
- Unasserted Claims Legal Opinion Letter
- Loss Contingency Audit Response Letter
- Outside Counsel Audit Response Letter
- Qualified Audit Response Opinion Letter
- Materiality Threshold Audit Opinion Letter
- American Bar Association Policy Compliant Audit Response Letter
- Year-End Financial Audit Opinion Letter
- Subsequent Events Audit Response Letter
- Clean Opinion Legal Audit Letter
- Subject Matter Specific Audit Opinion Letter
Standard Audit Response Opinion Letter
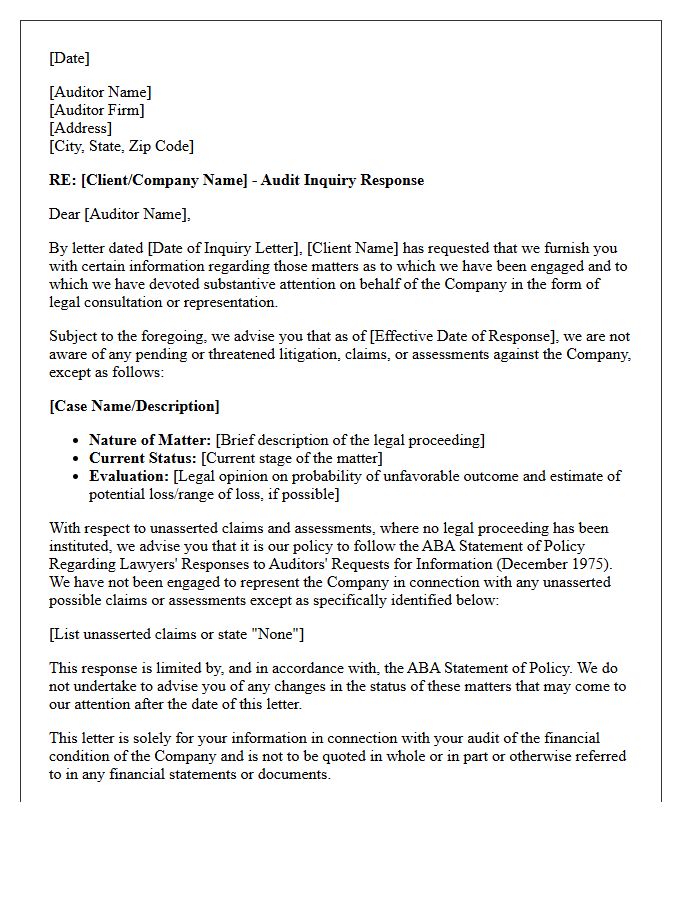
A Standard Audit Response Opinion Letter is a formal document issued by legal counsel to an independent auditor regarding pending litigation or potential liabilities. It serves as critical audit evidence to verify a company's financial health and legal exposure. The letter must balance transparency with the attorney-client privilege to avoid waiving legal protections. By evaluating the probability of unfavorable outcomes and estimating potential financial losses, these letters ensure that contingent liabilities are accurately disclosed in accordance with professional accounting standards and legal frameworks.
Pending Litigation Audit Response Letter
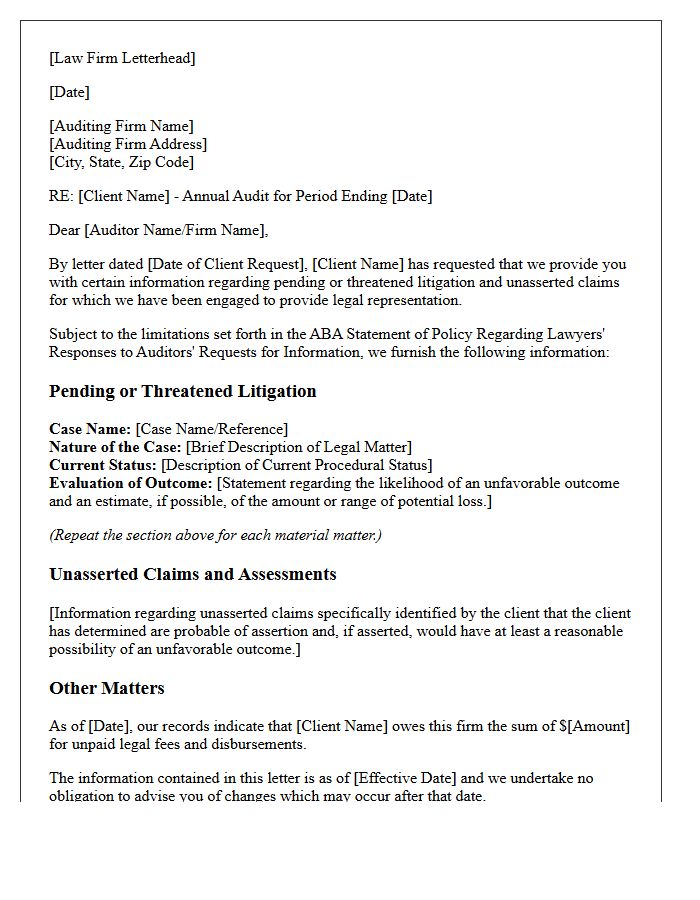
A Pending Litigation Audit Response Letter is a formal document sent by a company's legal counsel to external auditors. Its primary purpose is to disclose potential liabilities and ongoing lawsuits that could materially affect financial statements. This communication ensures transparency regarding legal risks, helping auditors assess the financial health of the entity. To maintain accuracy and protect attorney-client privilege, the letter carefully outlines the nature of claims, the probability of unfavorable outcomes, and estimated financial impacts, playing a critical role in the annual audit process and corporate compliance.
Unasserted Claims Legal Opinion Letter
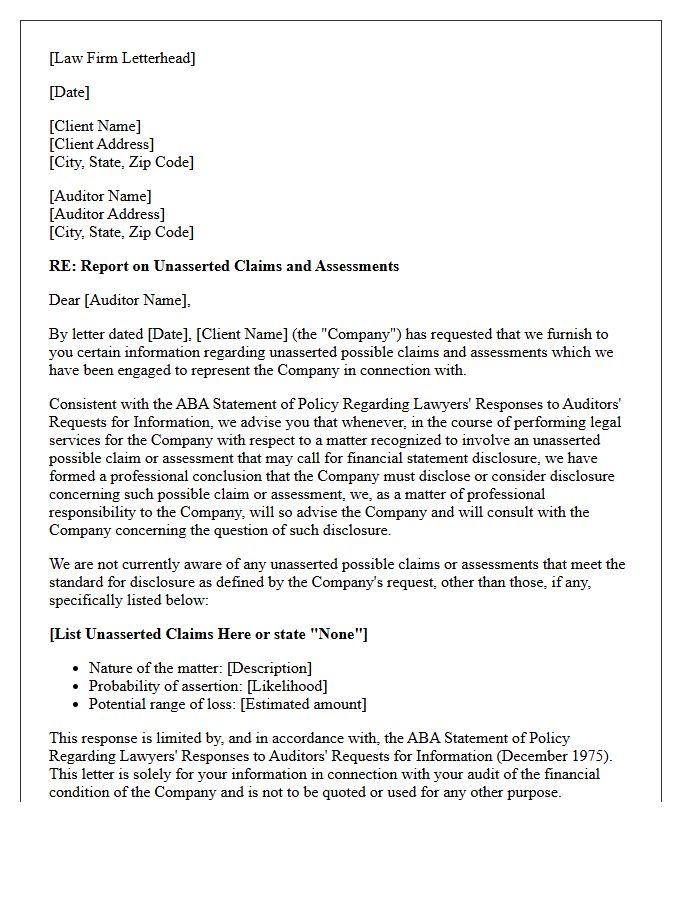
An Unasserted Claims Legal Opinion Letter provides a formal evaluation by counsel regarding potential litigation that has not yet been filed. It is crucial for financial reporting, helping auditors assess whether a contingent liability must be disclosed or accrued. This document evaluates the probability of an unfavorable outcome and the potential financial impact. By identifying latent risks, it ensures corporate transparency and compliance with accounting standards, allowing stakeholders to understand the company's future legal exposure before a formal lawsuit or demand is officially initiated.
Loss Contingency Audit Response Letter
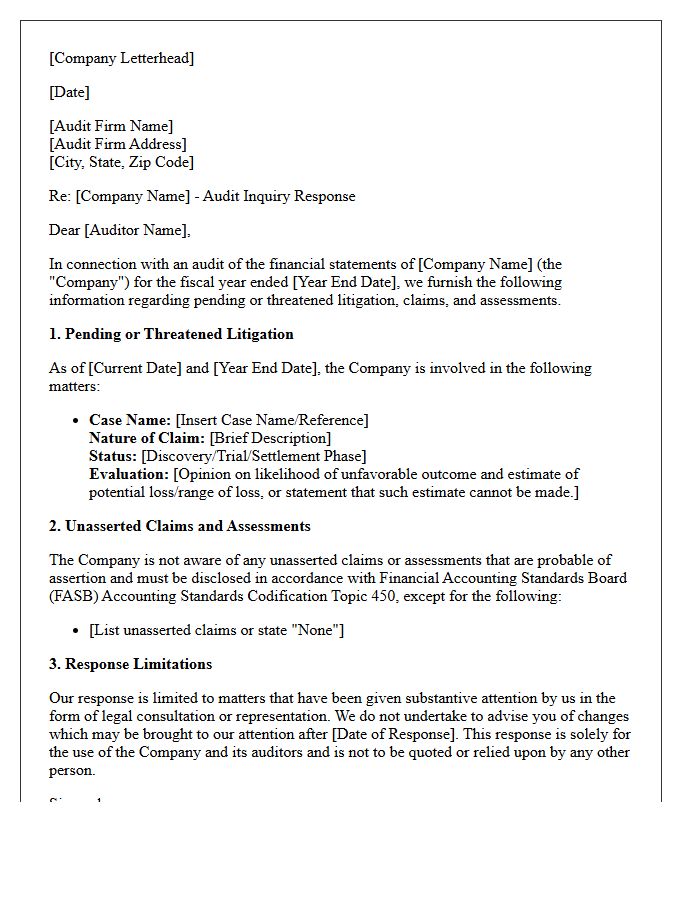
A Loss Contingency Audit Response Letter is a formal legal confirmation sent by an entity's legal counsel to its independent auditors. This document discloses potential liabilities arising from pending or threatened litigation, claims, and assessments. It is essential for ensuring that financial statements accurately reflect future financial risks. The letter evaluates the probability of an unfavorable outcome and provides estimated loss ranges when possible. Accurate reporting is critical for regulatory compliance and maintaining transparency for stakeholders regarding the organization's overall financial health and legal exposure.
Outside Counsel Audit Response Letter
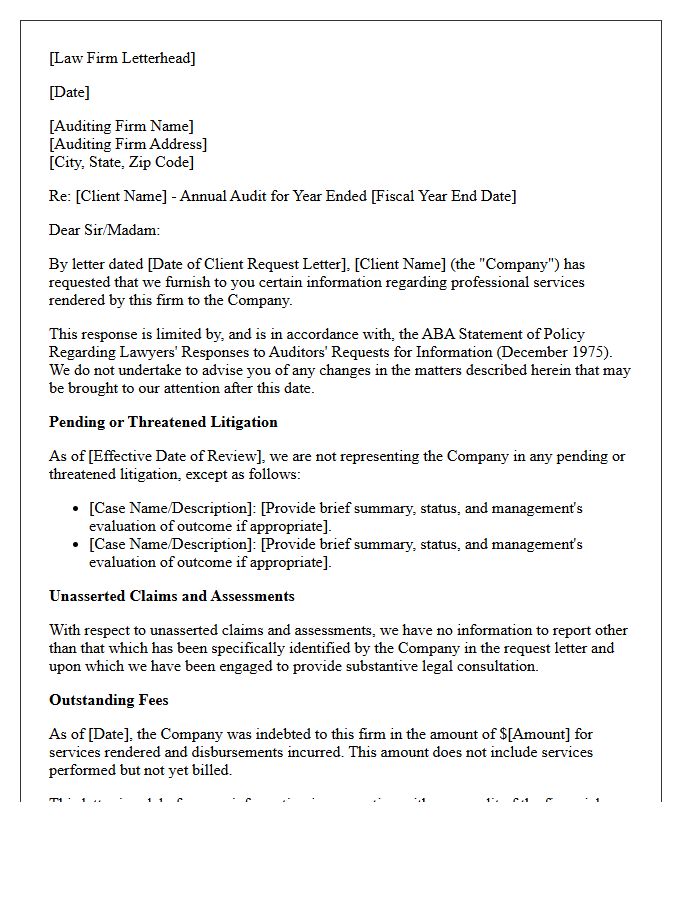
An Outside Counsel Audit Response Letter is a formal legal communication sent to a company's auditors. It discloses potential contingent liabilities, such as pending or threatened litigation, that may materially impact financial statements. Following the ABA Statement of Policy, attorneys must balance confidentiality and disclosure requirements. This document is essential for financial transparency and ensures that auditors can verify the accuracy of a client's legal risk profile during an annual audit process. Accurate reporting prevents legal exposure and maintains regulatory compliance for the organization.
Qualified Audit Response Opinion Letter
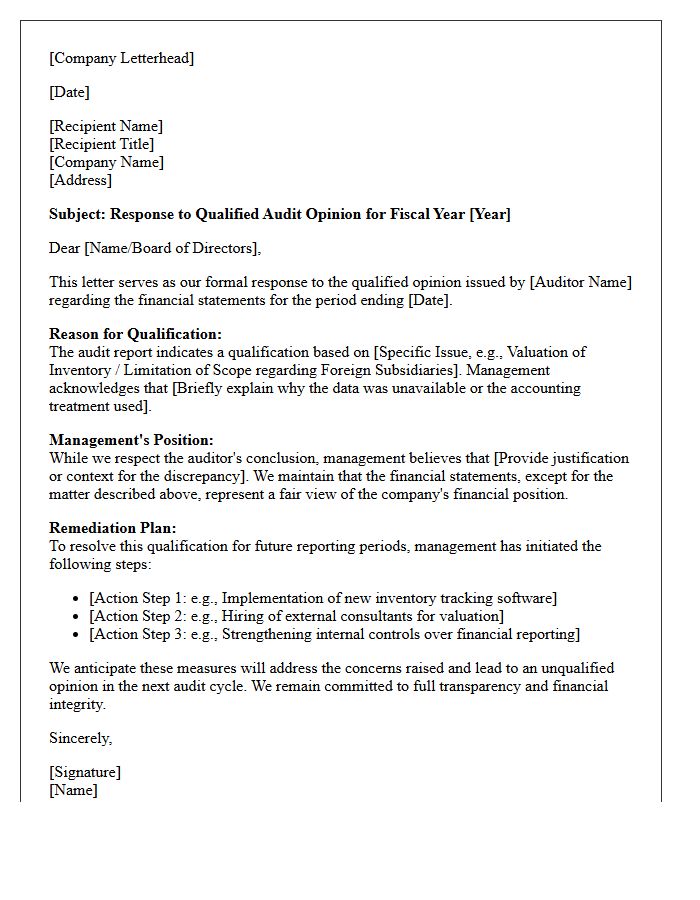
A Qualified Audit Response Opinion Letter is a formal document issued by an auditor when financial statements are fairly presented except for specific areas. This "qualified" status indicates that certain accounting practices do not fully comply with GAAP or that the auditor encountered a limitation in scope during the examination. While the report is not a total rejection, it alerts stakeholders to potential material misstatements or missing documentation. Investors and lenders scrutinize these letters closely, as they signal specific financial risks or uncertainties that require immediate attention and corrective action.
Materiality Threshold Audit Opinion Letter
A materiality threshold is the quantitative benchmark used by auditors to determine if financial misstatements are significant enough to influence stakeholders. In an audit opinion letter, this threshold defines the boundary for reasonable assurance. If errors exceed this limit, the auditor may issue a qualified or adverse opinion. Understanding this concept is vital because it clarifies that audits focus on material accuracy rather than absolute precision, ensuring the financial statements present a true and fair view of the organization's economic reality for investors and regulators.
American Bar Association Policy Compliant Audit Response Letter
An American Bar Association Policy Compliant Audit Response Letter is a formal legal communication providing auditors with information regarding a client's pending or threatened litigation. To protect attorney-client privilege, firms strictly adhere to the ABA Statement of Policy. This framework ensures lawyers only disclose material loss contingencies that are probable or reasonably possible, avoiding broad disclosures that could waive legal protections. Understanding these constraints is essential for maintaining professional confidentiality while satisfying financial reporting requirements during a corporate audit process.
Year-End Financial Audit Opinion Letter
A Year-End Financial Audit Opinion Letter is a formal document issued by an independent auditor after examining a company's financial statements. It serves as an official confirmation of whether the records present a true and fair view of the organization's fiscal health. This letter is crucial for stakeholders, as it validates compliance with accounting standards and ensures transparency. An unmodified opinion indicates clean reports, whereas qualifications highlight potential risks or inaccuracies, directly impacting investor confidence and credibility.
Subsequent Events Audit Response Letter
A Subsequent Events Audit Response Letter is a formal document provided by management to auditors during the year-end review. It identifies significant occurrences happening between the balance sheet date and the issuance of financial statements. This letter ensures that material transactions, such as litigation settlements, asset disposals, or financing changes, are properly disclosed or adjusted. It serves as audit evidence to verify that the financial records reflect the company's true economic position, protecting stakeholders from outdated information and ensuring compliance with accounting standards.
Clean Opinion Legal Audit Letter
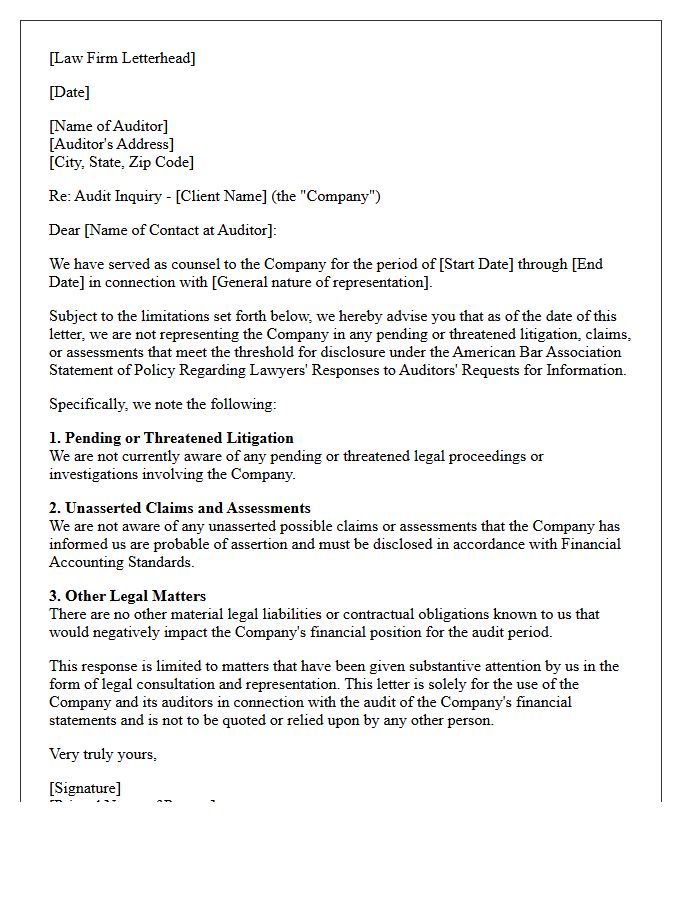
A Clean Opinion Legal Audit Letter, or an unqualified opinion, is a formal document issued by legal counsel during a corporate audit. It confirms that no material litigation, claims, or assessments exist that could jeopardize the company's financial integrity. This letter provides critical assurance to external auditors and investors that the entity's legal liabilities are accurately disclosed. Obtaining a clean opinion is vital for maintaining transparency and ensuring compliance with financial reporting standards, directly impacting a firm's credibility and overall valuation during fiscal reviews.
Subject Matter Specific Audit Opinion Letter
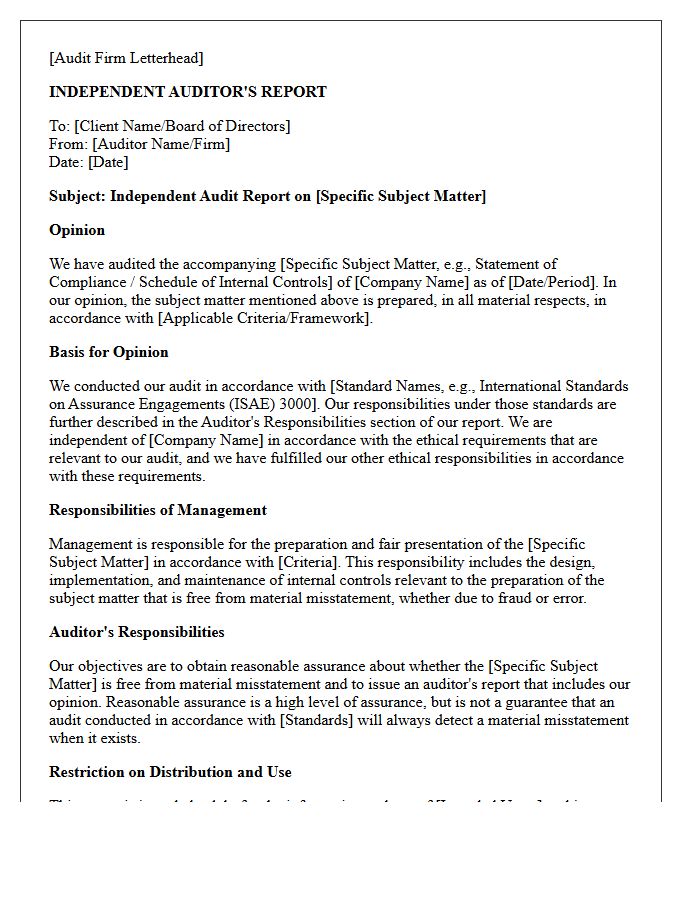
A Subject Matter Specific Audit Opinion Letter provides a formal assurance regarding a particular financial or non-financial assertion rather than full financial statements. It is crucial for verifying compliance, internal controls, or specific contract terms. This letter enhances stakeholder credibility by offering an independent professional evaluation of a targeted area. Investors and regulators rely on these documents to mitigate risk and ensure transparency within a specific scope of operations, making it a vital tool for accountability in specialized reporting frameworks.
What is an Audit Response Opinion Letter?
An Audit Response Opinion Letter is a formal legal document prepared by a company's legal counsel in response to an inquiry from independent auditors. It provides information regarding pending or threatened litigation, claims, and assessments that may impact the organization's financial statements.
Why do auditors request a legal response letter?
Auditors request these letters to corroborate management's assertions about the company's legal liabilities. This process is a standard requirement under professional accounting standards (such as ASC 450) to ensure that potential financial losses from legal matters are accurately disclosed or accrued.
What information is typically included in an Audit Response Opinion Letter?
The letter typically includes a list of pending litigation, a description of the nature of each matter, the current progress of the case, and an evaluation of the likelihood of an unfavorable outcome. It also specifies any limitations on the lawyer's response to protect attorney-client privilege.
How are loss contingencies evaluated in an audit response?
Attorneys evaluate loss contingencies using specific terminology: "probable" (likely to occur), "reasonably possible" (more than remote but less than likely), or "remote" (slight chance). If a loss is probable and estimable, the letter assists the auditor in determining the necessary financial statement accrual.
How does the ABA Statement of Policy affect audit response letters?
The American Bar Association (ABA) Statement of Policy Regarding Lawyers' Responses to Auditors' Requests for Information provides the framework for these letters. it balances the auditor's need for information with the lawyer's duty to maintain client confidentiality and avoid waiving legal privilege.
Comments