Insurance companies must act fairly when evaluating claims. If an insurer unreasonably denies or delays payment, a Bad Faith Insurance Claim Settlement Demand Letter is a critical legal tool to assert your rights and demand proper compensation. This document formalizes your grievances and sets a deadline for a fair resolution. To help you get started, below are some ready to use templates.
Image cover: Winning Your Bad Faith Insurance Claim: Effective Demand Letter Samples and Templates
Letter Samples List
- Unreasonable Claim Denial Bad Faith Demand Letter
- Unwarranted Delay In Claim Processing Bad Faith Demand Letter
- Failure To Properly Investigate Claim Bad Faith Demand Letter
- Inadequate Settlement Offer Bad Faith Demand Letter
- Refusal To Defend Third Party Claim Bad Faith Letter
- Breach Of Implied Covenant Bad Faith Settlement Demand Letter
- Deceptive Insurance Practices Bad Faith Demand Letter
- Pre-Litigation Final Settlement Demand Bad Faith Letter
- First Party Property Damage Bad Faith Settlement Letter
- Third Party Liability Bad Faith Settlement Demand Letter
- Unjustified Policy Rescission Bad Faith Demand Letter
- Failure To Communicate Claim Status Bad Faith Demand Letter
- Wrongful Withholding Of Policy Benefits Bad Faith Letter
- Statutory Unfair Claims Practices Bad Faith Demand Letter
Unreasonable Claim Denial Bad Faith Demand Letter
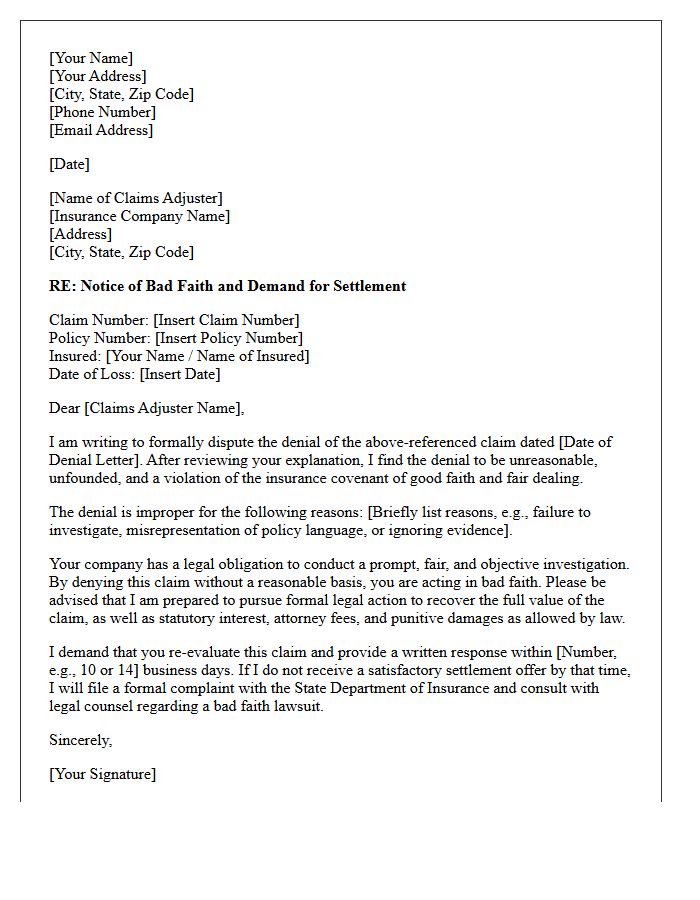
An Unreasonable Claim Denial Bad Faith Demand Letter is a formal legal notification sent to an insurance company that has unjustly refused a valid claim. This document highlights the insurer's failure to adhere to fiduciary duties and contractual obligations. It outlines specific evidence of misconduct, such as inadequate investigation or misrepresentation of policy terms. By threatening litigation under bad faith statutes, the letter pressures the insurer to settle immediately or face significant punitive damages and attorney fees in court, ensuring policyholders receive the compensation they are legally owed.
Unwarranted Delay In Claim Processing Bad Faith Demand Letter
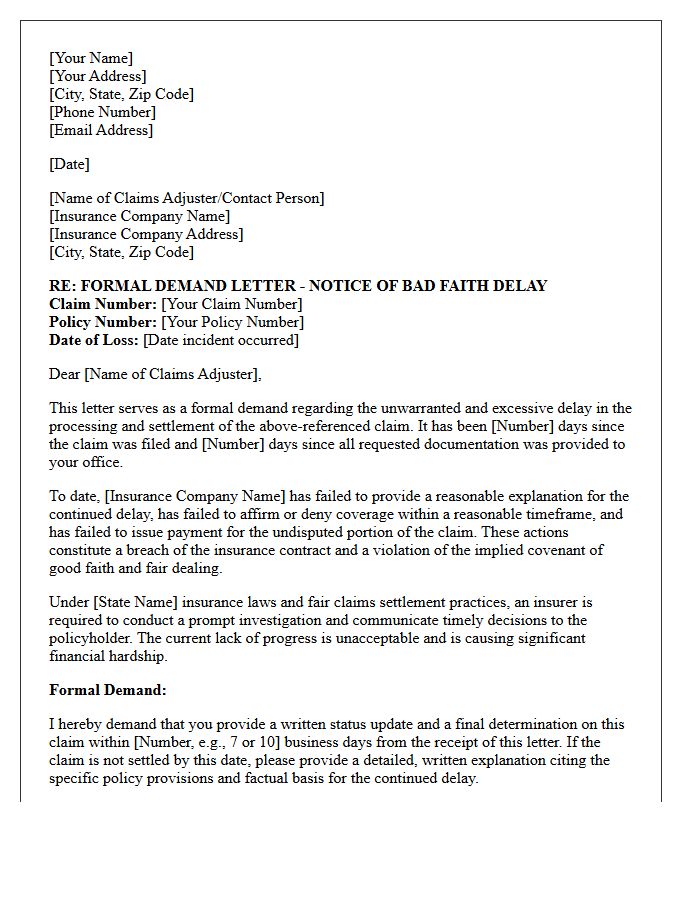
An unwarranted delay in insurance claim processing may constitute bad faith, violating the insurer's duty to act fairly. If a company fails to provide timely communication or reasonable explanations for setbacks, policyholders should issue a formal demand letter. This document must clearly outline the unreasonable timeline, document all correspondence, and cite specific legal obligations the insurer has breached. A well-structured demand letter serves as critical evidence for potential litigation, compelling the insurer to expedite the settlement process or face penalties for their dilatory tactics and lack of professional accountability.
Failure To Properly Investigate Claim Bad Faith Demand Letter
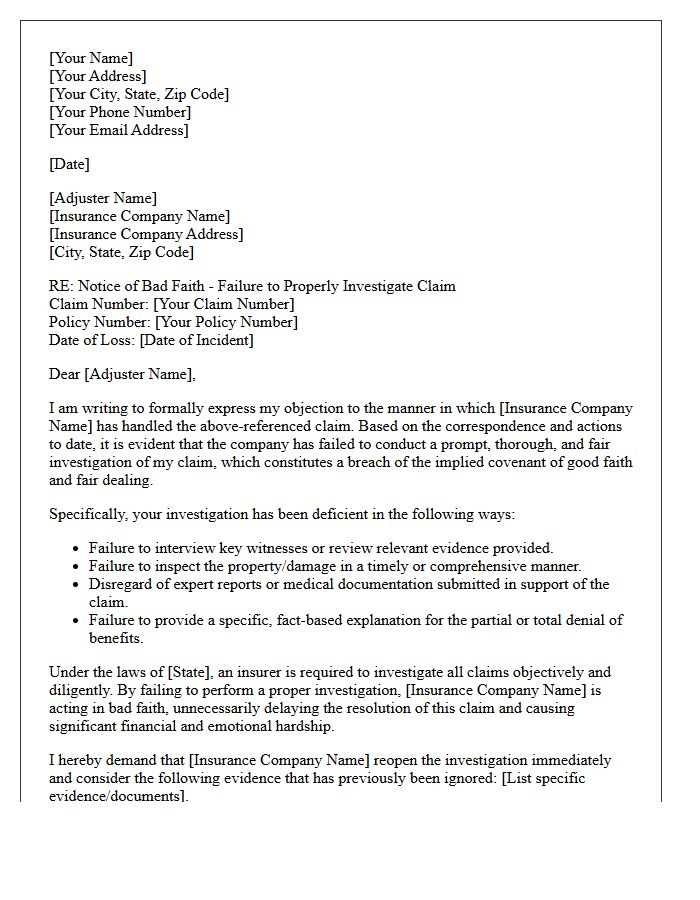
A bad faith demand letter is a formal legal notification sent to insurance companies that fail to conduct a thorough investigation of a policyholder's claim. Under insurance law, carriers have an implied duty of good faith to objectively evaluate all evidence. If an insurer denies a claim without performing a reasonable search for facts or ignores favorable information, they may be liable for extra-contractual damages. This letter serves as a legal prerequisite to a lawsuit, documenting the insurer's failure to meet industry standards and demanding immediate rectification of the claim handling process.
Inadequate Settlement Offer Bad Faith Demand Letter
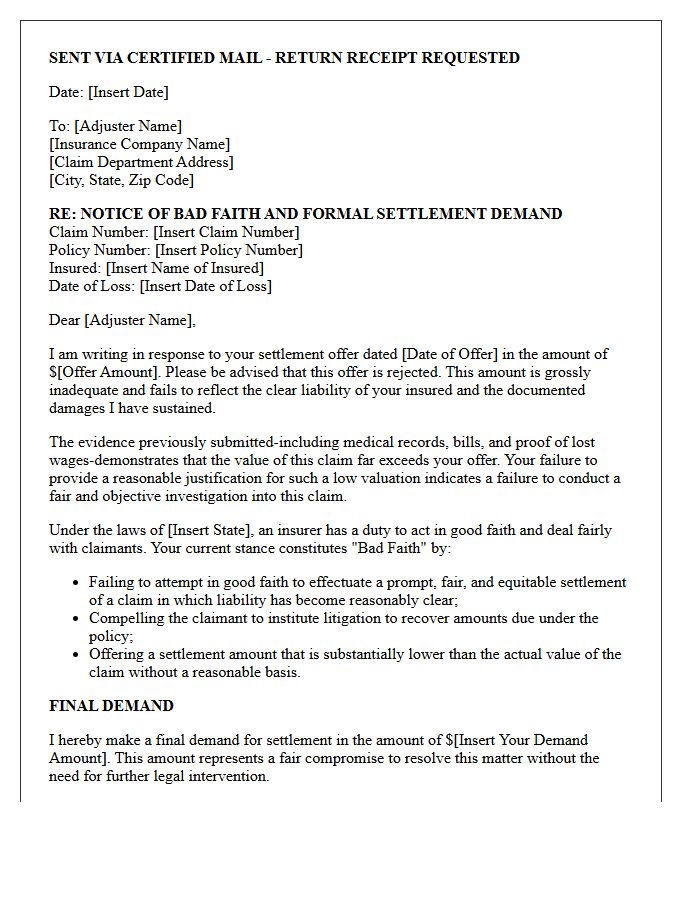
An Inadequate Settlement Offer Bad Faith Demand Letter is a formal legal notice sent when an insurance company fails to provide a fair payout. This letter asserts that the insurer is violating its legal duty to act in good faith by intentionally lowballing a claim. It serves as critical evidence for potential bad faith litigation, demanding that the company re-evaluate the damages or face legal consequences. By documenting the insurer's unreasonable conduct, you protect your rights and create a necessary paper trail for seeking full compensation and additional punitive damages.
Refusal To Defend Third Party Claim Bad Faith Letter
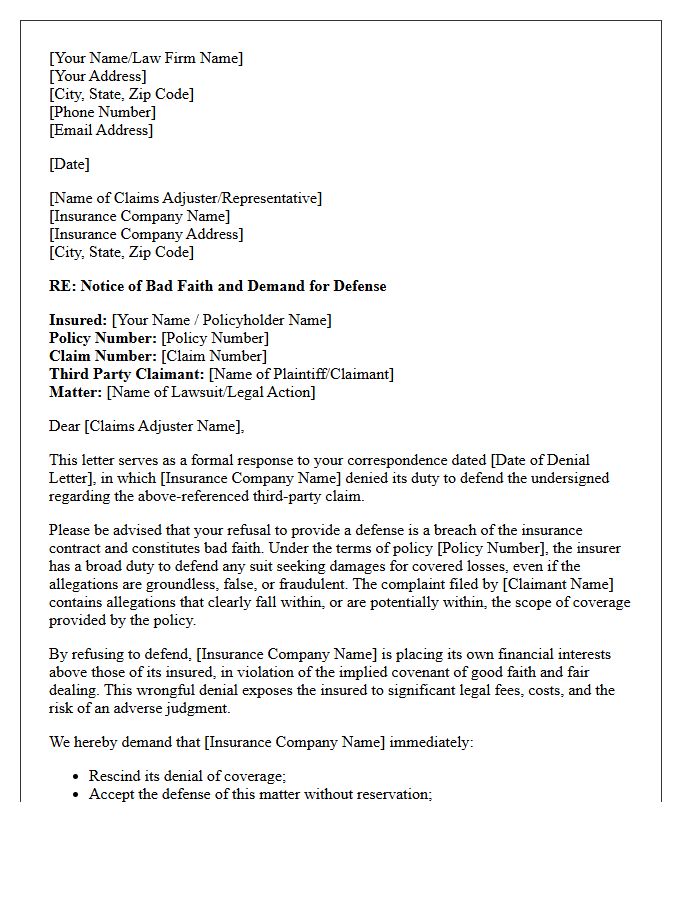
A bad faith letter for refusal to defend is a critical legal tool sent when an insurance carrier wrongfully denies its duty to defend a third-party claim. This formal notice asserts that the insurer is breaching its contractual obligations, potentially exposing them to damages beyond policy limits. The letter should clearly outline the factual allegations that trigger coverage and demand an immediate defense. Timely delivery is essential to preserve the policyholder's rights and establish a foundation for future bad faith litigation against the insurer for their unreasonable denial.
Breach Of Implied Covenant Bad Faith Settlement Demand Letter
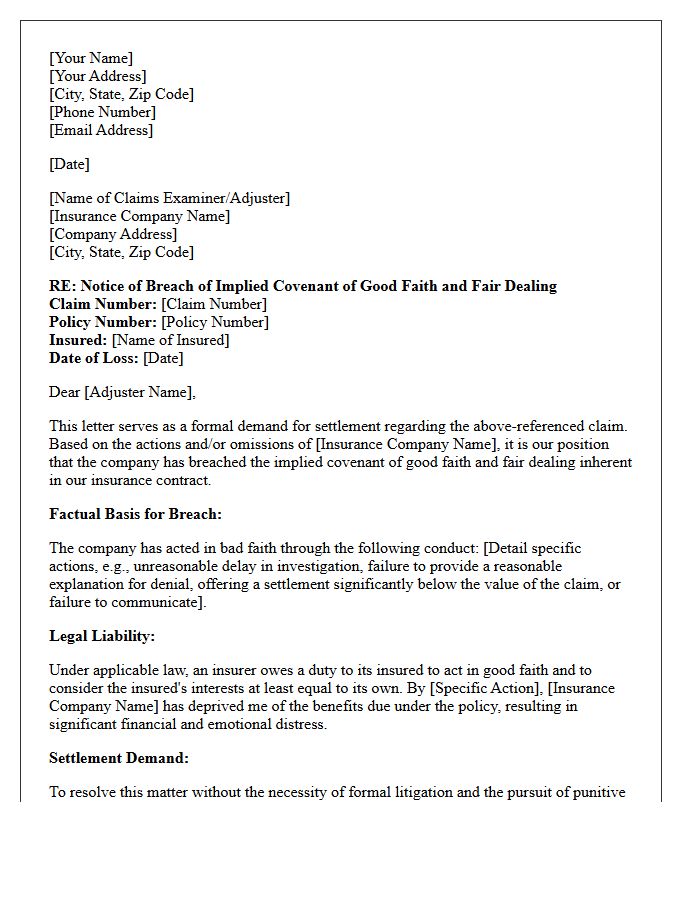
A breach of implied covenant bad faith settlement demand letter is a formal legal notice alleging an insurer failed its duty of good faith and fair dealing. This document highlights how the insurance company unreasonably denied or delayed a valid claim, prioritizing its interests over the policyholder's protection. By documenting specific failures in the settlement process, the letter serves as critical evidence for potential bad faith litigation, often seeking damages beyond policy limits to compensate for the insurer's tortious conduct and financial harm caused to the insured.
Deceptive Insurance Practices Bad Faith Demand Letter
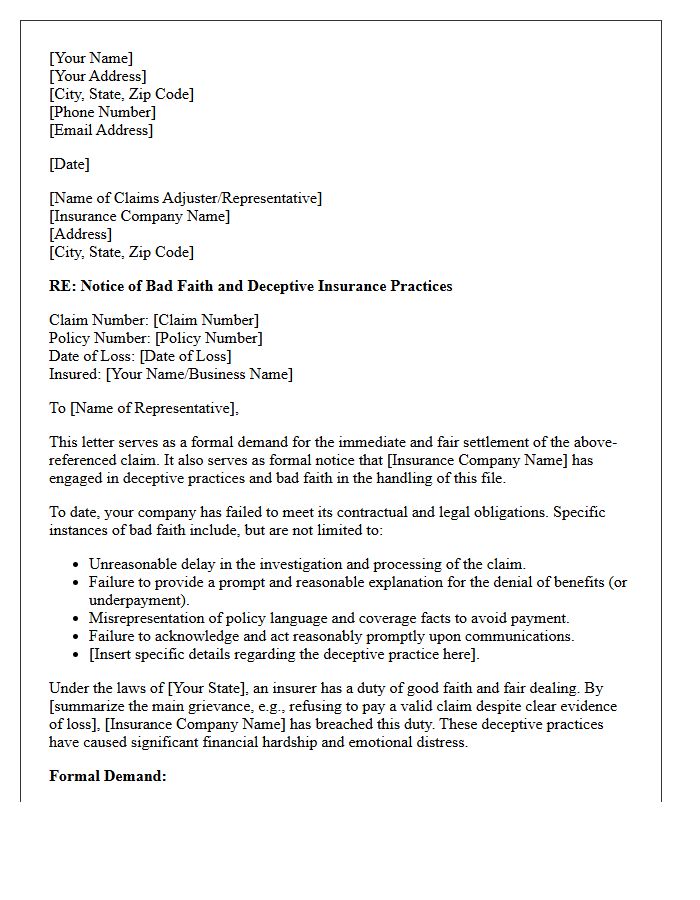
A Bad Faith Demand Letter is a formal legal notification sent to an insurer when they engage in deceptive insurance practices. This document outlines specific violations, such as unreasonable claim denials, intentional delays, or misrepresentation of policy terms. It serves as critical evidence that the company breached its fiduciary duty to the policyholder. By clearly detailing the insurer's failure to act in good faith, the letter creates a legal foundation for seeking punitive damages and extra-contractual compensation beyond the original policy limits during litigation.
Pre-Litigation Final Settlement Demand Bad Faith Letter
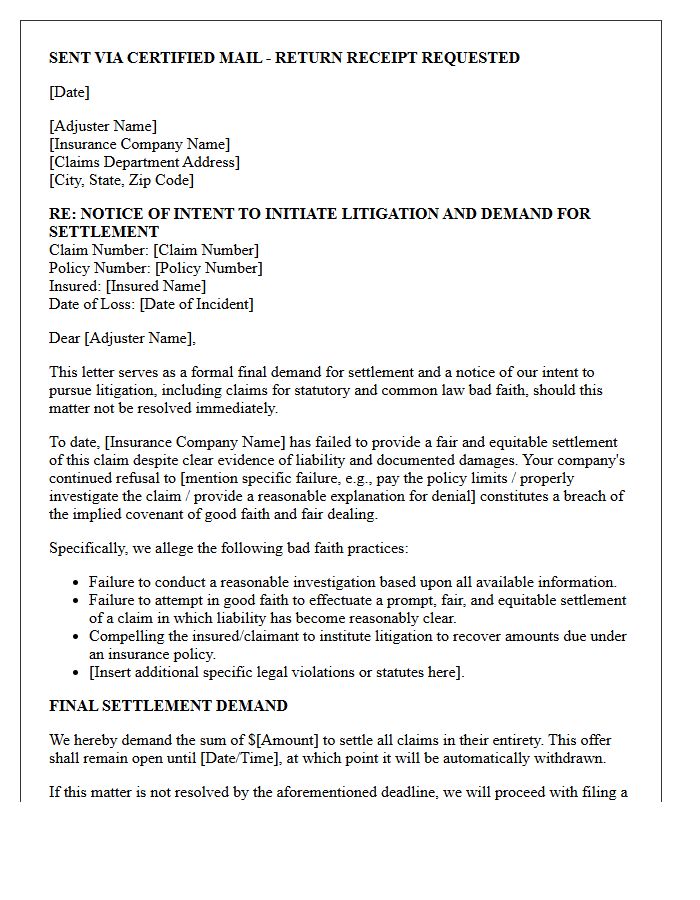
A Pre-Litigation Final Settlement Demand Bad Faith Letter is a formal notice sent to an insurance company before filing a lawsuit. It serves as a legal prerequisite to establish that the insurer is failing to settle a claim fairly within policy limits. By documenting the insurer's unreasonable delays or denials, this letter creates a paper trail for future bad faith litigation. It gives the company one final opportunity to resolve the claim, potentially exposing them to punitive damages and liability beyond the original policy coverage if they refuse a reasonable settlement.
First Party Property Damage Bad Faith Settlement Letter
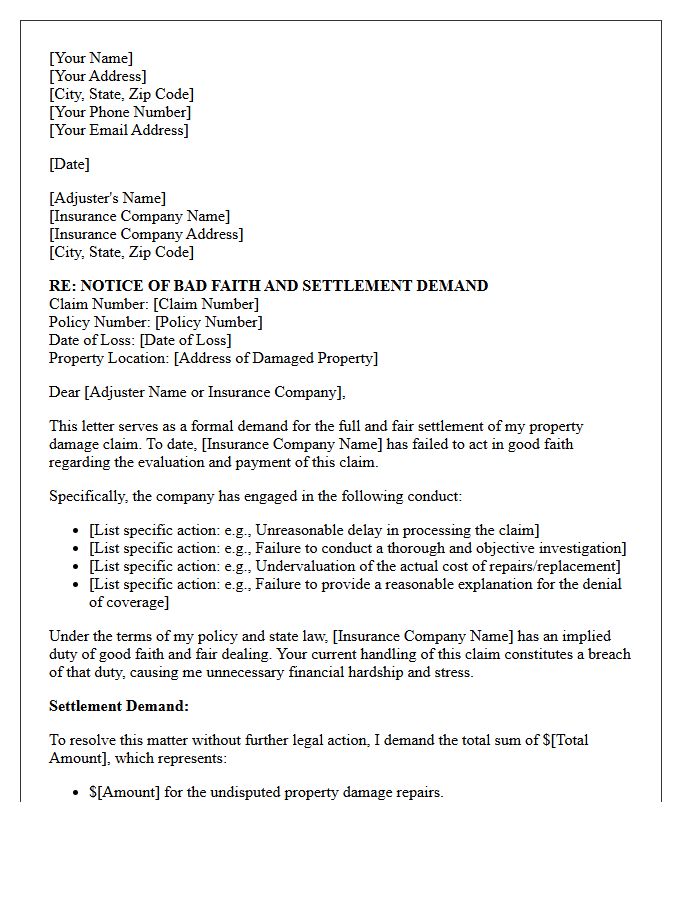
A First Party Property Damage Bad Faith Settlement Letter is a formal legal notice sent to an insurance company that has failed to act fairly. It documents specific instances of unreasonable delays, lowball offers, or wrongful denials of a claim. This letter serves as a final demand for a fair settlement before pursuing litigation. By citing statutory violations and evidence of breach of contract, the insured creates a necessary paper trail to hold the insurer liable for damages beyond the policy limits due to their dishonest conduct.
Third Party Liability Bad Faith Settlement Demand Letter
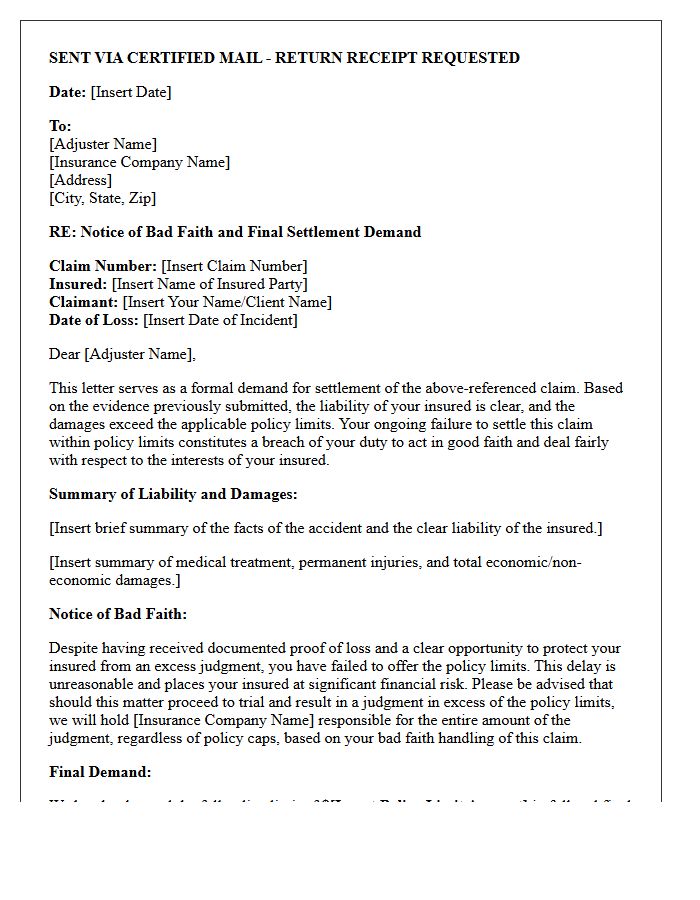
A Third Party Liability Bad Faith Settlement Demand Letter is a legal notification sent to an insurance company when they fail to settle a claim within policy limits. This document creates a time-limited opportunity for the insurer to resolve a valid claim fairly. If the insurer rejects a reasonable settlement, they may be held liable for the entire judgment amount, even if it exceeds the original policy coverage. This process protects victims by holding carriers accountable for unreasonable delays or bad faith negotiations during the claims process.
Unjustified Policy Rescission Bad Faith Demand Letter
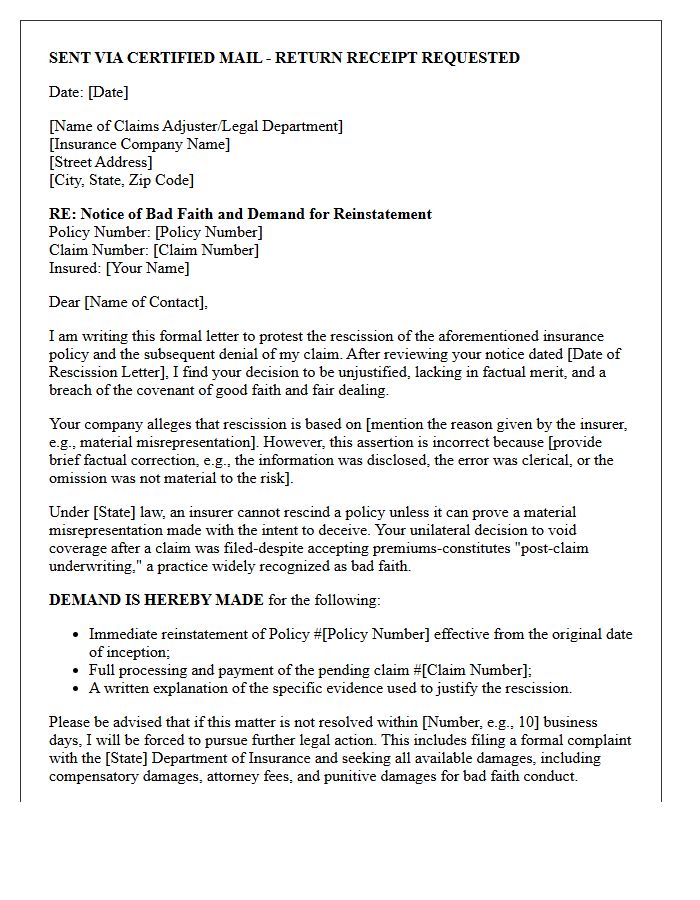
An Unjustified Policy Rescission Bad Faith Demand Letter is a formal legal notice issued when an insurer wrongfully cancels a policy to avoid paying a valid claim. The letter asserts that the company's retroactive termination lacks a factual or legal basis, violating the covenant of good faith and fair dealing. It serves as a prerequisite for litigation, demanding immediate reinstatement of coverage and payment of benefits. Highlighting specific bad faith conduct can pressure insurers to settle and may entitle the policyholder to additional punitive damages for financial losses.
Failure To Communicate Claim Status Bad Faith Demand Letter
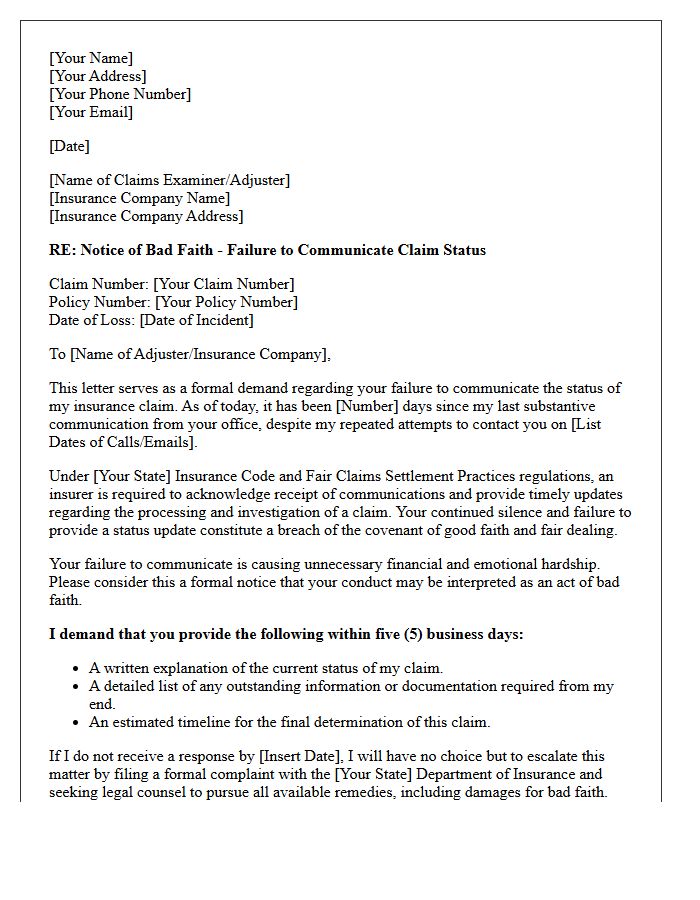
A Failure To Communicate Claim Status constitutes a primary element of insurance bad faith. When an insurer ignores inquiries or fails to provide timely updates regarding a pending claim, they violate their fiduciary duty. Issuing a formal Bad Faith Demand Letter is a critical legal step to document these communication lapses and demand prompt resolution. This letter serves as essential evidence for potential litigation, holding the insurance company accountable for unreasonable delays and ensuring they adhere to the implied covenant of good faith and fair dealing.
Wrongful Withholding Of Policy Benefits Bad Faith Letter
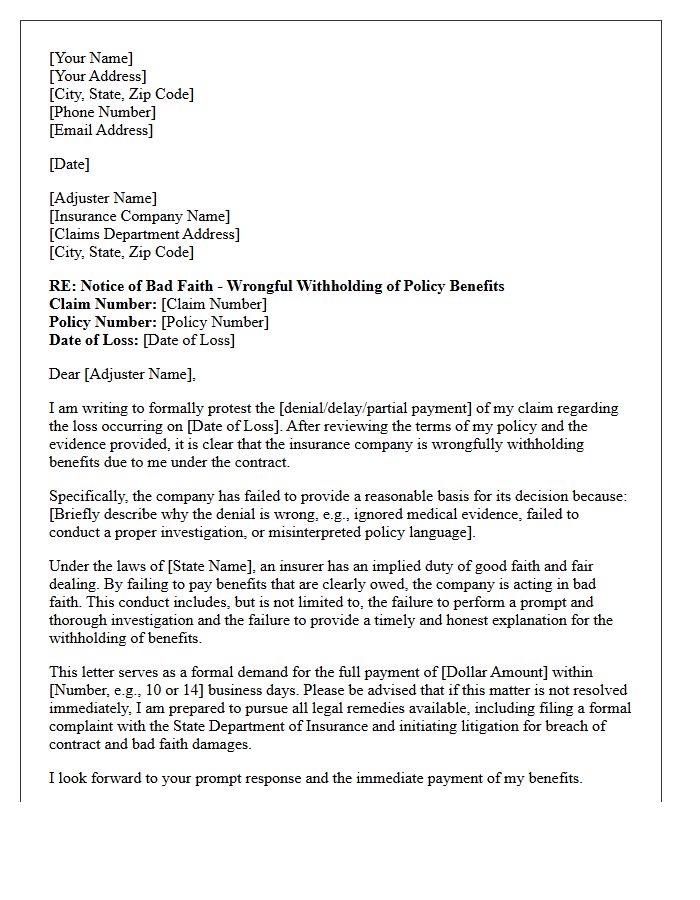
A Wrongful Withholding of Policy Benefits Bad Faith Letter is a formal legal demand sent to an insurance provider. It asserts that the insurer breached its duty of good faith and fair dealing by unreasonably denying or delaying valid claims. This document outlines specific policy violations and warns of potential litigation for extra-contractual damages. Properly drafting this letter is crucial to hold insurers accountable for unfair claims practices and to compel the immediate payment of owed benefits while establishing a record of the company's misconduct.
Statutory Unfair Claims Practices Bad Faith Demand Letter
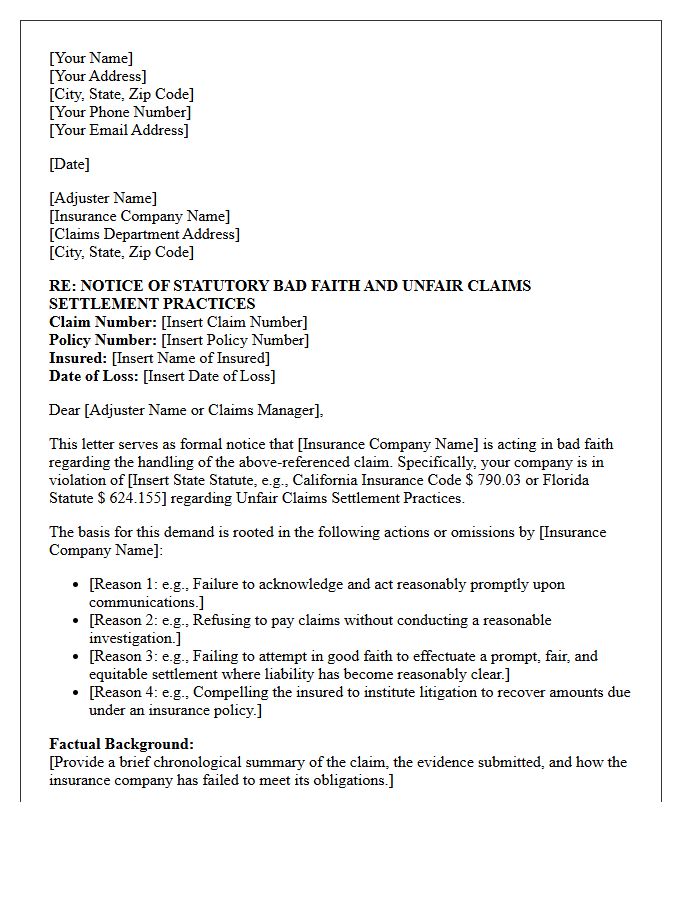
A Statutory Unfair Claims Practices Bad Faith Demand Letter is a formal legal notice notifying an insurer of specific violations of state insurance codes. It serves as a mandatory prerequisite for litigation, detailing how the company failed to settle a claim fairly or promptly. The letter must clearly outline the facts and legal grounds for the bad faith claim, providing the insurer a final opportunity to cure the breach. Properly drafting this document is essential to securing punitive damages and holding insurance companies accountable for deceptive or obstructive settlement behaviors.
What is a bad faith insurance claim settlement demand letter?
A bad faith insurance demand letter is a formal legal document sent to an insurer notifying them that they have breached their duty of good faith and fair dealing. It outlines specific instances of claim mishandling, cites relevant state statutes, and demands a fair settlement to avoid further litigation or punitive damages.
What evidence should be included in a bad faith demand letter?
To be effective, the letter should include a detailed timeline of communication, copies of denied claim notices, evidence of unreasonable delays, documentation of inadequate investigations, and proof of the actual damages incurred. Referencing internal claim file inconsistencies can also strengthen the allegation of bad faith.
When should you send a demand letter for an insurer's bad faith?
You should send a bad faith demand letter when an insurance company unreasonably denies a valid claim, fails to provide a timely explanation for a denial, offers a "lowball" settlement significantly below the policy value, or fails to conduct a thorough and objective investigation into the loss.
How long does an insurance company have to respond to a bad faith demand?
While response times vary by state law, most demand letters specify a deadline of 14 to 30 days. Providing a clear timeframe creates a "time-limit demand," which can be used later in court to prove the insurer had a reasonable opportunity to rectify their conduct but chose not to.
Can a bad faith demand letter increase a settlement amount?
Yes, a well-drafted bad faith demand letter can significantly increase a settlement because it signals to the insurer that you are prepared to pursue extra-contractual damages. This may include compensation for emotional distress, attorney fees, and punitive damages that exceed the original policy limits.
Comments