A Notice of Non-Renewal occurs when an insurance company stops coverage because of a change in underwriting guidelines. This often results from updated risk assessments or shifts in company policy rather than your personal claims history. Understanding these legal notices is essential for maintaining continuous protection. To help you communicate effectively, below are some ready to use templates.
Image cover: Official Notice: Policy Non-Renewal Based on Updated Underwriting Guidelines
Letter Samples List
- Commercial Property Underwriting Change Non-Renewal Letter
- Personal Auto Underwriting Risk Revision Non-Renewal Letter
- Homeowners Insurance Underwriting Guideline Non-Renewal Letter
- Workers Compensation Underwriting Shift Non-Renewal Letter
- Professional Liability Underwriting Restructure Non-Renewal Letter
- General Liability Policy Underwriting Update Non-Renewal Letter
- Cyber Insurance Risk Appetite Change Non-Renewal Letter
- Inland Marine Underwriting Guideline Shift Non-Renewal Letter
- Umbrella Policy Underwriting Criteria Change Non-Renewal Letter
- Business Owners Policy Underwriting Adjustment Non-Renewal Letter
- Directors and Officers Underwriting Guideline Change Non-Renewal Letter
- Commercial Auto Insurance Underwriting Modification Non-Renewal Letter
Commercial Property Underwriting Change Non-Renewal Letter
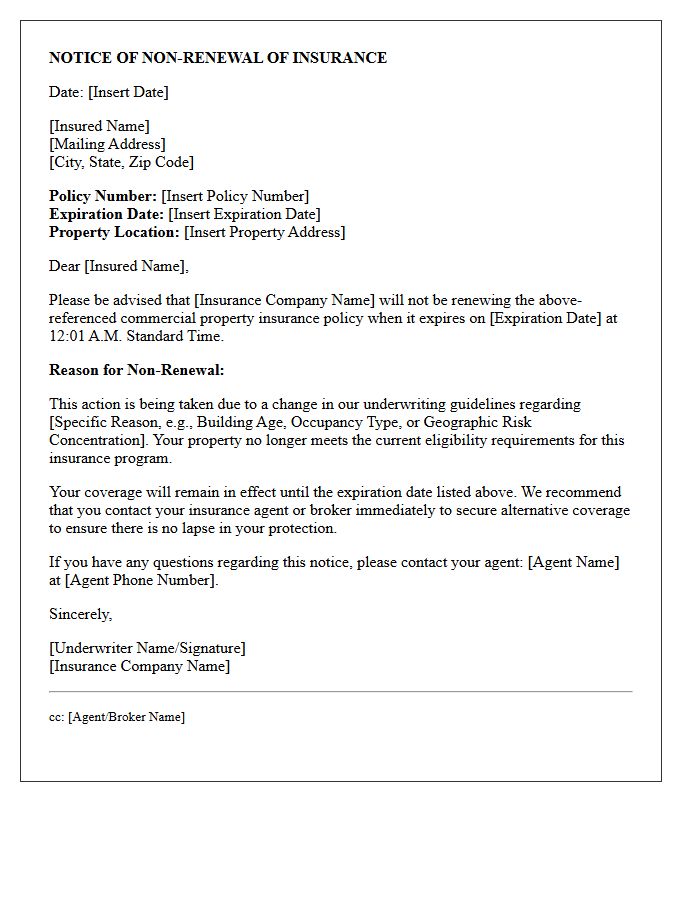
A commercial property underwriting change non-renewal letter notifies policyholders that their coverage will terminate due to specific risk adjustments. These notices often result from increased risk exposure, substantial claims history, or shifts in the insurer's underwriting guidelines. It is crucial to review the effective date and the specific reasons provided to seek alternative coverage promptly. Insurers must adhere to state-mandated notice periods, typically thirty to sixty days, ensuring businesses have adequate time to mitigate potential gaps in protection and maintain financial stability during the transition.
Personal Auto Underwriting Risk Revision Non-Renewal Letter
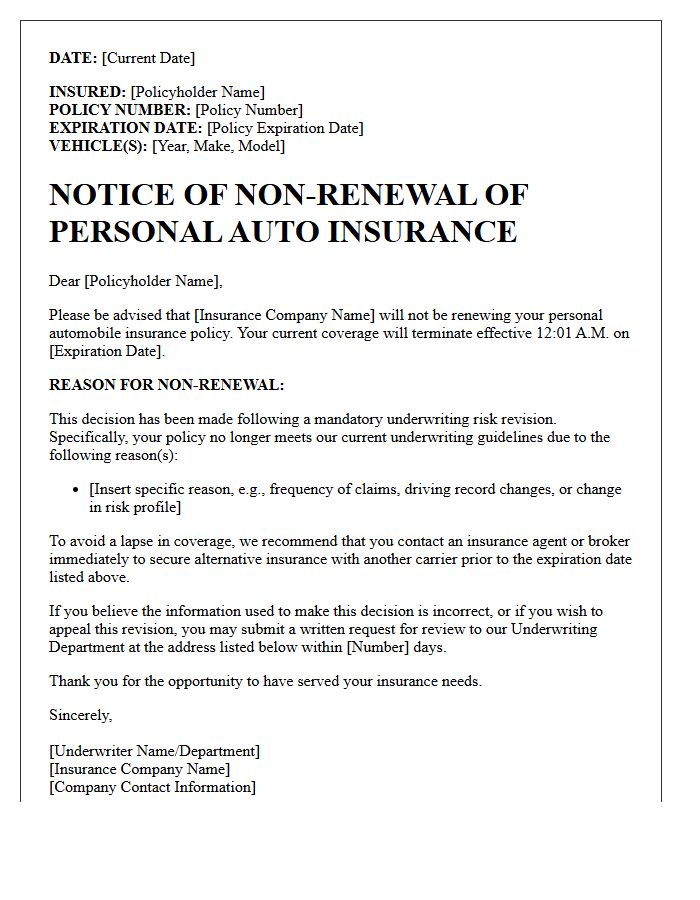
A Personal Auto Underwriting Risk Revision Non-Renewal Letter is a formal notification that an insurer will not extend coverage past the current term. This typically occurs after a comprehensive risk assessment identifies factors like frequent claims, serious traffic violations, or undisclosed drivers. The letter must provide a specific reason for the decision and state the exact policy expiration date. To maintain continuous protection, policyholders should immediately seek alternative coverage and review their CLUE report for any inaccuracies contributing to the non-renewal status.
Homeowners Insurance Underwriting Guideline Non-Renewal Letter
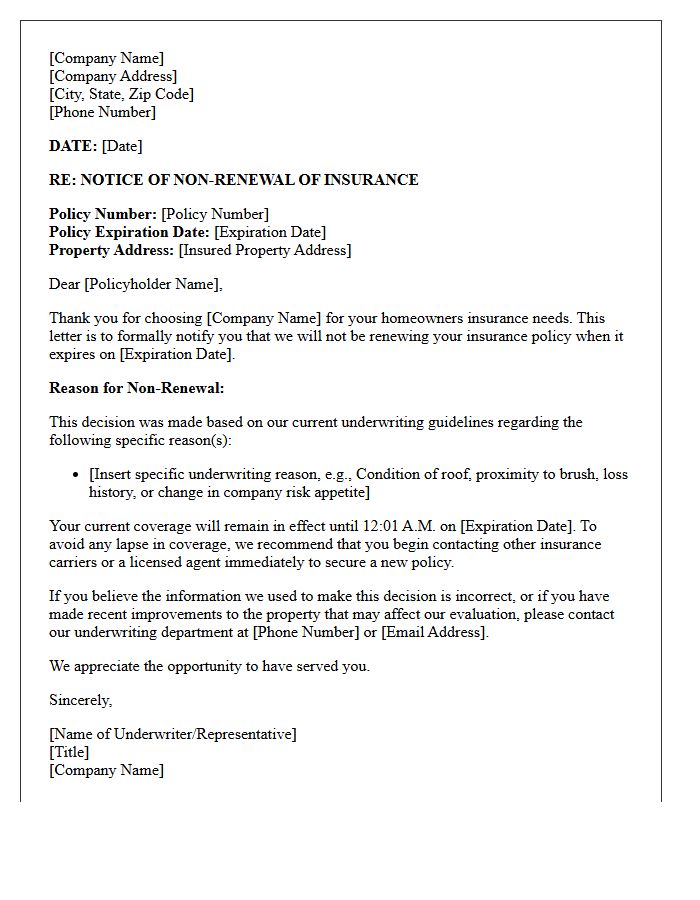
A Homeowners Insurance Underwriting Guideline Non-Renewal Letter is a formal notice stating that your insurer will not extend coverage past the current term. This typically occurs due to risk eligibility changes, such as poor roof condition, excessive claims history, or high-hazard liabilities on the property. Receiving this document requires immediate action to prevent a lapse in coverage. Review the specific reasons cited to determine if remediation is possible or if you must secure a new policy through a different carrier before the expiration date.
Workers Compensation Underwriting Shift Non-Renewal Letter
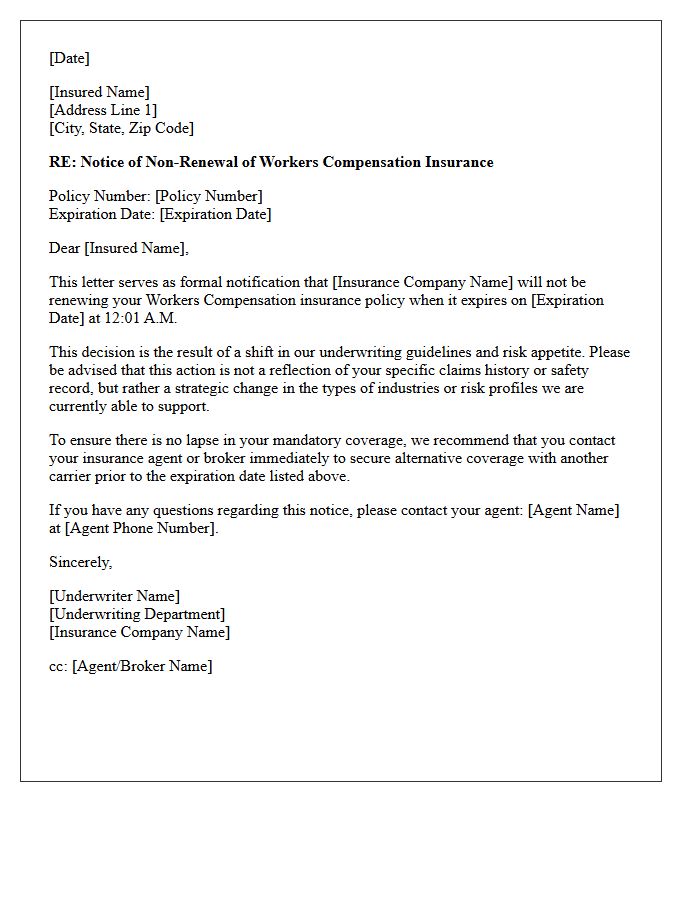
A Workers Compensation Underwriting Shift Non-Renewal Letter notifies policyholders that their coverage will terminate due to changes in a carrier's risk appetite or strategic market withdrawal. This notice is often unrelated to the insured's claims history, focusing instead on the insurer's internal reclassification of eligible industries. Upon receiving this formal document, businesses must immediately seek alternative coverage to avoid a lapse. It is essential to review the effective date and specific underwriting criteria cited to ensure a seamless transition to a new insurance provider before the current policy expires.
Professional Liability Underwriting Restructure Non-Renewal Letter
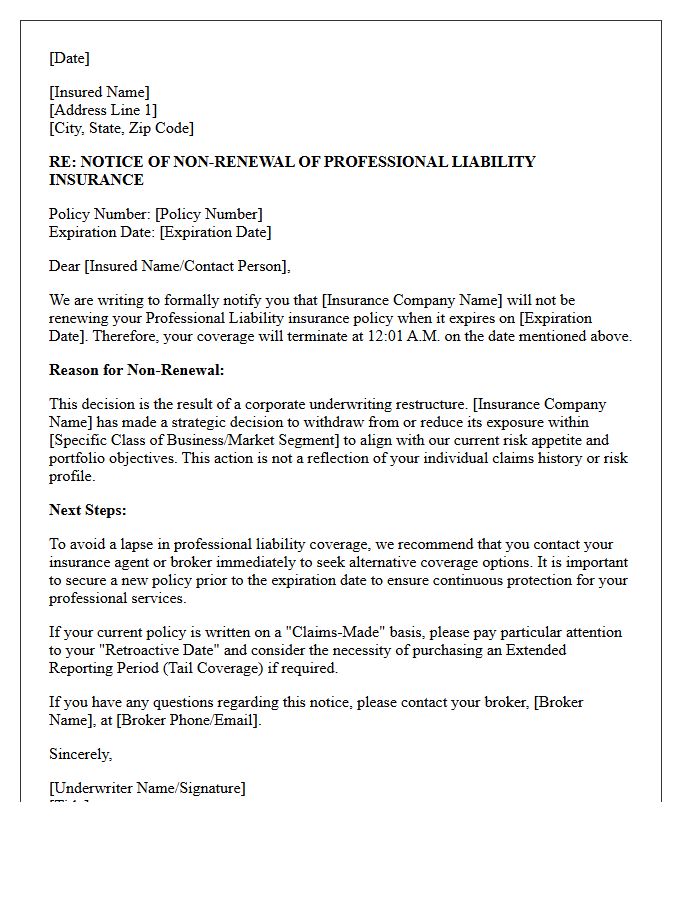
A professional liability underwriting restructure non-renewal letter notifies policyholders that their current coverage will not be renewed due to portfolio rebalancing. This formal notice often indicates the insurer is exiting a specific market or adjusting risk appetite. It is legally required to provide advance warning, allowing the insured to seek alternative protection. Receiving this letter does not necessarily reflect the client's claim history; rather, it highlights a strategic shift in the carrier's underwriting guidelines. Reviewing the effective date immediately is essential to avoid a lapse in professional indemnity coverage.
General Liability Policy Underwriting Update Non-Renewal Letter
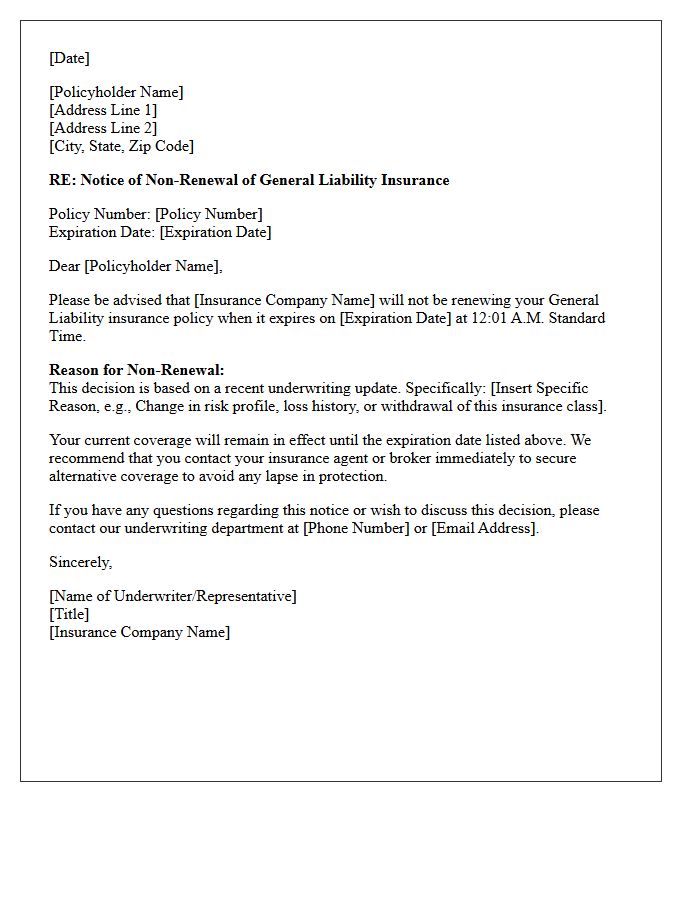
Receiving a General Liability Policy Underwriting Update Non-Renewal Letter means your insurer will not extend coverage past the current expiration date. This usually results from an increased risk profile, frequent claims, or changes in the carrier's appetite for certain industries. It is crucial to review the underwriting reasons provided to address safety concerns or operational gaps. To avoid a lapse in coverage, immediately begin seeking quotes from alternative markets, as non-renewals can signal to new insurers that your business requires a higher level of risk management scrutiny.
Cyber Insurance Risk Appetite Change Non-Renewal Letter
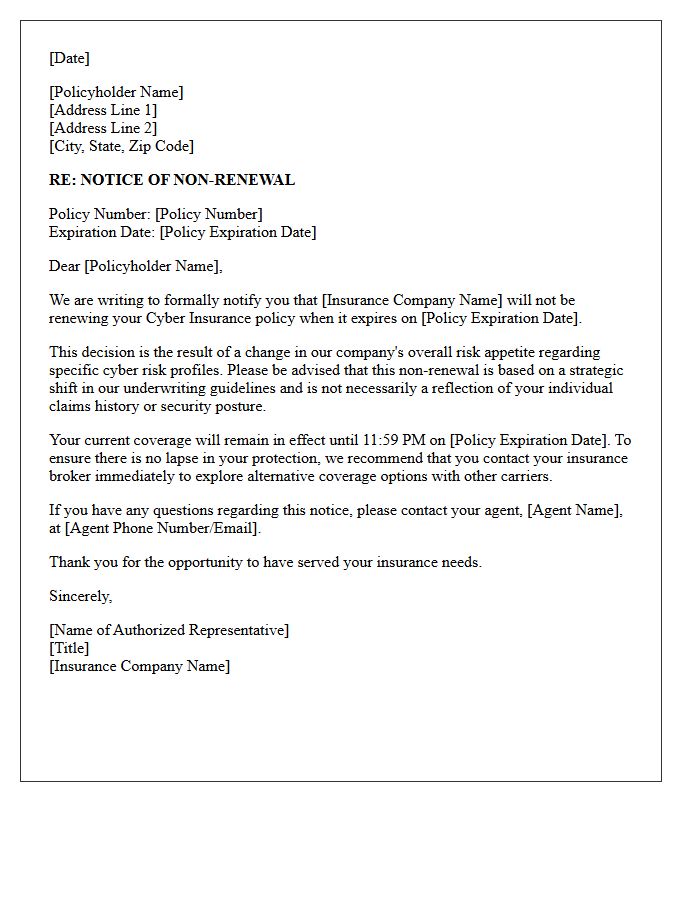
Receiving a non-renewal letter for cyber insurance often signals a shift in the carrier's risk appetite. Insurers are tightening underwriting standards due to rising ransomware frequency and systemic threats. To maintain coverage, organizations must demonstrate robust security controls, such as multi-factor authentication and encrypted backups. If your policy is terminated, it is critical to perform a gap analysis and upgrade cybersecurity protocols immediately. Addressing these vulnerabilities is essential to securing a new policy in a hardening market where risk mitigation is the primary requirement for insurability.
Inland Marine Underwriting Guideline Shift Non-Renewal Letter
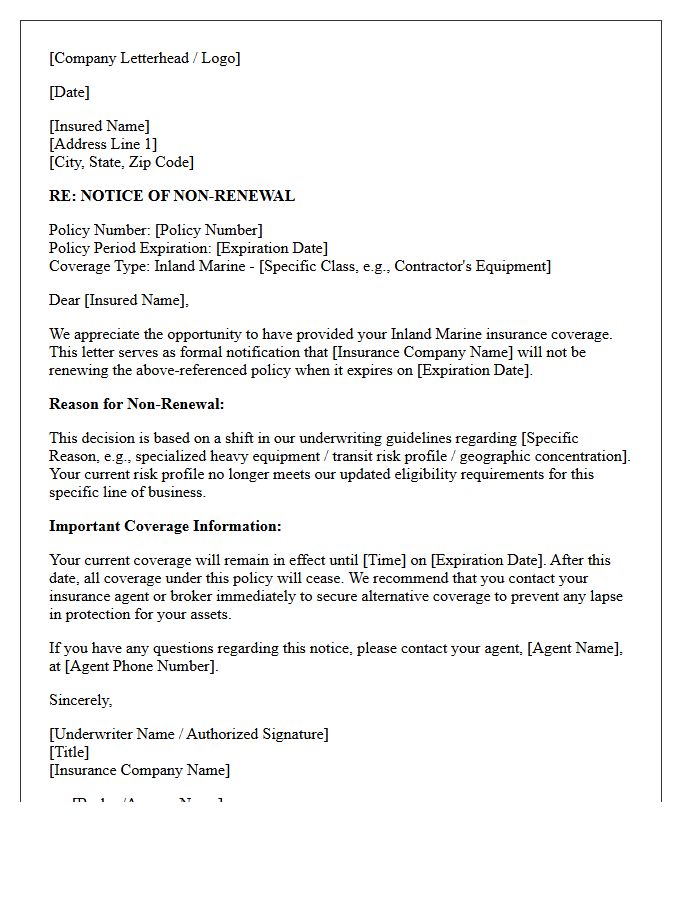
An Inland Marine Underwriting Guideline Shift Non-Renewal Letter notifies policyholders that their coverage will not be extended due to strategic changes in risk appetite. This formal notice must clearly cite the specific underwriting criteria revisions, such as narrowed class eligibility or geographic restrictions. To ensure compliance, the letter must be issued within state-mandated timeframes and include details regarding the effective expiration date. Documenting these shifts helps insurers manage portfolio exposure while providing insureds necessary time to secure alternative coverage through different markets or specialty providers.
Umbrella Policy Underwriting Criteria Change Non-Renewal Letter
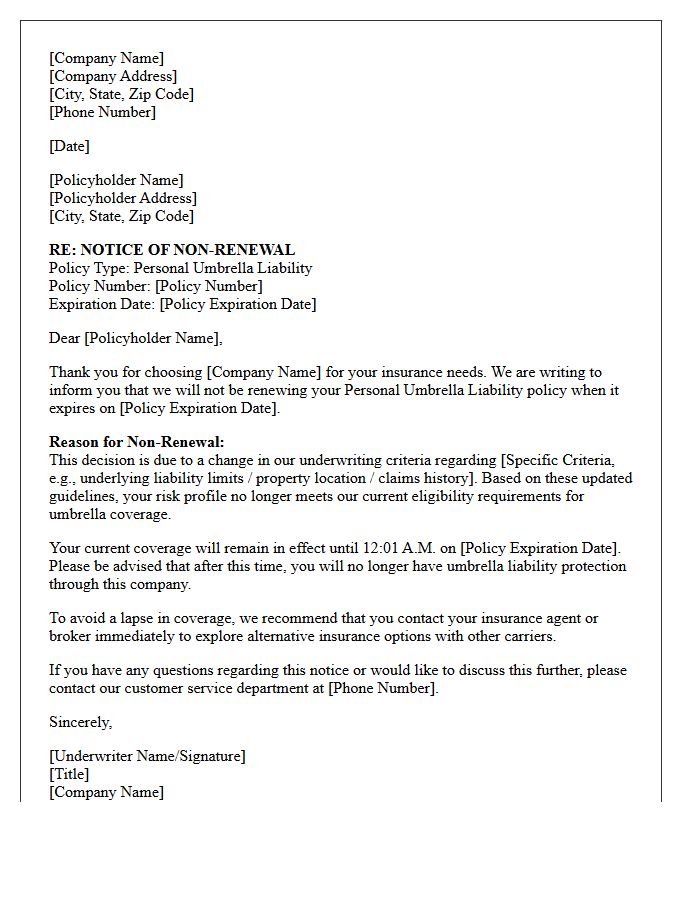
An Umbrella Policy Non-Renewal Letter notifies policyholders that their coverage will not continue due to updated underwriting criteria. These changes often stem from increased risk exposure, a history of claims, or shifts in company risk appetite. To maintain protection, you must review the specific reasons cited and promptly seek alternative coverage to avoid a lapse in liability protection. Consulting an agent is essential to finding a new carrier that accommodates the revised guidelines while ensuring your underlying home and auto limits meet the necessary eligibility requirements for a new umbrella policy.
Business Owners Policy Underwriting Adjustment Non-Renewal Letter
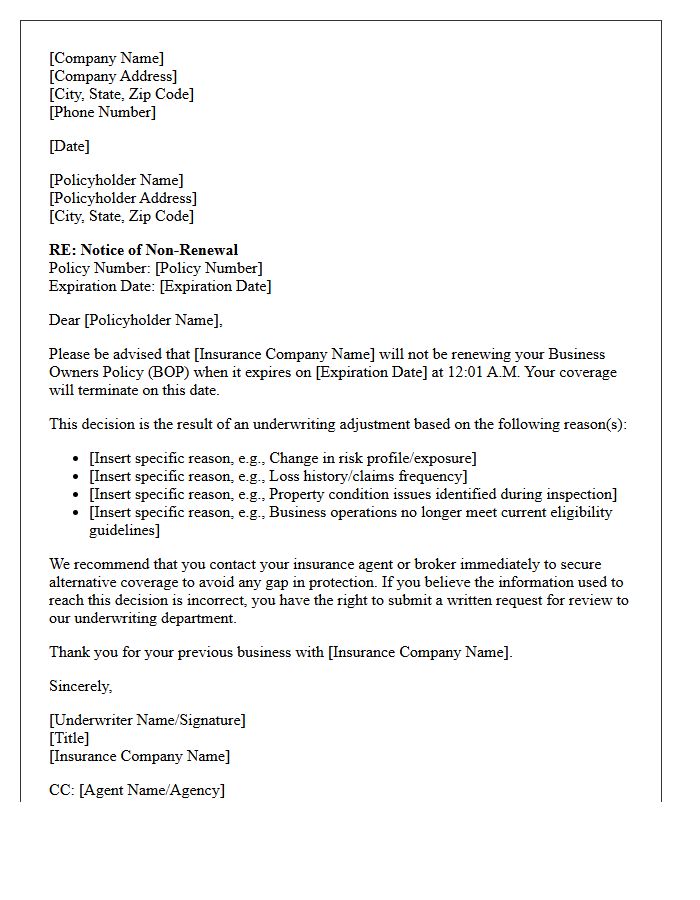
A Business Owners Policy Underwriting Adjustment Non-Renewal Letter notifies policyholders that their coverage will not be extended past the current term due to underwriting criteria changes. This formal notice indicates the insurer has reassessed the risk profile, often due to claims history, hazardous operations, or shifts in risk appetite. It is crucial to review the effective date immediately to avoid a lapse in protection. Upon receipt, business owners should seek alternative coverage options or consult an agent to address the specific eligibility requirements cited for the non-renewal decision.
Directors and Officers Underwriting Guideline Change Non-Renewal Letter
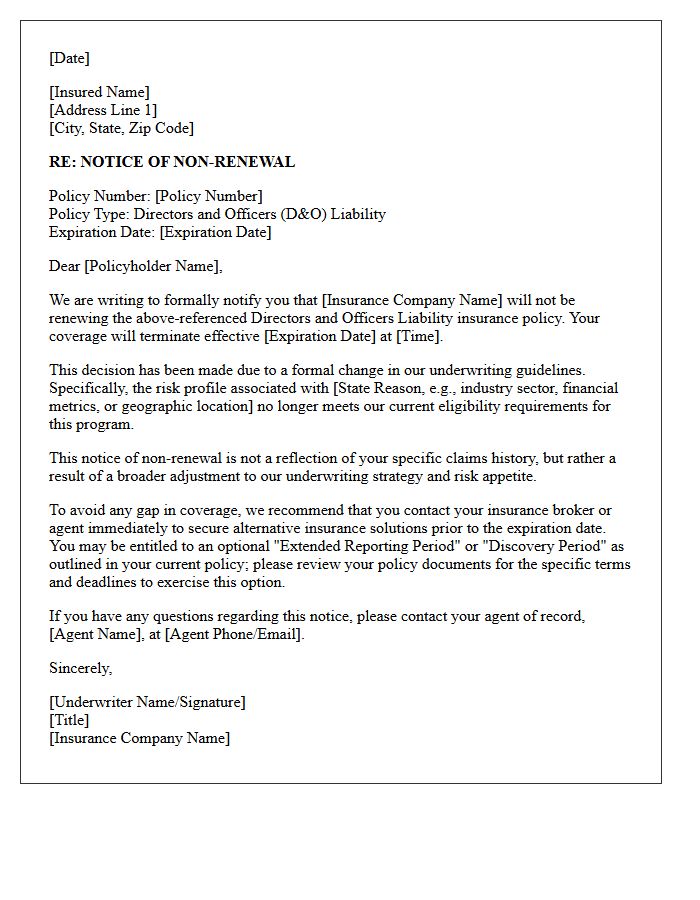
A Directors and Officers (D&O) non-renewal letter informs policyholders that their coverage will not continue under current terms due to specific underwriting guideline changes. These adjustments often stem from shifts in risk appetite, financial instability, or claims history. It is critical to review the notice period required by state law to ensure compliance. Companies receiving this letter must promptly seek alternative markets to avoid gaps in protection. Understanding the underlying reasons for the change helps in negotiating better terms or improving corporate governance to satisfy new risk requirements.
Commercial Auto Insurance Underwriting Modification Non-Renewal Letter
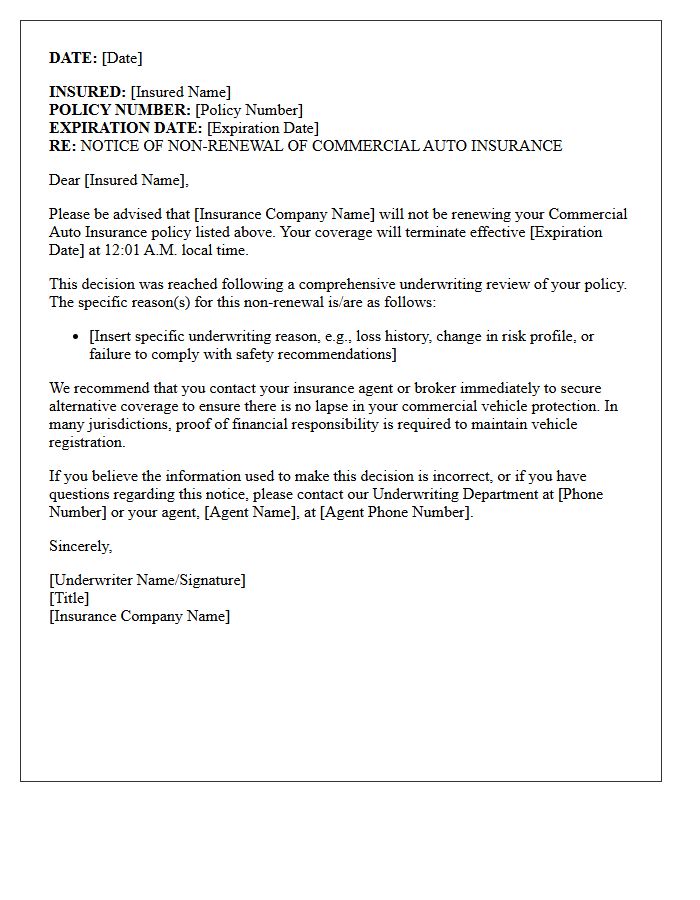
A Commercial Auto Insurance Underwriting Modification Non-Renewal Letter notifies policyholders that their current coverage will not be extended due to specific risk changes. This legal notice typically highlights material changes in business operations, poor loss history, or increased vehicle risk profiles. Carriers use these letters to propose modified terms, such as higher deductibles or restricted driver lists, as a condition for future coverage. Policyholders must respond promptly to address underwriting concerns or seek alternative insurance placement to avoid coverage gaps before the existing policy expiration date.
What does a "Notice of Non-Renewal Due to Change in Underwriting Guidelines" mean?
This notice indicates that your insurance provider is updating the internal criteria used to determine which risks they are willing to cover. Because your policy no longer aligns with these newly established eligibility requirements, the insurer will not offer a renewal contract once your current policy term expires.
Is a non-renewal due to underwriting changes the same as a cancellation?
No, a non-renewal is different from a cancellation. A cancellation terminates a policy before its expiration date, often due to non-payment or fraud. A non-renewal simply means the relationship will end naturally at the end of the current policy period, and it is usually not a reflection of your personal claim history or credit.
Can I dispute a non-renewal based on updated underwriting guidelines?
While underwriting guidelines are proprietary business decisions, you have the right to request a specific explanation of which guideline you no longer meet. If you believe the data used to make the decision is inaccurate, you can provide corrective documentation to your insurer, though they are generally not legally obligated to renew the policy if their risk appetite has changed.
How much notice must an insurer provide before non-renewing a policy?
Notice requirements vary by state law and policy type, but insurers are typically required to provide a written notice 30 to 60 days before the policy expiration date. This window is designed to give policyholders sufficient time to shop for alternative coverage and avoid a lapse in protection.
Will this non-renewal make it harder for me to find insurance with another company?
Generally, a non-renewal due to a change in corporate underwriting guidelines does not negatively impact your "insurability" with other carriers. Since the decision was driven by the company's internal shift in risk strategy rather than your personal behavior or high claim volume, other insurers will evaluate you based on their own specific criteria.
Comments