Managing rental income requires consistent cash flow. When a tenant demonstrates a chronic late payment history, issuing a formal non-renewal notice becomes a necessary business decision to protect your investment. This guide explores the legal considerations and professional steps for ending a tenancy due to payment instability. To help you communicate clearly, below are some ready to use template.
Image cover: Notice of Lease Non-Renewal: Consistent Late Payment History
Letter Samples List
- Commercial Auto Insurance Non-Renewal Letter Due to Late Payments
- Homeowners Policy Non-Renewal Letter for Chronic Late Payment History
- Notice of Non-Renewal Letter for General Liability Premium Delinquency
- Chronic Late Payment Non-Renewal Letter for Workers Compensation Policy
- Personal Auto Insurance Policy Non-Renewal Letter for Payment History
- Commercial Property Insurance Non-Renewal Letter Due to Premium Delinquency
- Business Owner Policy Non-Renewal Letter for Chronic Late Payments
- Umbrella Policy Non-Renewal Letter Due to Unfavorable Payment History
- Term Life Insurance Non-Renewal Letter for Consistent Late Payments
- Renters Insurance Policy Non-Renewal Letter for Premium Payment Issues
- Professional Liability Non-Renewal Letter Due to Chronic Late Payments
- Cyber Liability Policy Non-Renewal Letter for Consistent Payment Delinquency
- Errors and Omissions Policy Non-Renewal Letter for Delinquent Payments
Commercial Auto Insurance Non-Renewal Letter Due to Late Payments
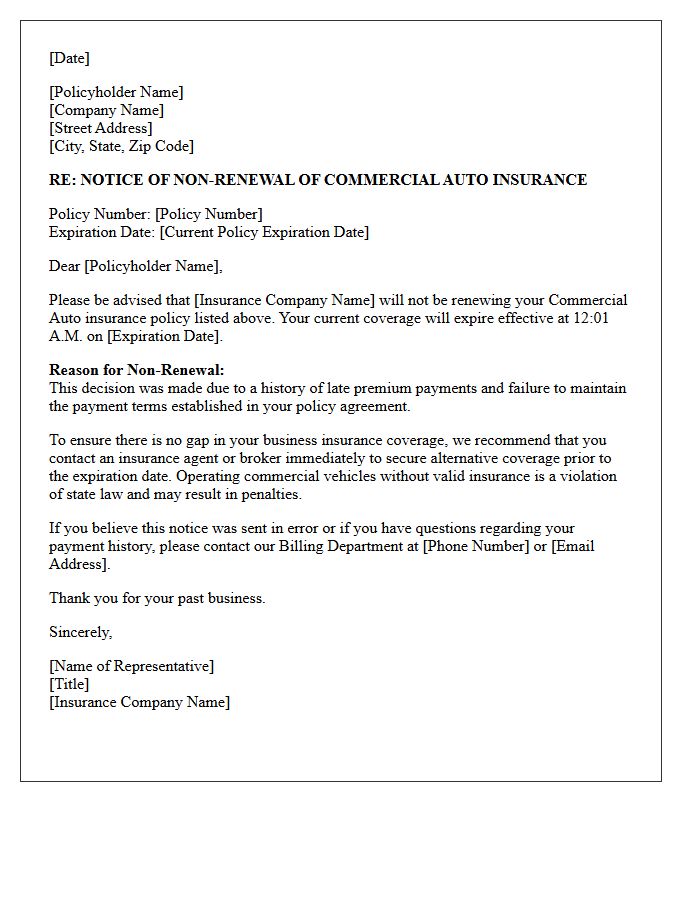
Receiving a commercial auto insurance non-renewal letter due to late payments indicates your insurer will not extend coverage past the current policy expiration. This action results from chronic payment delinquency, signaling a higher financial risk to the provider. To maintain legal compliance and protect your business fleet, you must secure a new policy immediately to avoid a coverage gap. Be aware that a history of late payments may lead to higher premiums or placement with non-standard carriers, as most standard insurers prioritize clients with consistent payment histories.
Homeowners Policy Non-Renewal Letter for Chronic Late Payment History
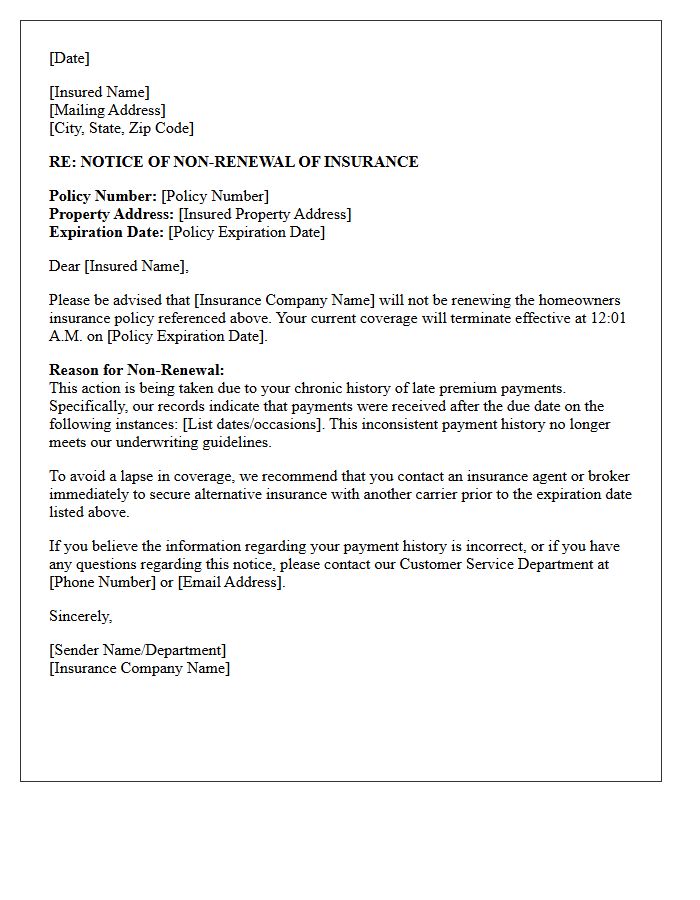
Receiving a non-renewal letter due to chronic late payments means your insurer has decided to terminate your coverage at the end of the current term. This occurs because inconsistent payment history signals high financial risk. To protect your property, you must secure new coverage immediately to avoid a lapses in insurance, which can trigger force-placed policies from mortgage lenders. Improving your credit score and setting up automated payments are essential steps to demonstrate reliability to future providers and secure more affordable premiums in the high-risk market.
Notice of Non-Renewal Letter for General Liability Premium Delinquency
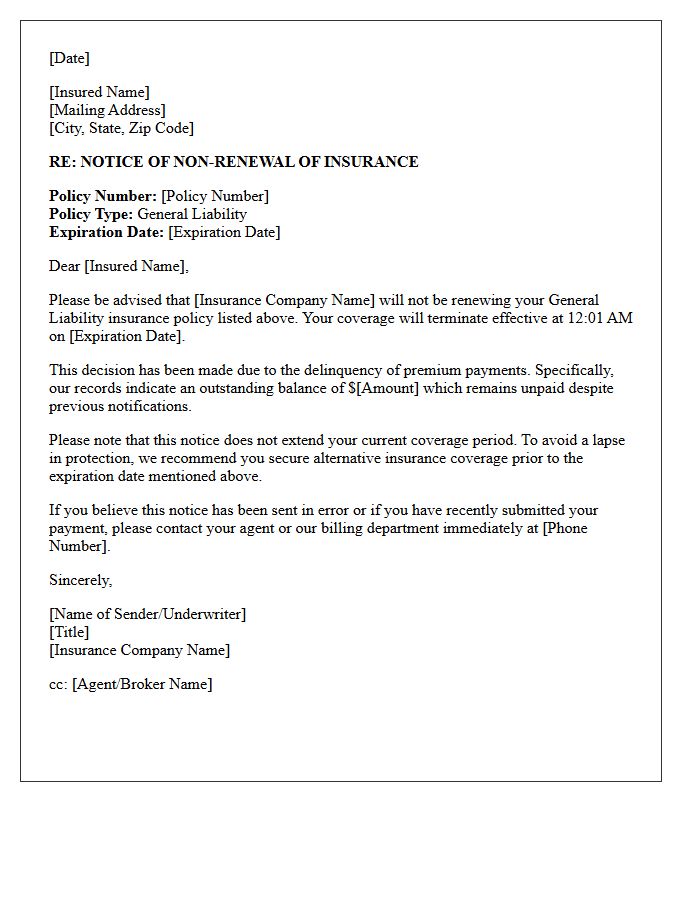
A Notice of Non-Renewal for premium delinquency is a formal legal alert stating that your general liability insurance will not be extended past the current expiration date. This action occurs when an insured fails to pay agreed premiums on time. To maintain continuous coverage and avoid risky protection gaps, you must settle outstanding balances immediately. Receiving this notice can negatively impact your risk profile, making it harder or more expensive to secure future policies. Always prioritize timely payments to ensure your business remains legally protected and financially secure.
Chronic Late Payment Non-Renewal Letter for Workers Compensation Policy
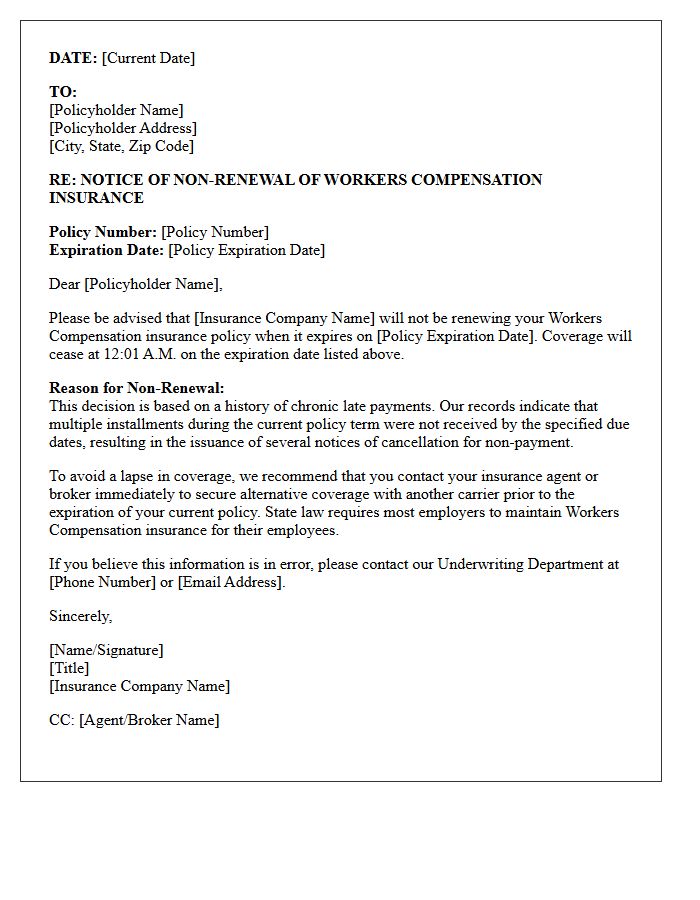
A chronic late payment non-renewal letter is a formal notice from an insurance carrier stating they will not extend Workers' Compensation coverage due to persistent delinquency. This document signifies that repeated failure to meet payment deadlines has made the policyholder a high-risk client. Receiving this notice is critical because it leads to a coverage gap, potentially triggering state penalties or legal liabilities. To maintain protection, employers must prioritize timely premium payments to avoid being forced into assigned risk pools with significantly higher costs and more restrictive terms.
Personal Auto Insurance Policy Non-Renewal Letter for Payment History
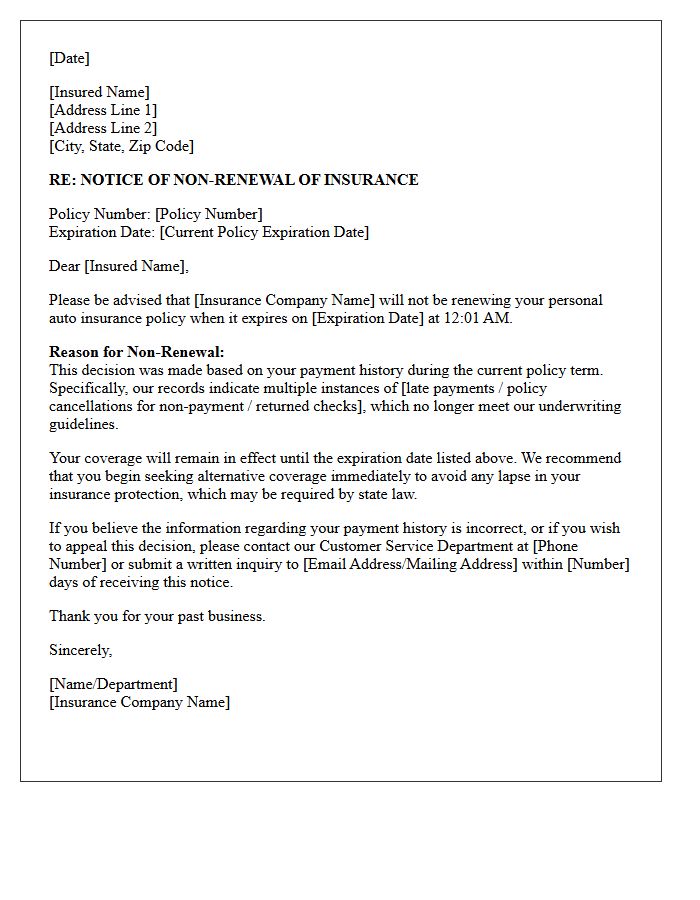
Receiving a non-renewal letter for payment history indicates your insurer will not extend coverage past the current term due to consistent late payments. This adverse action can lead to a coverage lapse, making you a high-risk driver to future carriers and significantly increasing your premiums. To maintain protection, immediately review your reinstatement options or secure a new policy before the expiration date. Maintaining a continuous insurance record is essential for legal compliance and securing competitive rates in the future. Always prioritize timely payments to avoid non-renewal risks.
Commercial Property Insurance Non-Renewal Letter Due to Premium Delinquency
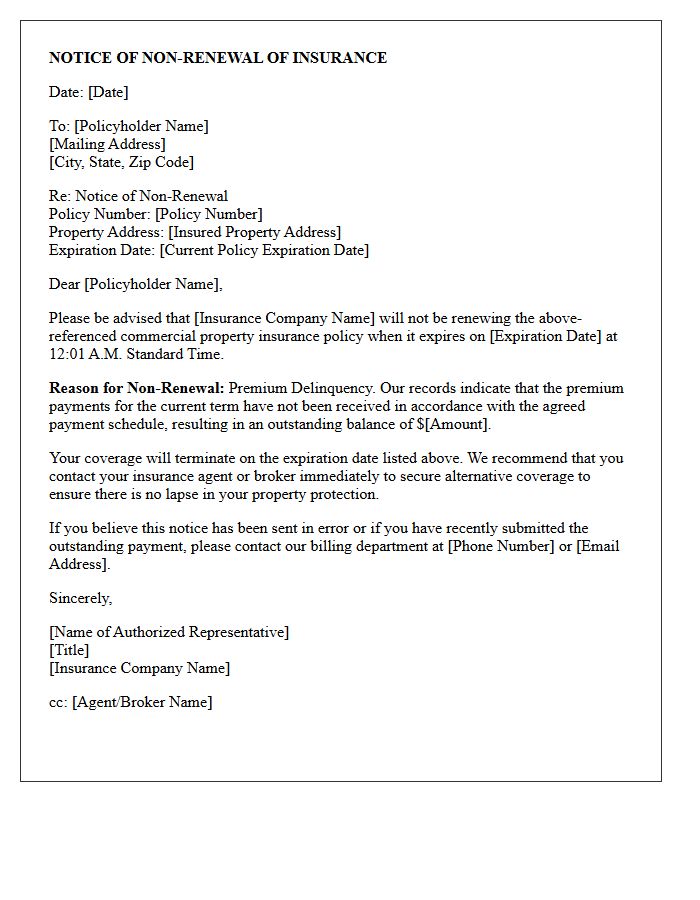
Receiving a commercial property insurance non-renewal letter due to premium delinquency indicates the insurer will not extend coverage past the current expiration date. This notice is triggered by unpaid premiums, creating a high-risk profile for the business. It is critical to act immediately to avoid a lapse in coverage, which can lead to legal penalties and higher future rates. Business owners should contact their broker to negotiate a reinstatement or secure alternative protection quickly to ensure continuous asset security and operational compliance.
Business Owner Policy Non-Renewal Letter for Chronic Late Payments
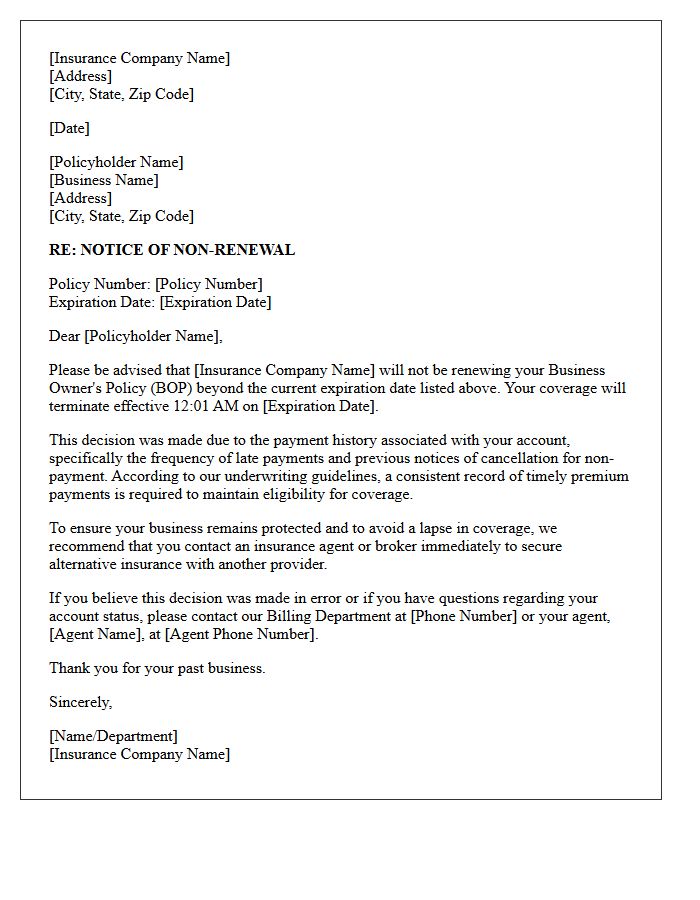
Receiving a Business Owner Policy (BOP) non-renewal letter due to chronic late payments indicates that your insurer considers you a high-risk client. Unlike a cancellation, non-renewal occurs at the end of the policy term, meaning coverage will cease entirely on the expiration date. It is critical to secure replacement insurance immediately to avoid a coverage gap, which can lead to higher premiums or denial from new carriers. To protect your business, prioritize consistent payment history to maintain eligibility for standard commercial rates and comprehensive protection.
Umbrella Policy Non-Renewal Letter Due to Unfavorable Payment History
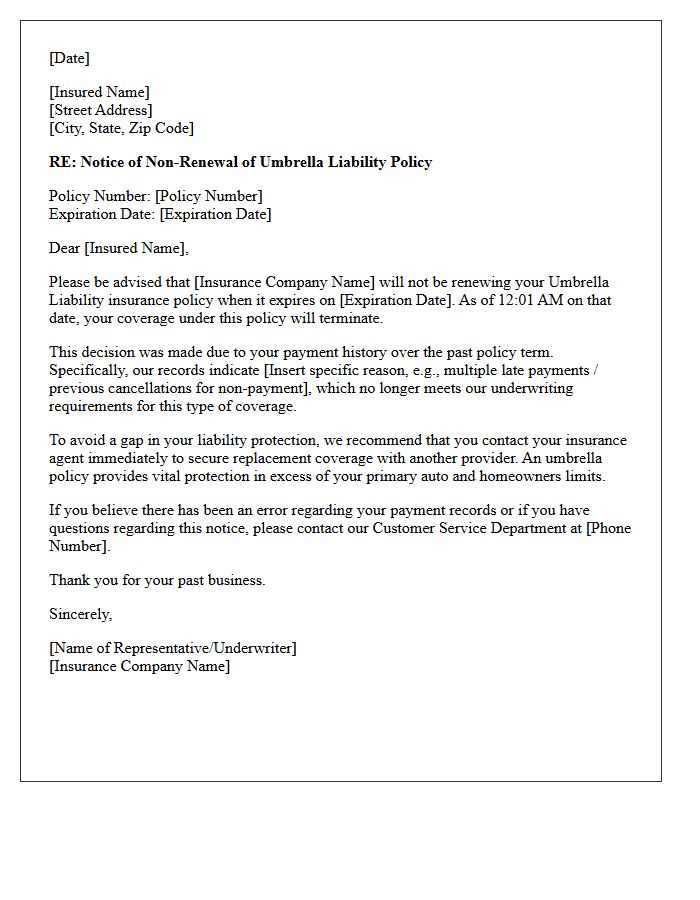
Receiving an umbrella policy non-renewal letter due to unfavorable payment history indicates the insurer is terminating coverage because of consistent late payments or missed premiums. This document serves as a formal notice that your liability protection will lapse on the expiration date. To maintain critical asset protection, you must immediately address any outstanding balances and seek alternative coverage. Frequent payment lapses signal high risk to underwriters, potentially making it difficult to secure standard rates elsewhere. Promptly contacting your agent to resolve billing disputes or improve your credit standing is essential.
Term Life Insurance Non-Renewal Letter for Consistent Late Payments
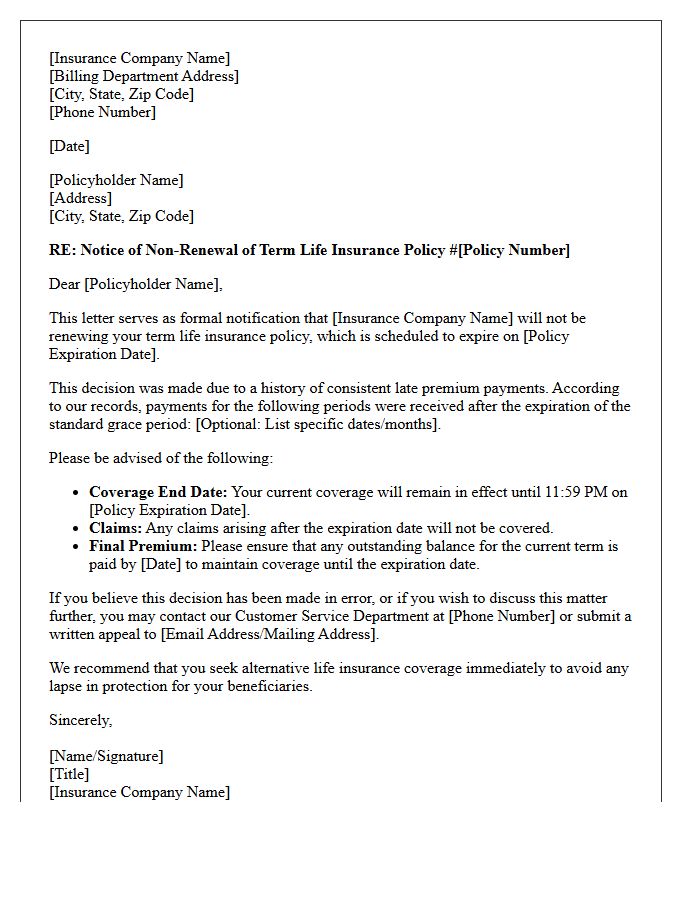
Receiving a term life insurance non-renewal letter signifies the insurer's decision to terminate coverage at the end of the current term. This action is frequently triggered by consistent late payments, which signal high risk to the provider. Unlike a grace period lapse, non-renewal prevents policy extension, leaving beneficiaries unprotected. It is crucial to address payment delinquency immediately, as a history of payment instability can make it difficult and more expensive to secure a new policy with different carriers in the future due to shared industry data.
Renters Insurance Policy Non-Renewal Letter for Premium Payment Issues
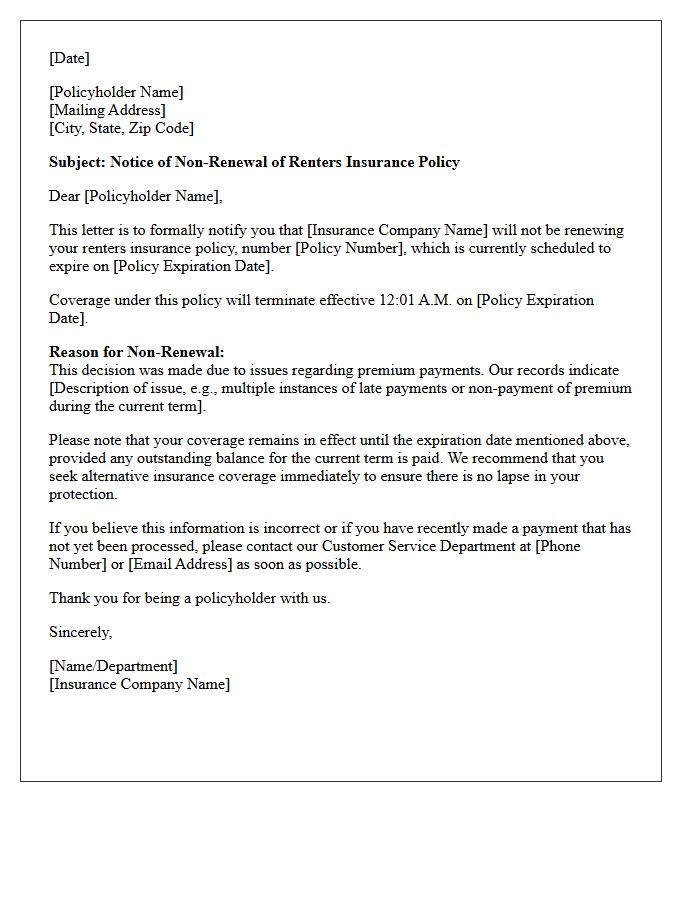
Receiving a non-renewal letter for premium payment issues means your insurance provider will not extend your coverage at the end of the current term. Frequent late payments or a history of policy lapses signal high risk to insurers. To protect your belongings and liability, immediately contact your agent to discuss potential reinstatement or seek a new provider. Maintaining continuous coverage is vital, as a coverage gap can lead to significantly higher rates in the future. Always prioritize timely payments to ensure your rental protection remains active and affordable.
Professional Liability Non-Renewal Letter Due to Chronic Late Payments
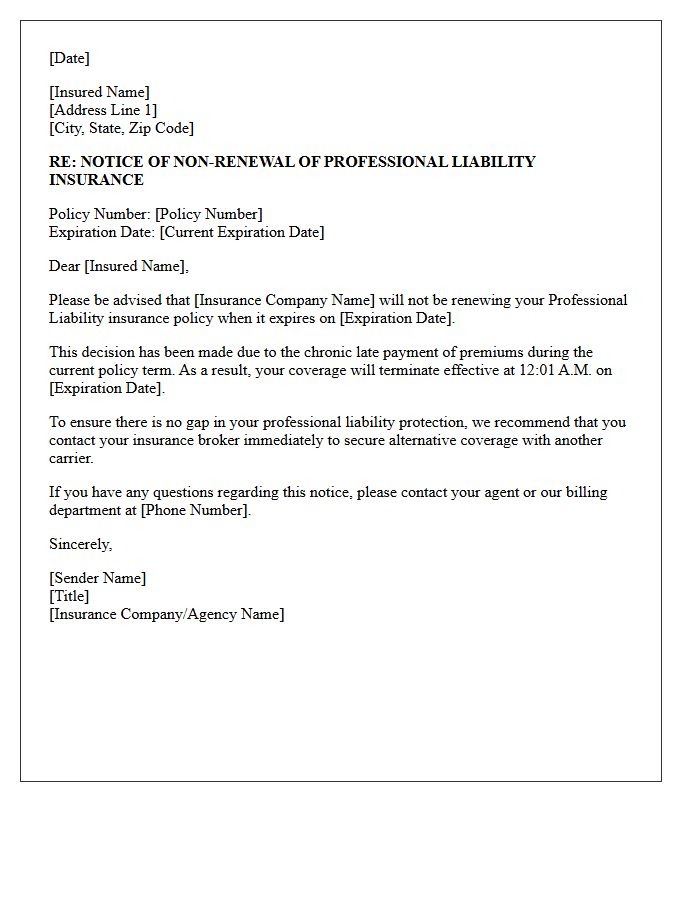
Receiving a professional liability non-renewal letter due to chronic late payments signifies that your insurer considers you a high-risk policyholder. To maintain continuous coverage and protect your professional reputation, you must act before the current policy expiration date. Insurance carriers view consistent payment delinquency as a lack of financial responsibility, often leading to automatic non-renewal. If this occurs, you may face higher premiums or difficulty securing a new policy through standard markets, as future applications will require you to disclose this prior coverage termination for payment history issues.
Cyber Liability Policy Non-Renewal Letter for Consistent Payment Delinquency
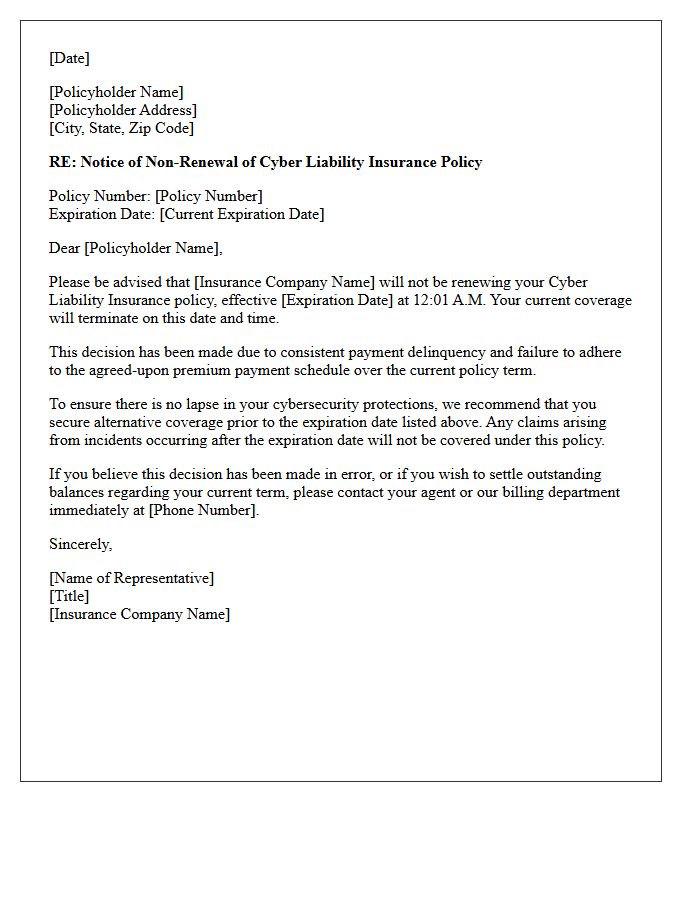
A Cyber Liability Policy Non-Renewal Letter is a formal notice issued by an insurer terminating coverage due to consistent payment delinquency. This document signifies that the policyholder has failed to meet premium obligations, resulting in a high-risk profile. Receiving this letter creates a critical coverage gap, leaving the business vulnerable to data breaches and digital extortion. To mitigate long-term damage, the insured must immediately address outstanding balances or seek alternative markets, though past payment issues may lead to significantly higher premiums or total denial of coverage elsewhere.
Errors and Omissions Policy Non-Renewal Letter for Delinquent Payments
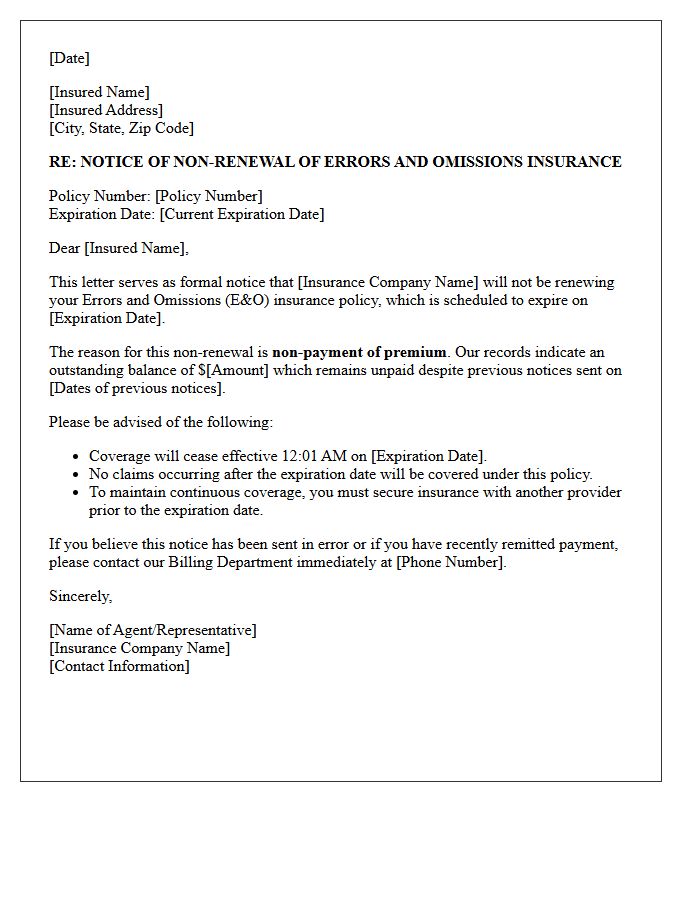
An Errors and Omissions (E&O) policy non-renewal letter due to delinquent payments is a formal notice that coverage will terminate. This occurs when an insured professional fails to pay premiums, leading the carrier to decline policy renewal. Receiving this letter is critical because it creates a coverage gap, leaving you unprotected against professional negligence claims. It is essential to act immediately by settling outstanding balances or securing a new policy to avoid uninsured liabilities and potential difficulty obtaining affordable future coverage due to your payment history.
What is a Notice of Non-Renewal due to chronic late payments?
A Notice of Non-Renewal is a formal legal document issued by a landlord notifying a tenant that their lease agreement will not be extended at the end of the current term specifically due to a consistent history of delinquent or late rent payments.
How much notice must a landlord provide for non-renewal based on payment history?
The required notice period typically ranges from 30 to 60 days before the lease expiration date, though this varies by state law and the specific terms outlined in your original rental agreement.
Can I stop the non-renewal by paying my past-due balance in full?
Unlike an eviction for non-payment, which can often be "cured" by paying the debt, a non-renewal is a decision not to enter into a new contract. A landlord is generally not legally obligated to renew a lease if the tenant has established a documented pattern of chronic late payments, even if the balance is currently zero.
Will a Notice of Non-Renewal for late payments affect my credit or rental history?
While the notice itself is not an eviction, a history of chronic late payments can be reported to credit bureaus or shared during future landlord reference checks, which may make it more difficult to secure a new rental property.
What are my options if I receive a non-renewal notice for late payments?
If you receive this notice, your primary options are to vacate the premises by the specified date to avoid formal eviction proceedings, or attempt to negotiate a new lease with the landlord by offering a higher security deposit or automated payment (ACH) setup, though they are not required to accept.
Comments