Insurance carriers may issue a Notice of Non-Renewal if policyholders fail to address safety concerns. This action typically follows a failure to comply with specific loss control recommendations designed to mitigate risk. Understanding these requirements is essential for maintaining continuous coverage and protecting your business assets. To assist you in your professional communication, below are some ready to use templates.
Image cover: Loss Control Compliance: Non-Renewal Notice Templates and Best Practices
Letter Samples List
- Commercial Property Non-Renewal Letter Due to Loss Control Non-Compliance
- Workers Compensation Policy Non-Renewal Letter for Ignored Safety Recommendations
- General Liability Non-Renewal Letter Regarding Failure to Mitigate Identified Risks
- Notice of Policy Non-Renewal Letter for Outstanding Loss Control Requirements
- Fleet Auto Insurance Non-Renewal Letter Following Unresolved Safety Inspections
- Business Owners Policy Non-Renewal Letter Due to Unfulfilled Risk Management Mandates
- Inland Marine Coverage Non-Renewal Letter for Ignored Security Recommendations
- Cyber Liability Non-Renewal Letter Due to Unpatched System Vulnerabilities
- Professional Liability Non-Renewal Letter Regarding Unimplemented Training Protocols
- Restaurant Insurance Non-Renewal Letter for Kitchen Exhaust System Violations
- Manufacturing Facility Non-Renewal Letter Regarding Incomplete Hazard Corrections
- Construction Builders Risk Non-Renewal Letter Due to Site Safety Non-Compliance
Commercial Property Non-Renewal Letter Due to Loss Control Non-Compliance
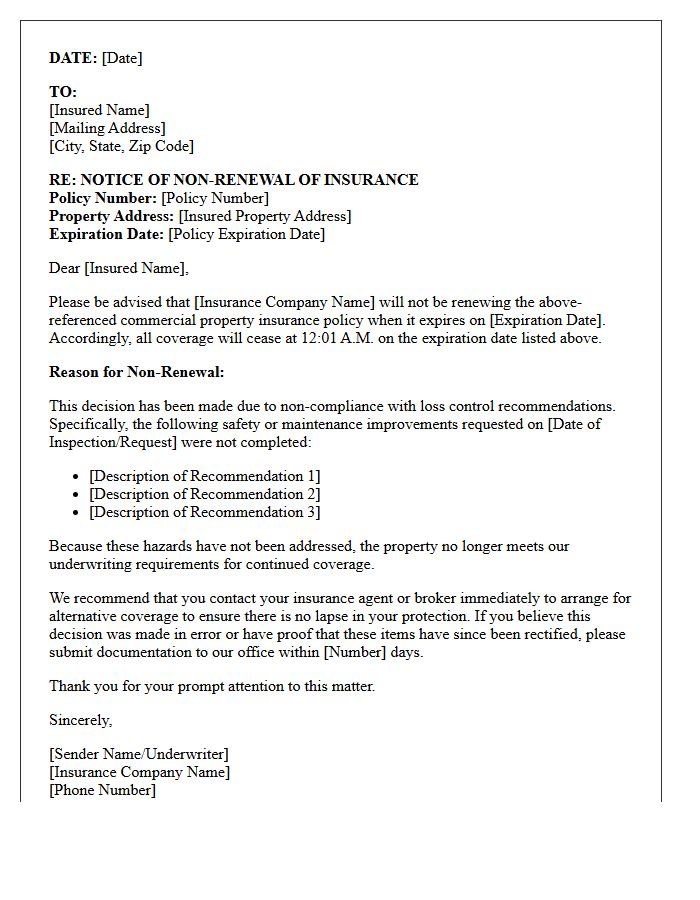
A Commercial Property Non-Renewal Letter is a formal notice terminating coverage because the insured failed to address safety hazards identified during an inspection. Policyholders must prioritize Loss Control Non-Compliance issues, such as faulty wiring or fire safety gaps, to maintain eligibility. When risk recommendations are ignored, insurers view the property as an unacceptable liability. Receiving this letter means you must quickly rectify outstanding safety requirements or face high-risk premiums and limited options in the surplus lines market. Timely remediation is the only way to restore insurability and protect your business assets.
Workers Compensation Policy Non-Renewal Letter for Ignored Safety Recommendations
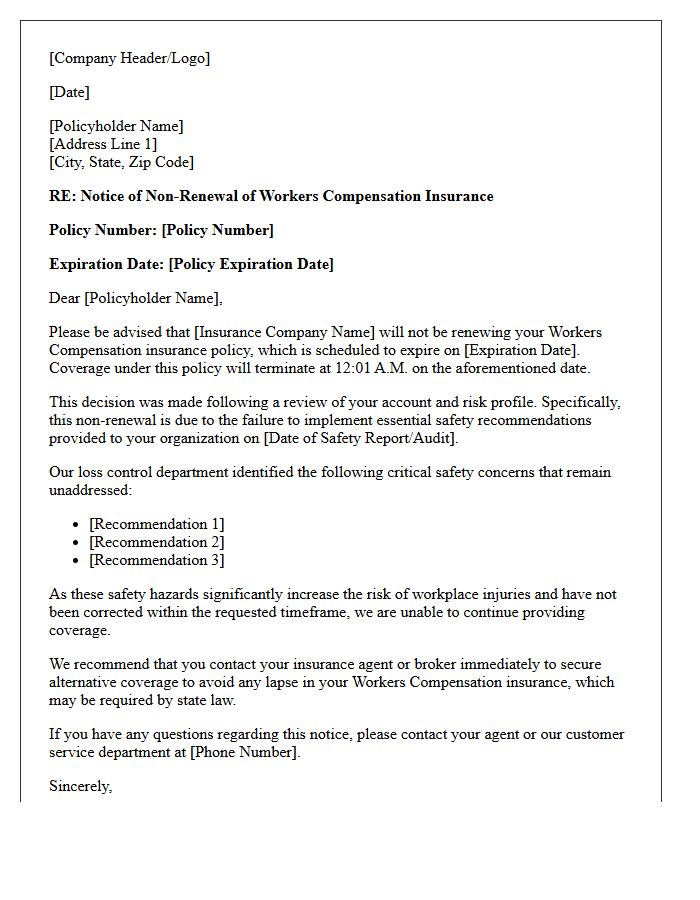
Receiving a workers compensation non-renewal letter signifies that an insurer is terminating coverage due to unresolved risks. When an employer consistently exhibits ignored safety recommendations, the insurance carrier views the business as a high-liability threat. Failing to implement mandated loss-control measures violates policy standards, leading to mandatory cancellation. To maintain coverage, businesses must provide immediate proof of compliance and safety improvements. Promptly addressing these hazards is essential to securing alternative insurance and avoiding lapses in coverage that result in legal penalties and significantly higher premiums in the high-risk market.
General Liability Non-Renewal Letter Regarding Failure to Mitigate Identified Risks
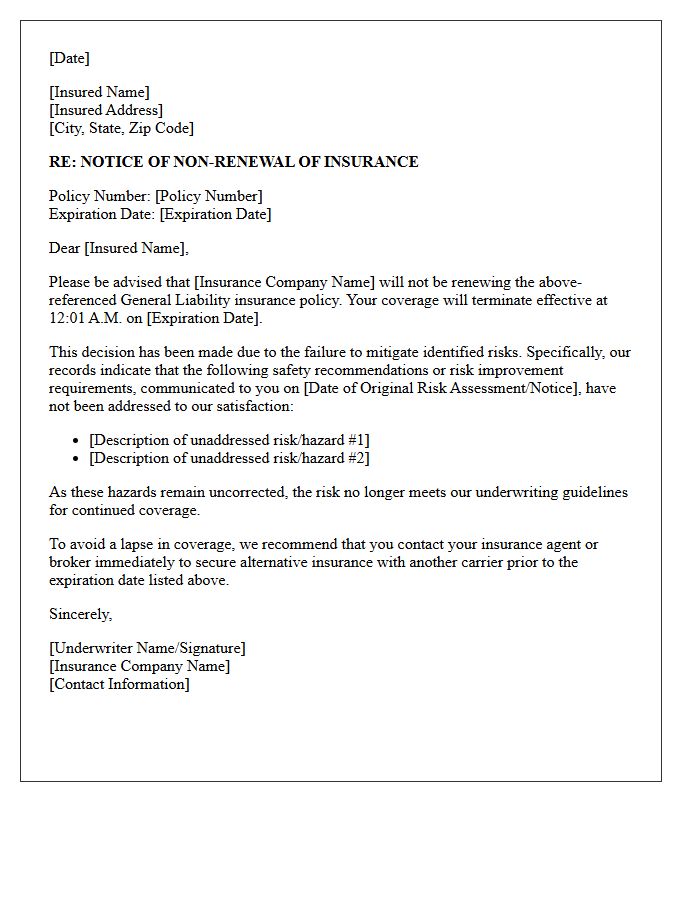
Receiving a General Liability Non-Renewal Letter indicates your insurance carrier will not extend coverage past the current term expiration. The primary cause cited is a failure to mitigate identified risks, meaning previous safety recommendations or hazard corrections were ignored. To protect your business, you must immediately address these outstanding safety issues and document all improvements. Promptly seeking alternative insurance markets is critical to avoid a lapse in protection, as carriers view unresolved risks as a high probability for future claims.
Notice of Policy Non-Renewal Letter for Outstanding Loss Control Requirements
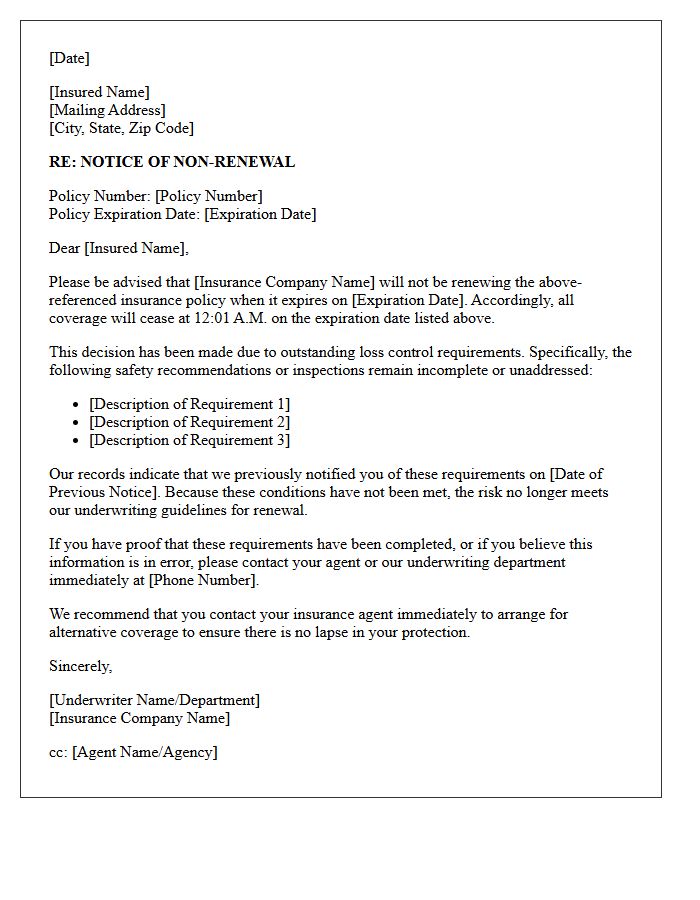
A Notice of Policy Non-Renewal regarding outstanding loss control requirements indicates that your insurer will terminate coverage at the policy's end. This typically occurs when a policyholder fails to implement mandatory safety improvements or risk mitigation measures identified during an inspection. To prevent a gap in protection, you must promptly address the specified compliance issues and provide proof of completion to your agent. Failure to resolve these hazards makes your property high-risk, complicating your ability to secure affordable insurance from other providers in the future.
Fleet Auto Insurance Non-Renewal Letter Following Unresolved Safety Inspections
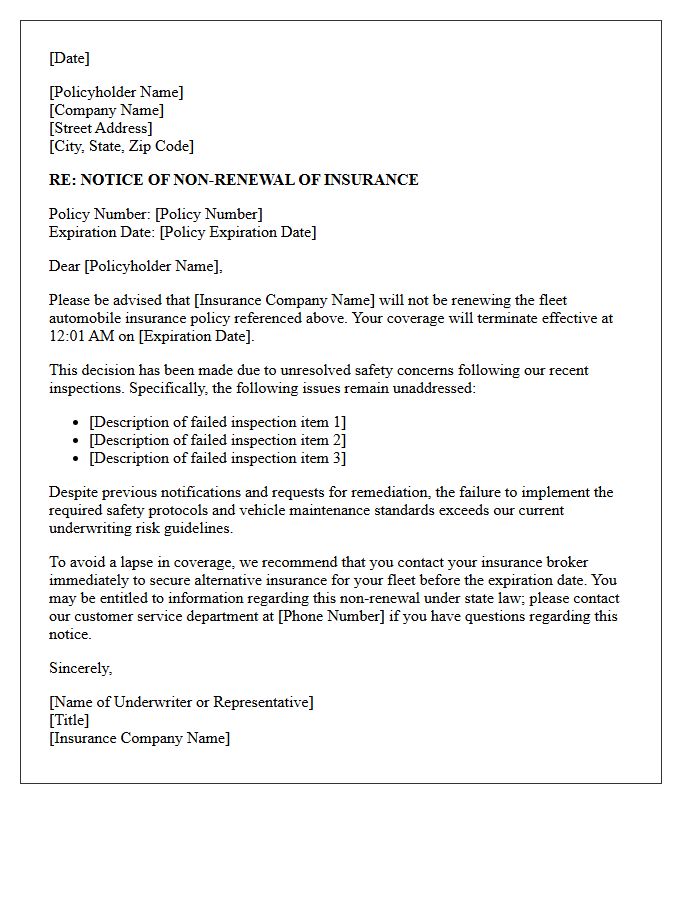
Receiving a Fleet Auto Insurance Non-Renewal Letter signifies that your provider will cease coverage upon the policy's expiration. This action typically follows unresolved safety inspections, where identified vehicle defects or compliance failures remain unaddressed. Insurers view outstanding maintenance issues as high-risk liabilities. To protect your business, you must prioritize corrective actions immediately and document all repairs. Failure to resolve these safety concerns can lead to a total loss of coverage, increased premiums with new carriers, and significant operational downtime for your entire commercial fleet.
Business Owners Policy Non-Renewal Letter Due to Unfulfilled Risk Management Mandates
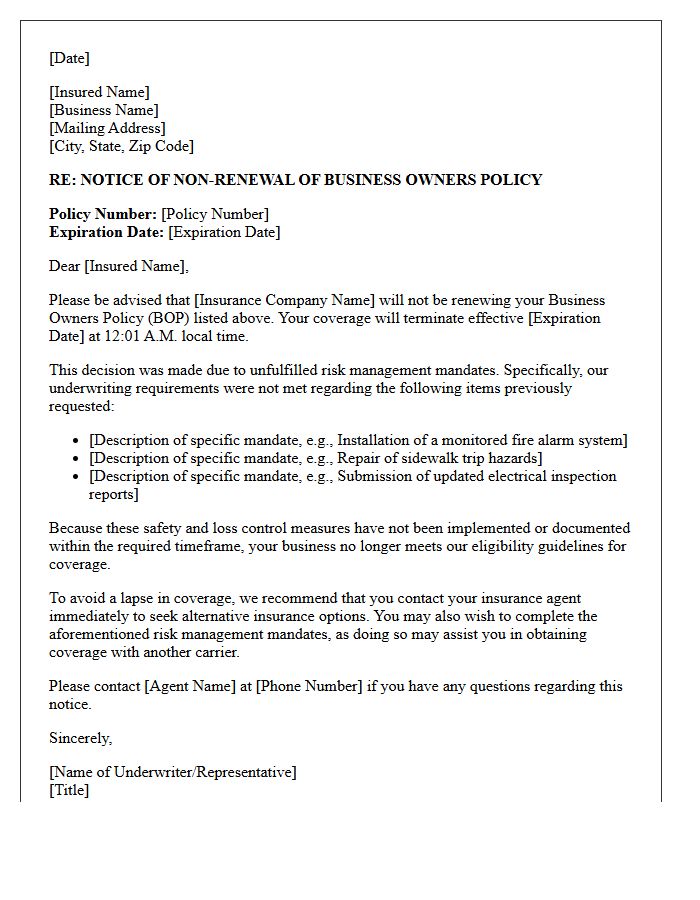
Receiving a Business Owners Policy (BOP) non-renewal letter often stems from unfulfilled risk management mandates. When an insurer identifies specific hazards, they issue mandatory safety improvements to mitigate potential claims. Failure to implement these required upgrades or provide proof of compliance leads to policy termination. To maintain coverage, owners must prioritize underwriting recommendations before the expiration date. Ignoring these directives signals high risk, making it difficult to secure affordable commercial insurance elsewhere. Promptly addressing security, fire safety, or structural concerns is essential for business continuity and long-term insurability.
Inland Marine Coverage Non-Renewal Letter for Ignored Security Recommendations
Receiving an inland marine non-renewal letter often stems from ignored security recommendations regarding high-value mobile equipment or cargo. When a business fails to implement mandated theft prevention or tracking upgrades, insurers view the risk as unmanageable. This formal notice signifies that coverage will terminate at the policy's expiration date. To prevent a permanent lapse, policyholders must immediately address the specified safety deficiencies or seek alternative high-risk insurance markets. Maintaining rigorous risk mitigation protocols is essential to ensuring continuous protection for equipment in transit or on remote worksites.
Cyber Liability Non-Renewal Letter Due to Unpatched System Vulnerabilities
Receiving a cyber liability non-renewal letter indicates that your insurer views your business as high-risk. This action is frequently triggered by unpatched system vulnerabilities discovered during security scans. Insurance carriers now mandate strict adherence to patch management protocols to mitigate data breaches. To regain coverage, you must demonstrate a proactive remediation strategy and provide proof that critical security updates are installed. Failure to address these gaps results in a lapse in coverage, leaving your organization financially exposed to cyberattacks, regulatory fines, and legal liabilities following a security incident.
Professional Liability Non-Renewal Letter Regarding Unimplemented Training Protocols
Receiving a professional liability non-renewal letter due to unimplemented training protocols indicates a critical breakdown in risk management. Insurers view the failure to adopt mandated safety or compliance education as an unacceptable increase in underwriting risk. To protect your practice, you must immediately address these deficiencies and provide documented proof of completion. Failure to rectify these gaps can lead to a total loss of coverage, higher premiums, or legal exposure. Consulting with a broker is essential to demonstrate future compliance and secure alternative indemnity options before your current policy expires.
Restaurant Insurance Non-Renewal Letter for Kitchen Exhaust System Violations
Receiving a non-renewal letter due to kitchen exhaust violations is a critical risk to your business operations. Insurers issue these notices when grease accumulation or improper duct maintenance creates an unacceptable fire hazard. To prevent a lapse in coverage, you must immediately perform a certified professional cleaning and provide compliance documentation to your agent. Failure to rectify these safety violations can lead to policy cancellation, significantly higher premiums, or the inability to secure new property insurance in a high-risk market. Prioritizing fire suppression standards is essential for long-term risk management.
Manufacturing Facility Non-Renewal Letter Regarding Incomplete Hazard Corrections
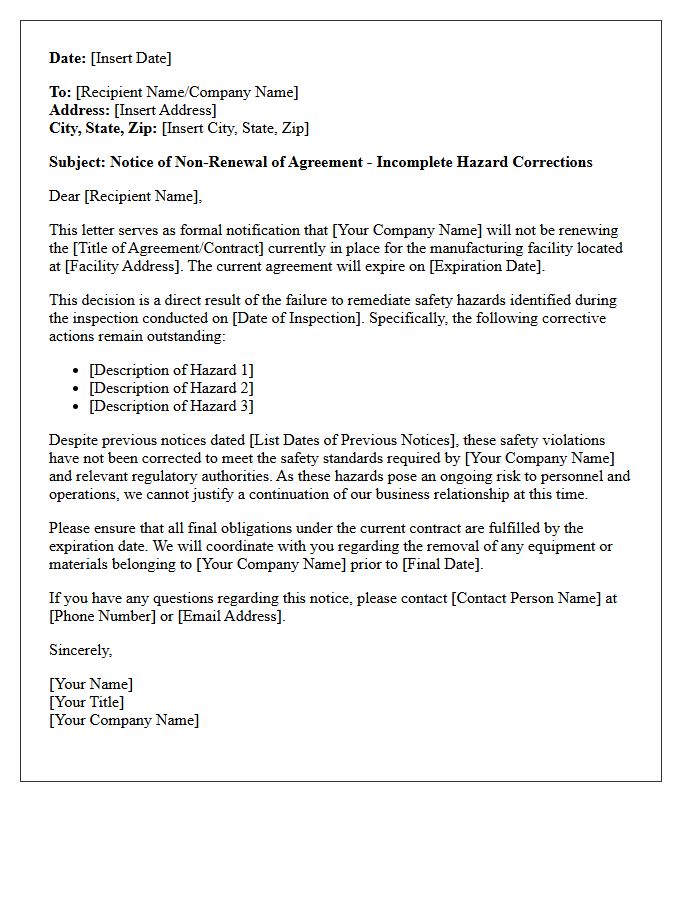
A manufacturing facility non-renewal letter signifies the termination of a contract or insurance policy due to incomplete hazard corrections. This formal notice alerts management that identified safety risks or compliance violations remain unresolved after prior inspections. Failure to mitigate these physical or operational threats results in a loss of coverage or leasing rights. To prevent business disruption, facilities must prioritize immediate remediation and provide documented proof of safety improvements to satisfy regulatory or underwriting requirements before the specified termination date occurs.
Construction Builders Risk Non-Renewal Letter Due to Site Safety Non-Compliance
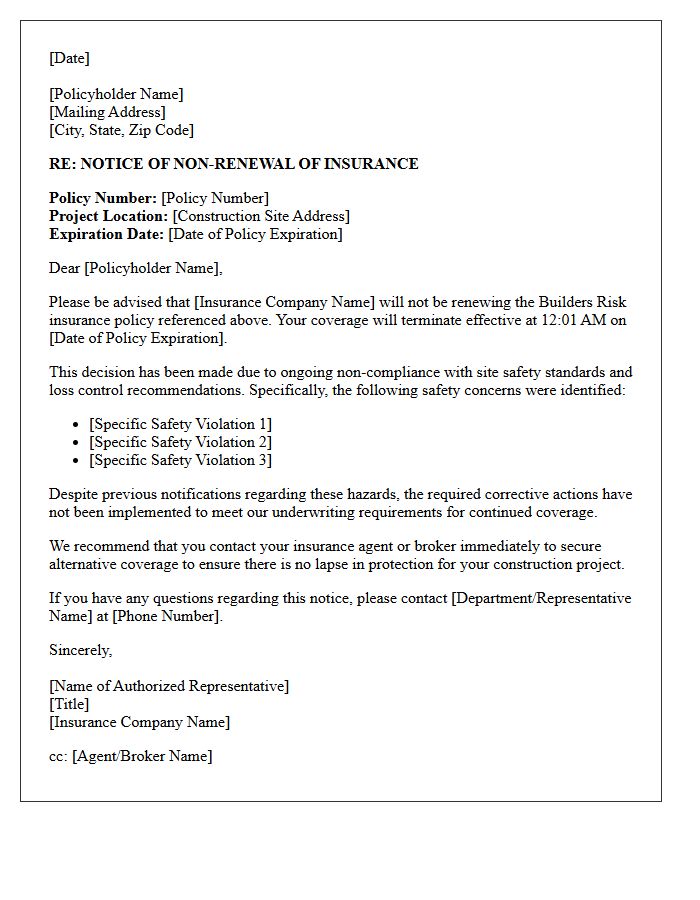
A Construction Builders Risk Non-Renewal Letter is a formal notice from an insurer terminating coverage due to persistent site safety non-compliance. This occurs when contractors fail to rectify identified hazards, such as poor debris management, inadequate fencing, or fire safety violations. Receiving this letter is critical because it creates a coverage gap, stalling project financing and increasing liability. To prevent non-renewal, project managers must prioritize risk mitigation and document all safety improvements immediately. Failure to address these concerns makes securing alternative insurance significantly more expensive or impossible for high-risk projects.
What is a Notice of Non-Renewal due to failure to comply with loss control recommendations?
A Notice of Non-Renewal is a formal document issued by an insurance carrier stating they will not extend coverage beyond the current policy expiration date because the policyholder failed to implement required safety or security improvements identified during a risk assessment.
Can I prevent a non-renewal if I complete the loss control recommendations now?
In many cases, if you complete the required safety improvements and provide proof of compliance before the effective date of the non-renewal, the insurance company may agree to rescind the notice and offer a renewal quote. However, this is at the discretion of the underwriter and should be addressed immediately.
How much time do I have to respond to a loss control non-renewal notice?
State laws typically require insurers to provide 30 to 60 days' notice before a policy expires. You should act as soon as you receive the notice to either complete the repairs, provide documentation of completion, or begin shopping for a new insurance provider to avoid a lapse in coverage.
Will a non-renewal for loss control issues make it harder to find new insurance?
Yes, a history of non-compliance with loss control recommendations can make you appear as a higher risk to other carriers. New insurers will often ask if you have had a policy non-renewed and may request proof that the previous safety issues have been corrected before offering a new policy.
What are common examples of loss control recommendations that lead to non-renewal?
Common recommendations include repairing damaged roofing, upgrading outdated electrical systems (such as aluminum wiring), installing fire suppression systems, fixing sidewalk trip hazards, or implementing formal safety training programs for employees.
Comments