Facing a Notice of Non-Renewal can be stressful, especially when triggered by a significant increase in hazard risk. This typically occurs when insurers determine your property's exposure to environmental threats or physical hazards has exceeded their underwriting guidelines. Understanding your rights and options is essential for maintaining continuous coverage. To help you communicate effectively with your provider, below are some ready to use templates.
Image cover: Important Notice Regarding Policy Non-Renewal Due to Increased Hazard Risk: Templates and Guidance
Letter Samples List
- Notice of Non-Renewal Letter Due to Significant Hazard Risk Increase
- Insurance Policy Non-Renewal Letter for Elevated Property Hazard
- Hazard Risk Escalation Non-Renewal Notification Letter
- Commercial Property Increased Hazard Non-Renewal Letter
- Letter of Non-Renewal Following Significant Hazard Risk Assessment
- Official Non-Renewal Letter Due to Unmitigated Hazard Risks
- Insurance Agency Letter for Policy Non-Renewal Based on Hazard Exposure
- Significant Hazard Risk Increase Policy Termination Letter
- Formal Letter of Non-Renewal for Escalated Environmental Hazards
- Policyholder Non-Renewal Letter Regarding Elevated Risk Profile
- Substantial Hazard Increase Coverage Non-Renewal Letter
- Insurance Coverage Expiration and Hazard Risk Non-Renewal Letter
Notice of Non-Renewal Letter Due to Significant Hazard Risk Increase
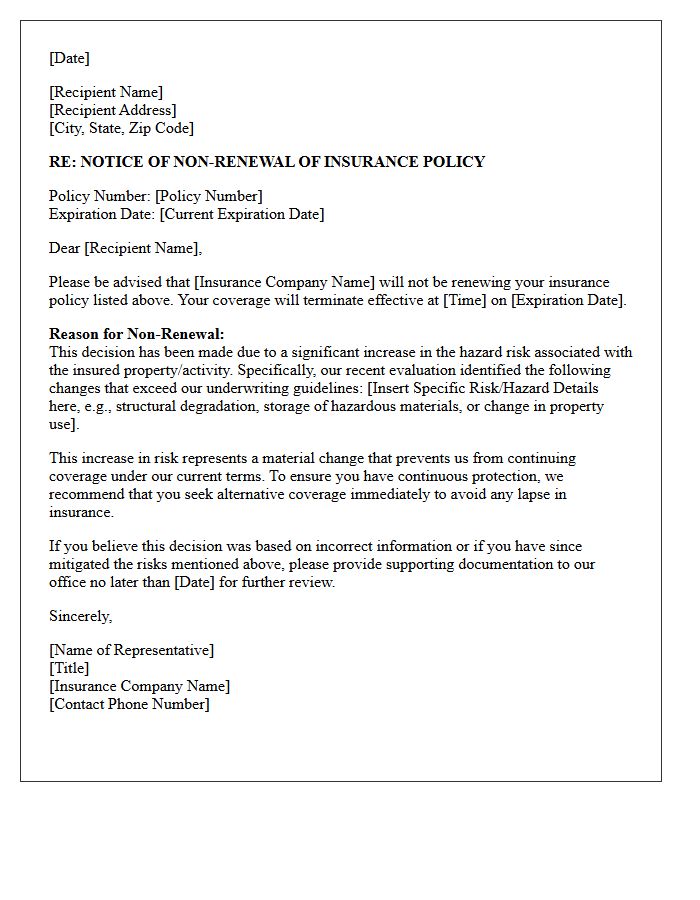
A Notice of Non-Renewal due to significant hazard risk increase means your insurer will not extend coverage past the current expiration date. This occurs when a property inspection or environmental data reveals new dangers, such as structural decay, outdated electrical systems, or heightened wildfire threats. To protect your investment, immediately address the identified hazards or shop for a new policy. Failure to secure replacement coverage can lead to a lender-placed policy or a total loss of financial protection against unforeseen disasters and liability claims.
Insurance Policy Non-Renewal Letter for Elevated Property Hazard
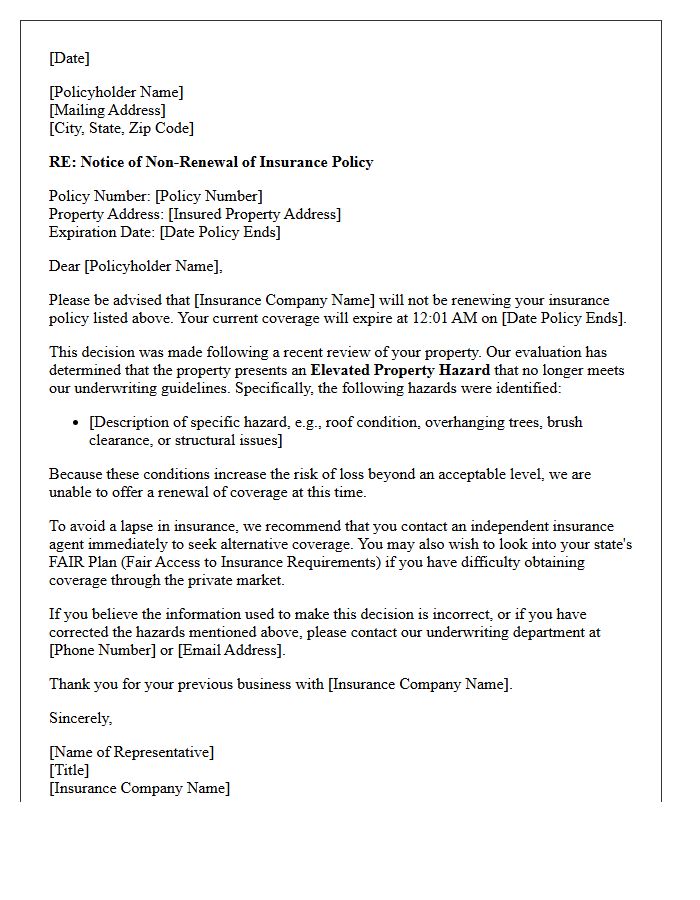
An insurance policy non-renewal letter due to an elevated property hazard signifies that your insurer will not extend coverage after the current term. This decision usually stems from unresolved safety risks, such as a failing roof, outdated wiring, or accumulation of debris. Upon receiving this notice, it is critical to address the specific maintenance issues identified to secure new reinsurance. You should immediately seek alternative quotes or a surplus lines carrier to ensure continuous protection, as a gap in coverage can lead to significantly higher premiums and future eligibility challenges.
Hazard Risk Escalation Non-Renewal Notification Letter
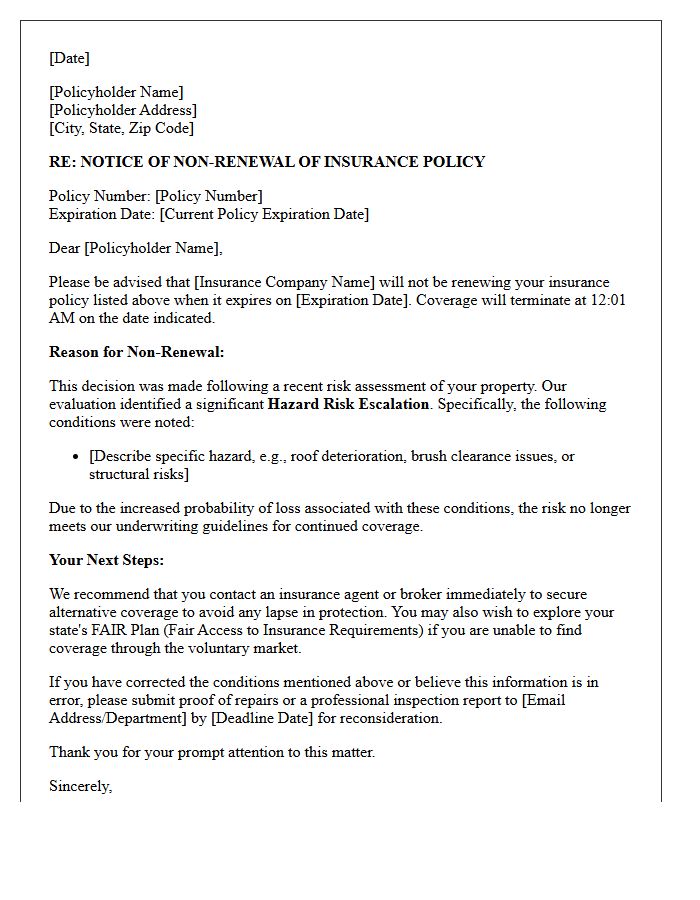
A Hazard Risk Escalation Non-Renewal Notification Letter informs policyholders that their insurance coverage will not be extended due to increased environmental or structural threats. This formal notice indicates that the property no longer meets underwriting standards because of rising hazards like wildfires, floods, or severe weather patterns. It is crucial to review the specific reasons provided and the effective termination date. Recipients must immediately seek alternative coverage to avoid a protection gap, as this mandatory legal notice serves as a final warning that the current insurer will no longer assume the risk.
Commercial Property Increased Hazard Non-Renewal Letter
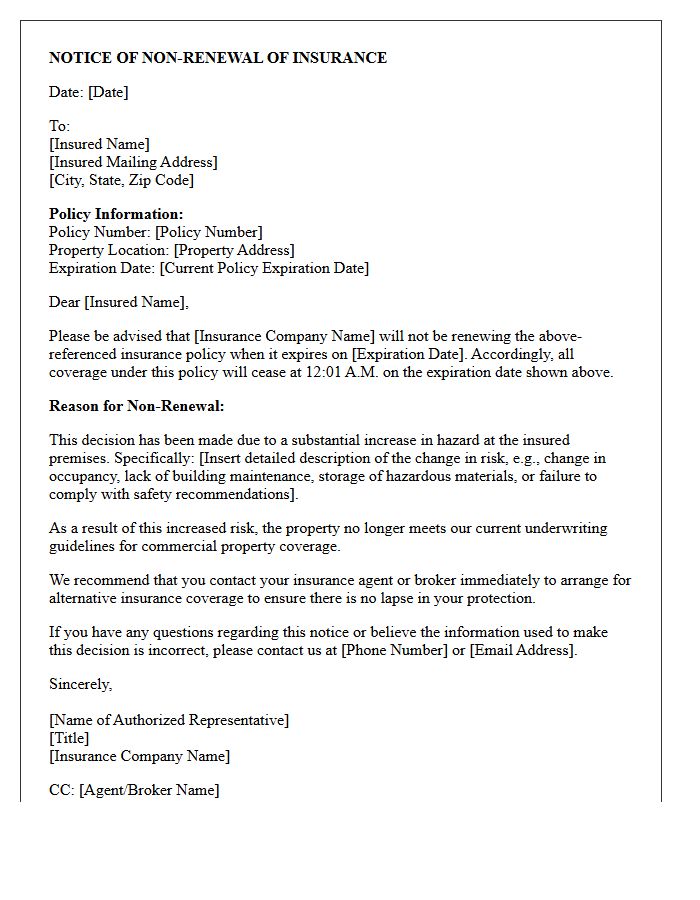
A Commercial Property Increased Hazard Non-Renewal Letter is a formal legal notice stating that an insurer will not extend coverage due to heightened risk. This typically occurs when a material change in operations or property condition significantly increases the likelihood of a claim. Policyholders must act quickly to find alternative coverage, as this notice indicates the current provider deems the risk uninsurable under existing terms. Reviewing the specific reasons cited is essential for addressing safety concerns or securing a new policy through surplus lines or specialized markets.
Letter of Non-Renewal Following Significant Hazard Risk Assessment
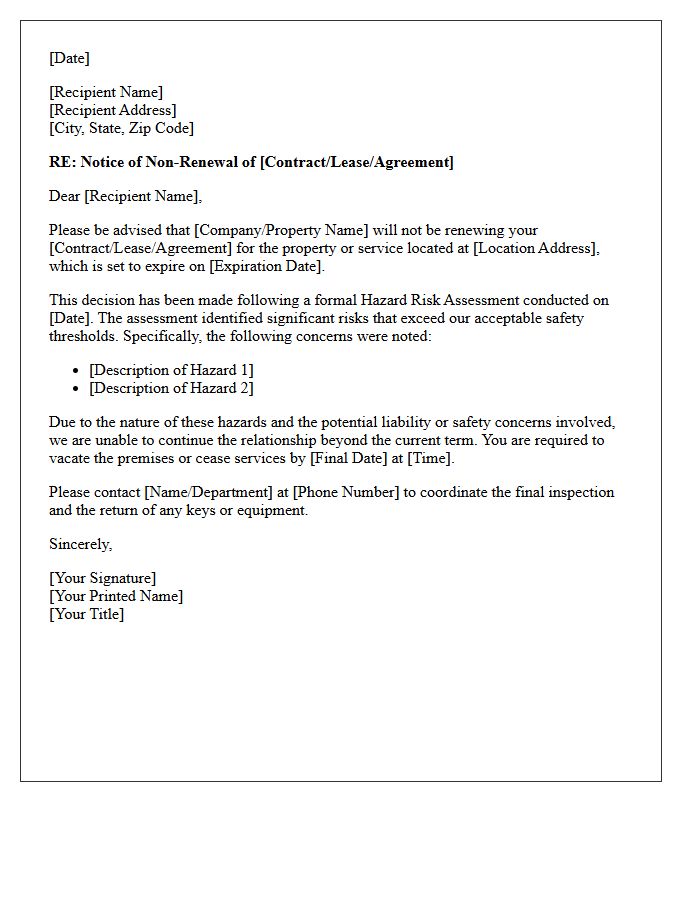
A Letter of Non-Renewal issued after a significant hazard risk assessment indicates that an insurer will not extend your coverage due to identified safety concerns. This formal notice typically outlines specific physical conditions or operational hazards that exceed the company's risk appetite. Property owners must address these vulnerabilities immediately, as a non-renewal can lead to higher premiums or difficulty securing alternative protection. It is essential to review the findings and implement required safety improvements or seek a surplus lines provider to maintain continuous insurance compliance.
Official Non-Renewal Letter Due to Unmitigated Hazard Risks
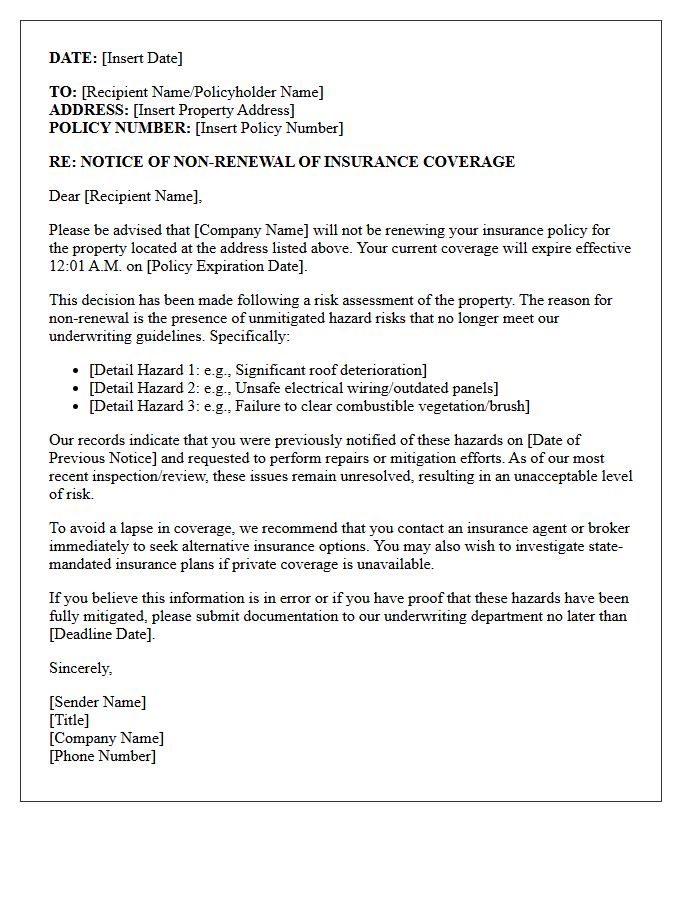
An official non-renewal letter notifies policyholders that their coverage will terminate due to unmitigated hazard risks. Insurance companies issue these notices when specific property hazards, such as old roofs or brush accumulation, remain unaddressed after inspection. To prevent a lapse in coverage, homeowners must complete required repairs or mitigate safety concerns before the expiration date. Maintaining your property is essential to ensuring insurance eligibility and avoiding high-risk market premiums. Always review the letter's specific compliance deadlines to protect your financial interests and maintain continuous protection.
Insurance Agency Letter for Policy Non-Renewal Based on Hazard Exposure
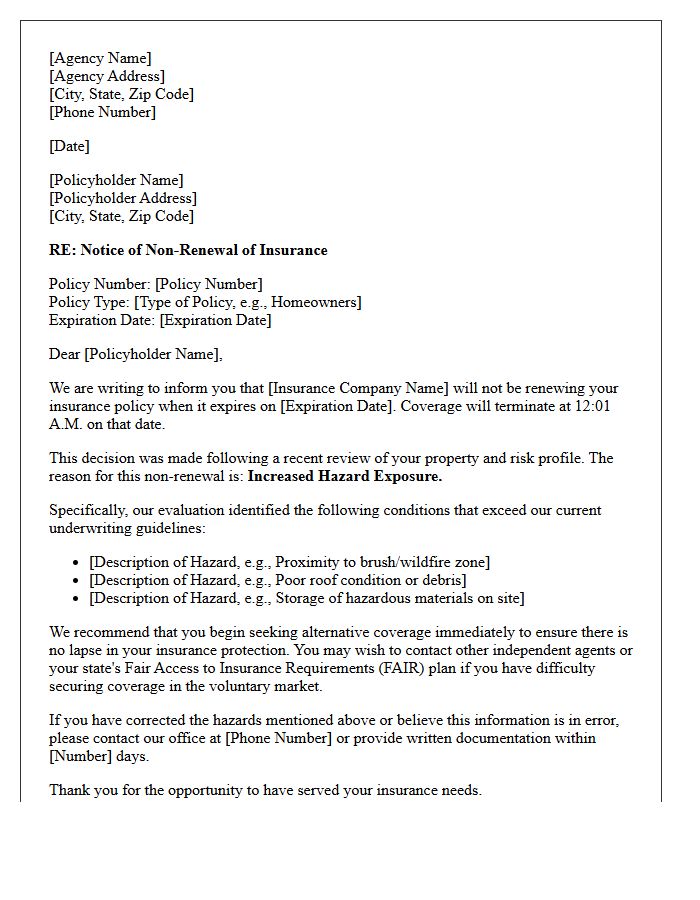
A non-renewal letter due to hazard exposure notifies policyholders that an insurer will not extend coverage because of unmitigated risks. These letters are often triggered by high-risk property conditions, such as roof damage, brush accumulation, or debris. To maintain protection, owners must address the specified safety concerns or seek alternative carriers before the expiration date. It is essential to review the notice for state-mandated appeal rights and deadlines to ensure continuous liability and asset protection through a new insurance policy.
Significant Hazard Risk Increase Policy Termination Letter
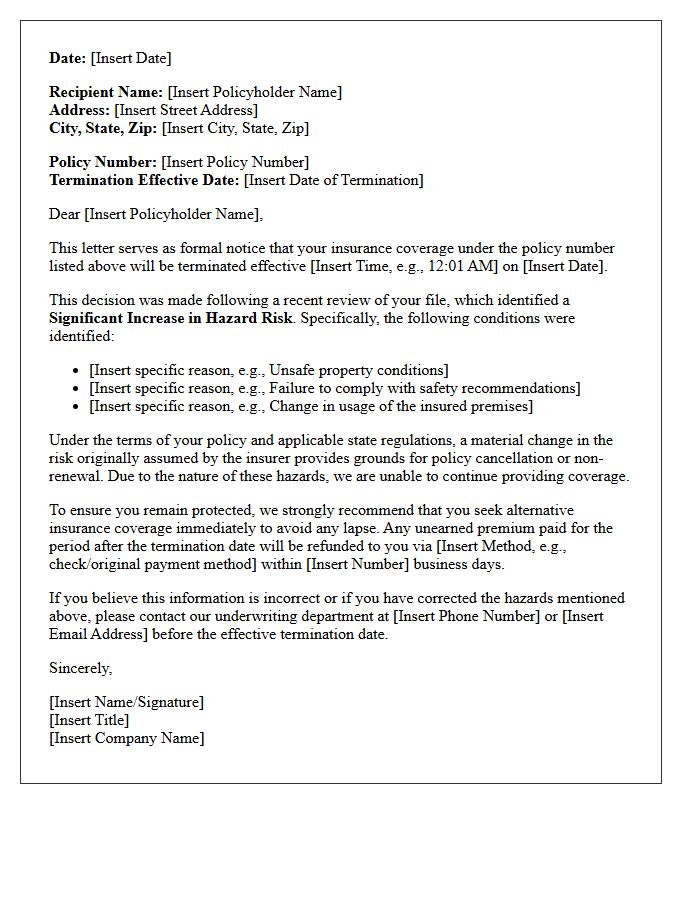
A Significant Hazard Risk Increase Policy Termination Letter is a formal notice from an insurer stating they are canceling your coverage due to newly discovered dangers. This occurs when property conditions change or undisclosed activities significantly elevate the chance of a claim. The underwriting department issues this because the risk no longer meets their safety guidelines. Upon receipt, you must act quickly to rectify the hazards or find alternative insurance to avoid a coverage lapse, which can lead to legal issues and higher future premiums.
Formal Letter of Non-Renewal for Escalated Environmental Hazards
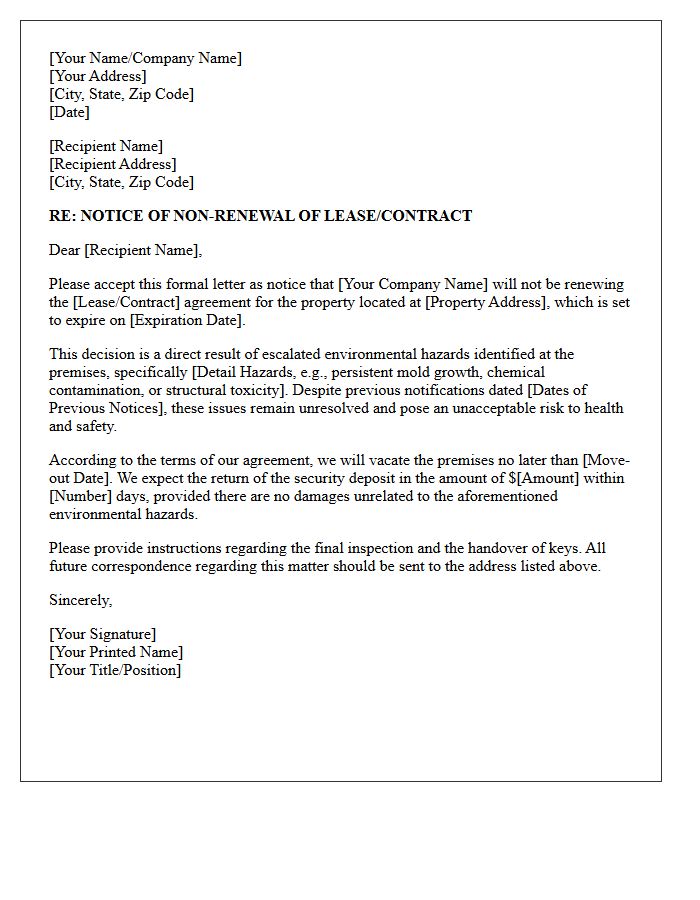
A formal letter of non-renewal due to escalated environmental hazards serves as a critical legal notice to terminate a lease or contract. This document must clearly cite unremedied safety violations, such as toxic mold, chemical leaks, or structural instability, which pose immediate risks. Highlighting these documented risks protects the sender from liability while ensuring compliance with health regulations. It is essential to include specific inspection dates and the final move-out deadline. This formal communication ensures a legally binding exit, prioritizing human safety over continued tenancy when hazardous conditions persist without resolution.
Policyholder Non-Renewal Letter Regarding Elevated Risk Profile
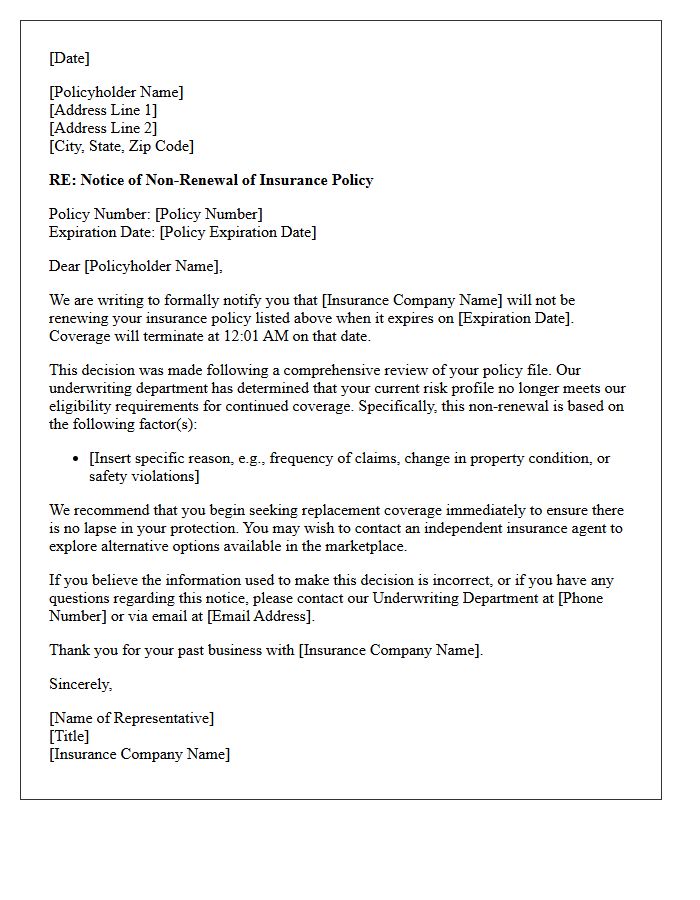
A policyholder non-renewal letter regarding an elevated risk profile notifies a client that their insurance coverage will not be extended past the current term. This typically occurs when a carrier determines that loss potential has exceeded acceptable underwriting thresholds. Key reasons include frequent claims, significant property hazards, or changes in safety scores. To maintain protection, recipients should immediately review the notice period and seek alternative coverage. Understanding specific risk factors mentioned can help policyholders implement safety improvements to secure reinsurance or new policies with different providers.
Substantial Hazard Increase Coverage Non-Renewal Letter
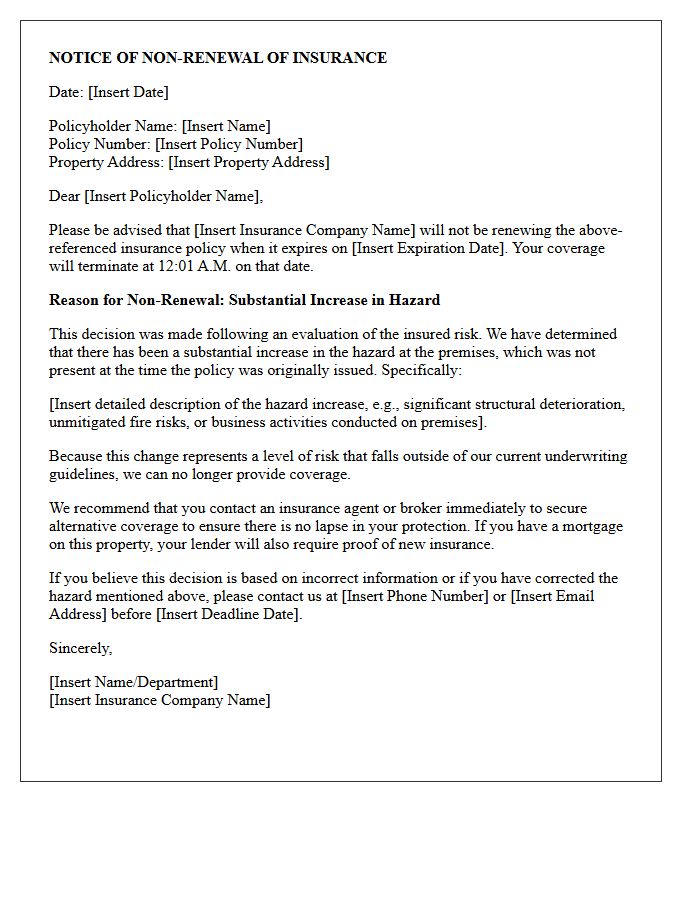
Receiving a Substantial Hazard Increase non-renewal letter means your insurer has identified a material change in risk that exceeds their underwriting guidelines. This notice officially terminates your policy at the end of the current term because the property or operations have become too risky to cover. Common triggers include physical property deterioration, unaddressed safety hazards, or unauthorized structural alterations. To maintain protection, you must immediately address the identified safety issues or secure alternative coverage through a specialized surplus lines broker before the expiration date to avoid a costly lapse.
Insurance Coverage Expiration and Hazard Risk Non-Renewal Letter
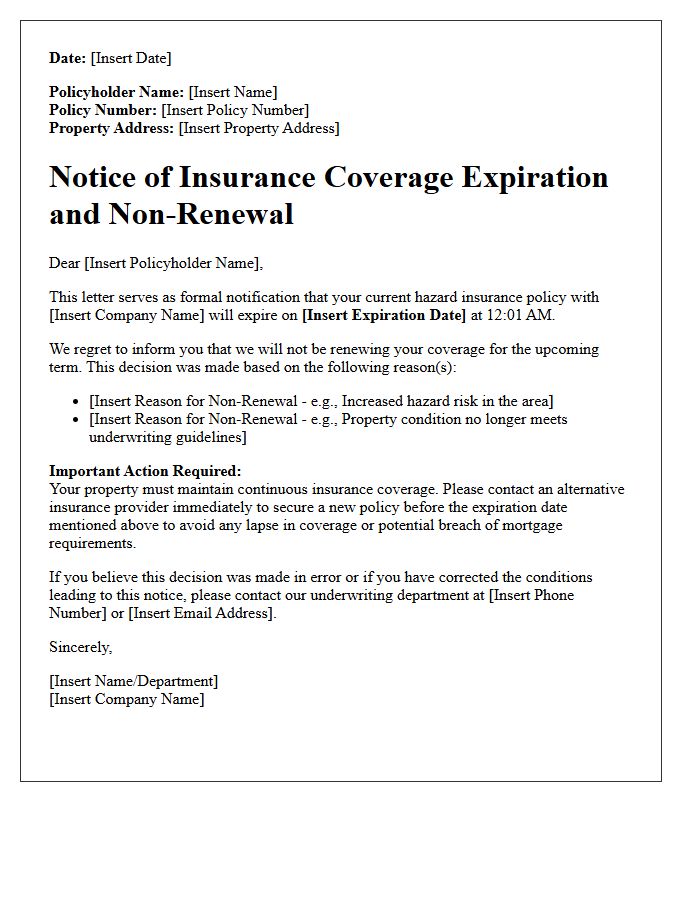
An insurance expiration notice or hazard risk non-renewal letter signifies that your current policy will terminate on a specific date. This creates a critical coverage gap, leaving your property vulnerable to financial loss from fire, storms, or theft. For homeowners with a mortgage, failing to secure a new policy may trigger force-placed insurance, which is significantly more expensive and offers limited protection. It is essential to immediately review the stated reason for non-renewal and shop for a replacement policy to maintain continuous protection and meet all legal or lender requirements.
What is a Notice of Non-Renewal Due to Significant Increase in Hazard Risk?
This is a formal notification from an insurance provider stating that they will not renew a policy at the end of its current term because the property's exposure to potential perils-such as wildfire, flooding, or structural instability-has exceeded the company's risk tolerance.
Why did my insurance company decide not to renew my policy now?
Non-renewals often occur after a reassessment of local geographic data, updated climate modeling, or a physical inspection reveals that the property is at a higher risk for loss than when the policy was originally issued. This change in risk profile makes the property ineligible for the provider's current underwriting guidelines.
Can I appeal a non-renewal based on increased hazard risk?
Yes, you can request a review if you have performed significant mitigation efforts, such as installing a fire-resistant roof, clearing defensible space, or upgrading drainage systems. Providing documentation and receipts of these improvements may encourage the insurer to reconsider the risk assessment.
How much time do I have to find new coverage after receiving this notice?
State laws typically require insurance companies to provide between 30 and 60 days of notice prior to the policy expiration date. It is critical to begin shopping for a replacement policy immediately, as finding coverage in high-hazard zones can be more time-consuming.
What are my options if I cannot find a standard insurer to cover my property?
If private insurers decline coverage due to hazard risk, you may need to look into "surplus lines" carriers or your state's FAIR Plan (Fair Access to Insurance Requirements). These plans are designed as a last resort for properties that are considered uninsurable in the voluntary market.
Comments