Issuing a Notice of Non-Renewal Due to Unacceptable Liability Risk is a critical step for insurers when policyholders exceed established safety or financial benchmarks. This formal communication explains the specific risk factors leading to the termination of coverage. Understanding these legal requirements ensures compliance and professional clarity. To help you draft this document effectively, below are some ready to use template options.
Image cover: Professional Templates for Non-Renewal Notices Based on Unacceptable Liability Risk
Letter Samples List
- Commercial Property Unacceptable Liability Risk Non-Renewal Letter
- General Contractor Unacceptable Liability Risk Non-Renewal Letter
- Excessive Claims History Unacceptable Liability Risk Non-Renewal Letter
- Personal Auto High Liability Risk Non-Renewal Letter
- Homeowners Unmitigated Liability Risk Non-Renewal Letter
- Commercial Auto Unacceptable Liability Risk Non-Renewal Letter
- Cyber Security Unacceptable Liability Risk Non-Renewal Letter
- Professional Liability Unacceptable Risk Non-Renewal Letter
- Workers Compensation Unacceptable Liability Risk Non-Renewal Letter
- Liquor Liability Unacceptable Risk Non-Renewal Letter
- Landlord Property Unacceptable Liability Risk Non-Renewal Letter
- Manufacturing Facility Unacceptable Liability Risk Non-Renewal Letter
Commercial Property Unacceptable Liability Risk Non-Renewal Letter
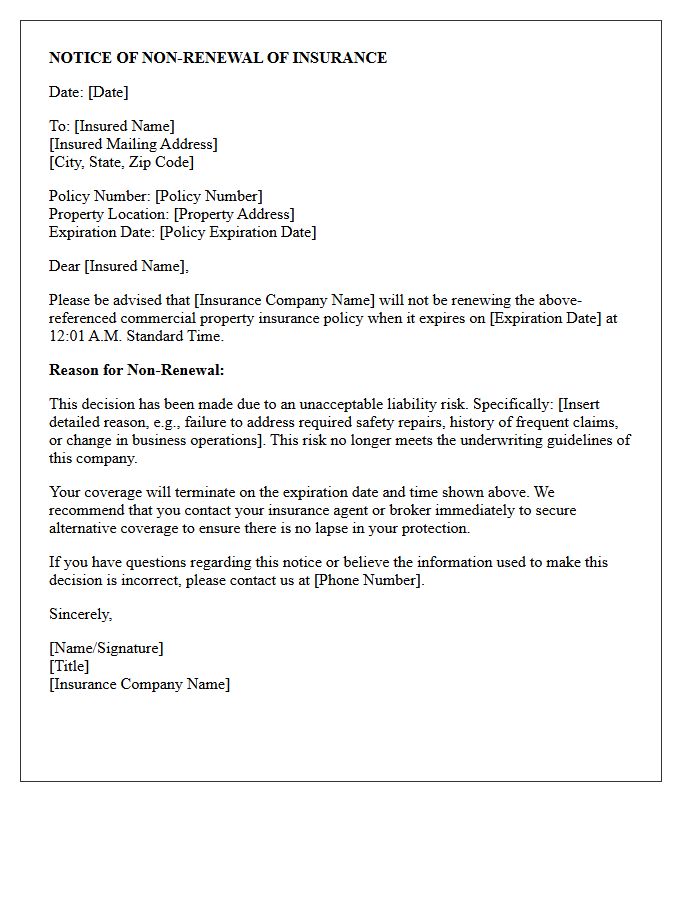
A Commercial Property Unacceptable Liability Risk Non-Renewal Letter is a formal notification that an insurer will terminate coverage upon policy expiration. This typically occurs when a risk assessment identifies hazards-such as poor maintenance, high claims frequency, or unsafe operations-that exceed underwriting guidelines. Receiving this letter means the property is deemed an unacceptable liability. To maintain protection, owners must immediately address identified safety issues or seek alternative coverage through surplus lines brokers, as a non-renewal notice can make securing standard insurance more challenging and expensive in the future.
General Contractor Unacceptable Liability Risk Non-Renewal Letter
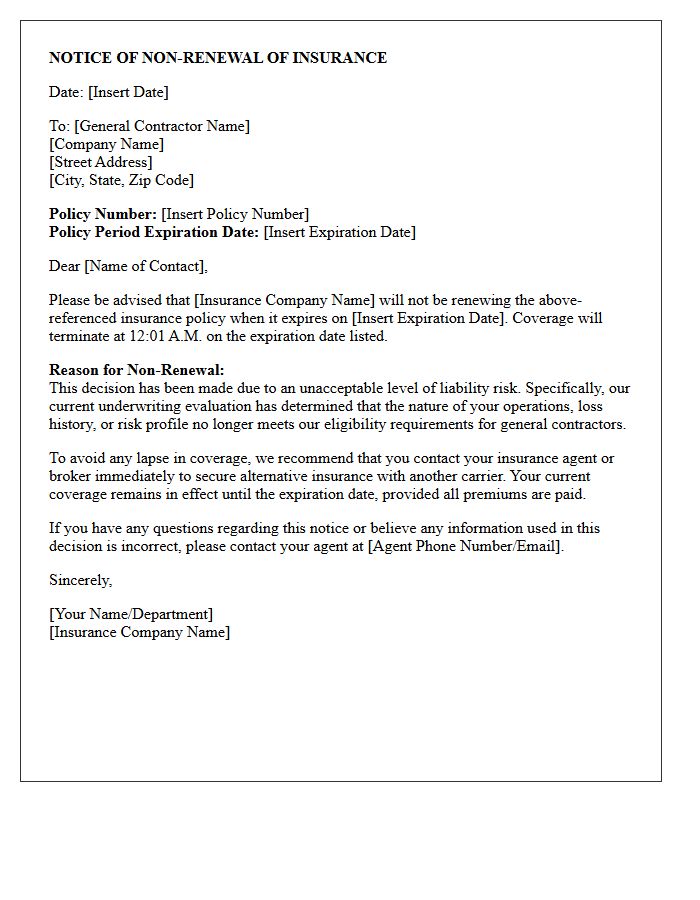
A General Contractor Unacceptable Liability Risk Non-Renewal Letter is a formal notice from an insurer terminating coverage due to high-risk exposure. This typically occurs when a contractor fails to meet safety standards, experiences frequent claims, or engages in excluded operations like multi-family habitational work. Receiving this letter indicates that your current carrier deems your business uninsurable under their guidelines. It is critical to address these underwriting concerns immediately and seek alternative specialty markets to avoid a lapse in coverage that could halt your projects and breach contracts.
Excessive Claims History Unacceptable Liability Risk Non-Renewal Letter
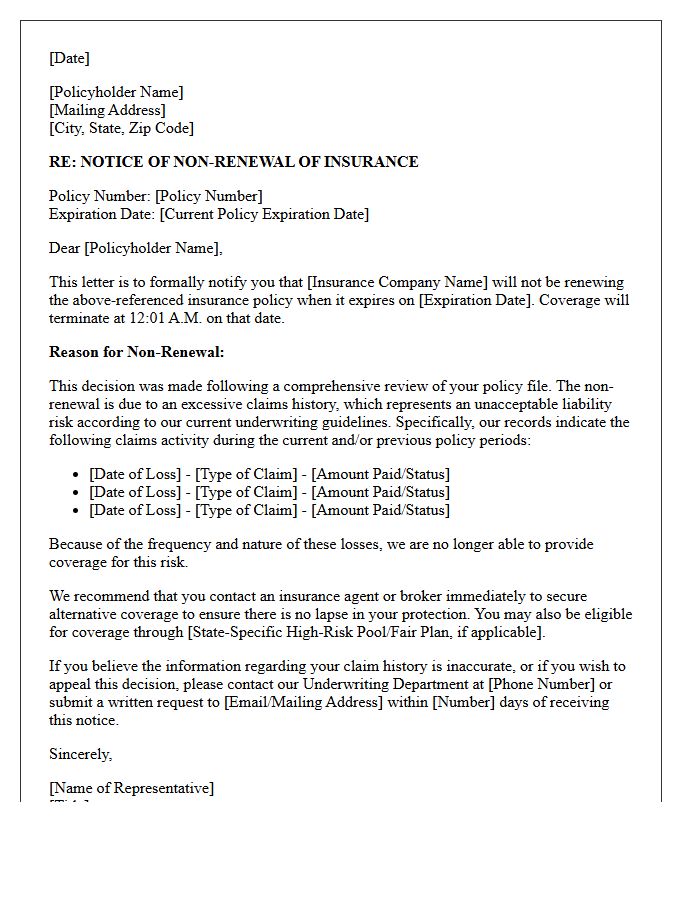
Receiving a Non-Renewal Letter due to excessive claims history indicates that an insurer views your frequent loss submissions as an unacceptable liability risk. This formal notice signifies the termination of coverage at the policy's expiration date. To mitigate future coverage denials, policyholders should review their claims frequency, implement safety improvements, and seek specialized high-risk insurance markets. Maintaining a clean record is essential for securing affordable premiums and long-term insurability in a competitive market.
Personal Auto High Liability Risk Non-Renewal Letter
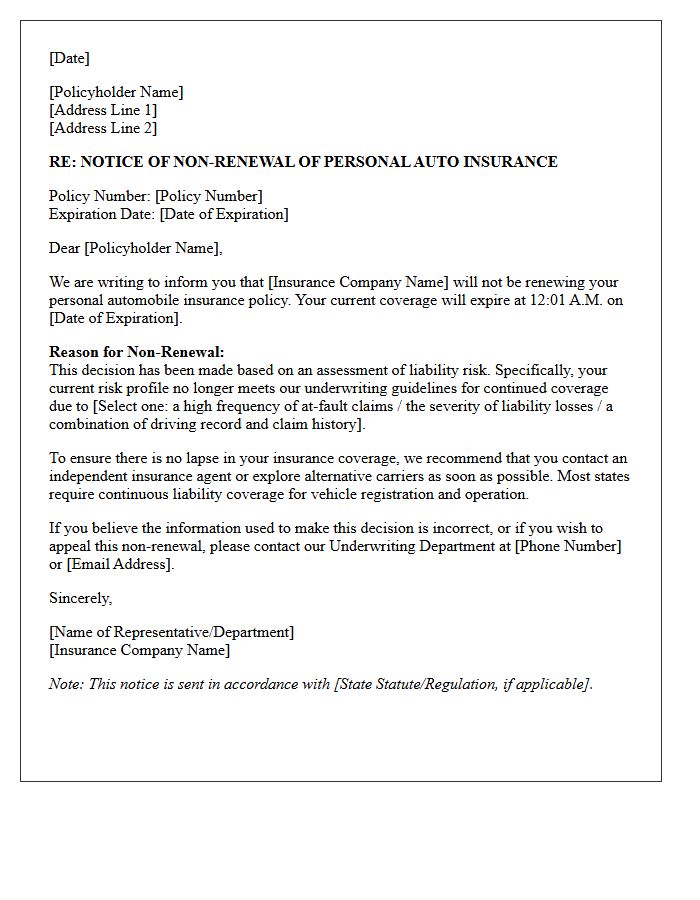
Receiving a non-renewal letter for personal auto insurance indicates the carrier will not extend coverage past the expiration date. This often occurs due to high liability risk, such as multiple at-fault accidents, severe traffic violations, or high-frequency claims. It is crucial to secure a new policy immediately to avoid a coverage lapse, which can significantly increase future premiums. If traditional insurers decline coverage, you may need to seek a high-risk specialist or a state-sponsored insurance plan to remain legally compliant on the road.
Homeowners Unmitigated Liability Risk Non-Renewal Letter
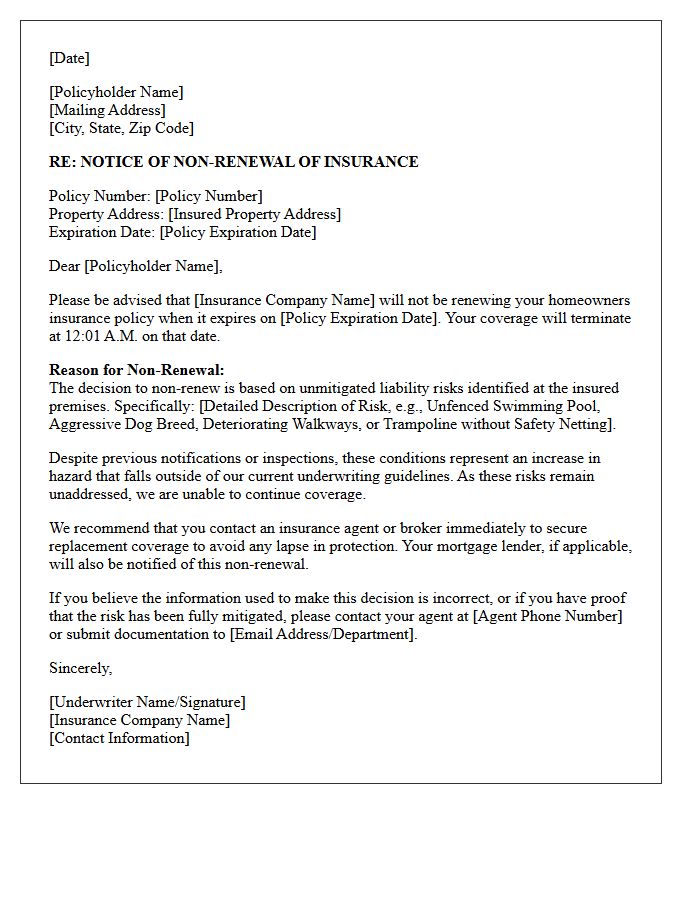
Receiving a non-renewal letter due to unmitigated liability risk indicates your insurer has identified safety hazards on your property. Common triggers include unfenced swimming pools, aggressive dog breeds, or decaying structures that increase the likelihood of injury claims. To secure coverage and avoid higher premiums in the high-risk market, you must promptly address these specific hazards. Failure to mitigate these issues can lead to a total loss of insurance eligibility, making it difficult to protect your home's financial value against future legal or medical liabilities.
Commercial Auto Unacceptable Liability Risk Non-Renewal Letter
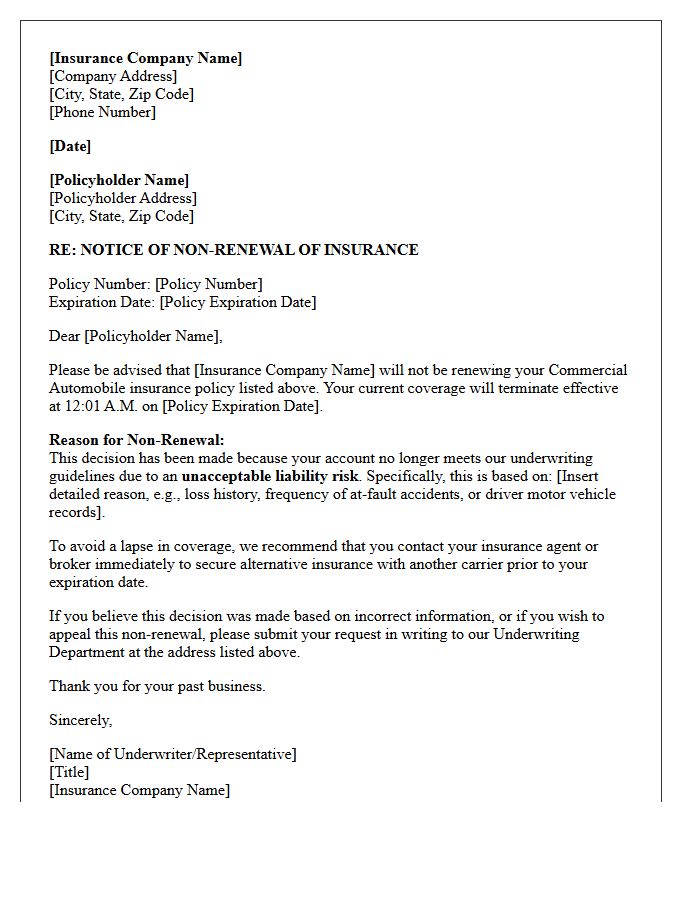
A Commercial Auto Unacceptable Liability Risk Non-Renewal Letter is a formal legal notice from an insurer terminating coverage due to excessive exposure. This action typically occurs when a policyholder's loss history, safety violations, or hazardous operations no longer meet underwriting guidelines. Receiving this letter means the carrier has deemed the business too volatile to insure. It is critical to review the specific reasons for non-renewal immediately and begin securing alternative coverage to avoid a lapse, which could lead to legal penalties and significantly higher insurance premiums in the future.
Cyber Security Unacceptable Liability Risk Non-Renewal Letter
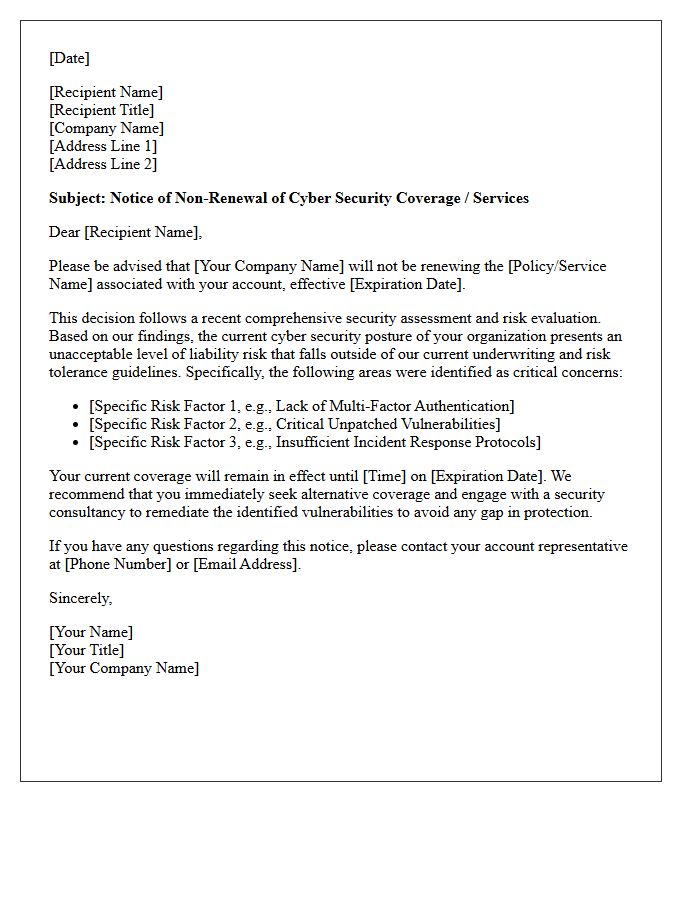
Receiving a Cyber Security Unacceptable Liability Risk Non-Renewal Letter means your insurance carrier has determined your digital defenses are insufficient for coverage. This often results from failed security audits, lack of multi-factor authentication, or outdated software. To restore eligibility, you must remediate identified vulnerabilities immediately. Failing to address these cybersecurity gaps can lead to permanent loss of coverage, leaving your organization financially exposed to data breaches and ransomware attacks. Prioritize strengthening your incident response plans and technical controls to mitigate this significant operational threat and secure future policy renewals.
Professional Liability Unacceptable Risk Non-Renewal Letter
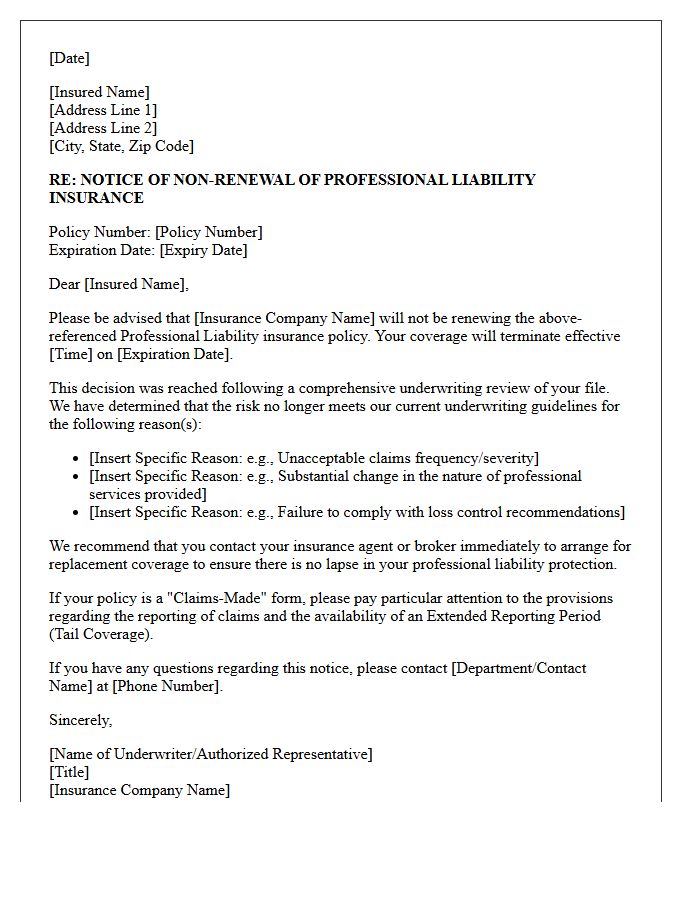
A Professional Liability Unacceptable Risk Non-Renewal Letter is a formal notification that an insurer will not extend coverage due to increased liability exposure. Receiving this document means the carrier has identified material changes in your risk profile, such as frequent claims, high-risk activities, or poor loss history. It is crucial to immediately seek alternative coverage to avoid a lapse in protection, as a non-renewal can make securing future policies more difficult and expensive. Always review the letter's specific reasons to implement necessary risk management improvements for your business.
Workers Compensation Unacceptable Liability Risk Non-Renewal Letter
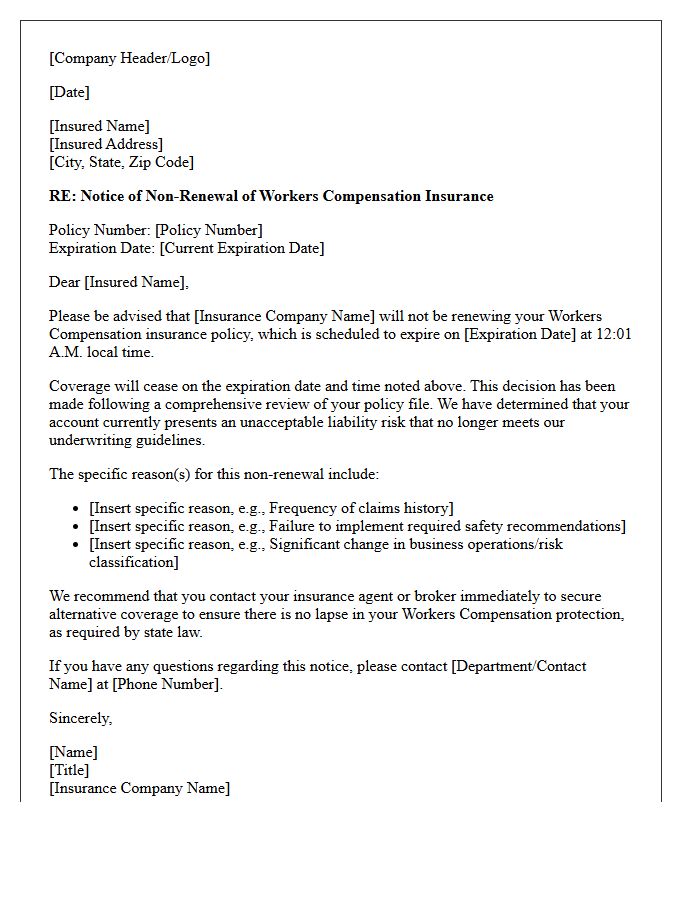
A workers' compensation non-renewal letter citing unacceptable liability risk is a formal notice that an insurer will no longer provide coverage. This typically occurs due to a high frequency of claims, unsafe working conditions, or significant changes in business operations that exceed the carrier's risk appetite. To maintain compliance and avoid legal penalties, businesses must immediately seek alternative coverage or enter a state-funded risk pool. Proactively improving safety protocols and loss control measures is essential to securing a new policy and lowering future premiums in a competitive insurance market.
Liquor Liability Unacceptable Risk Non-Renewal Letter
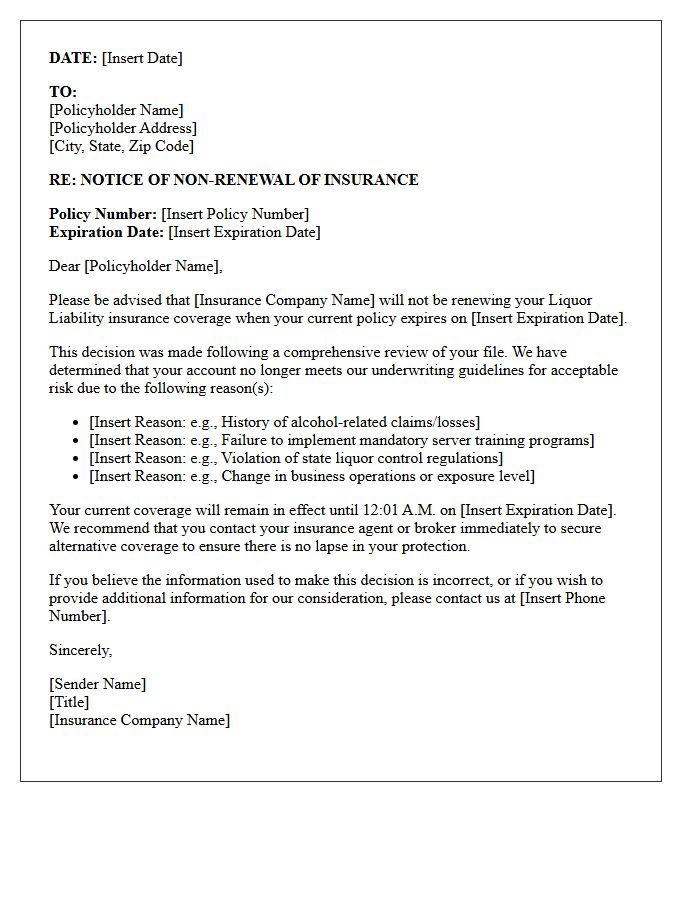
Receiving a Liquor Liability Non-Renewal Letter signifies that your establishment is now classified as an unacceptable risk. This typically occurs due to frequent claims, safety violations, or high-risk business models. To maintain coverage, you must immediately address the identified underwriting concerns and implement stricter risk management protocols. Promptly consulting a specialist broker is essential to secure alternative coverage and avoid a lapse in insurance, which could jeopardize your operating license and legal compliance. Proactive safety improvements are the only way to restore your insurability in a tightening market.
Landlord Property Unacceptable Liability Risk Non-Renewal Letter
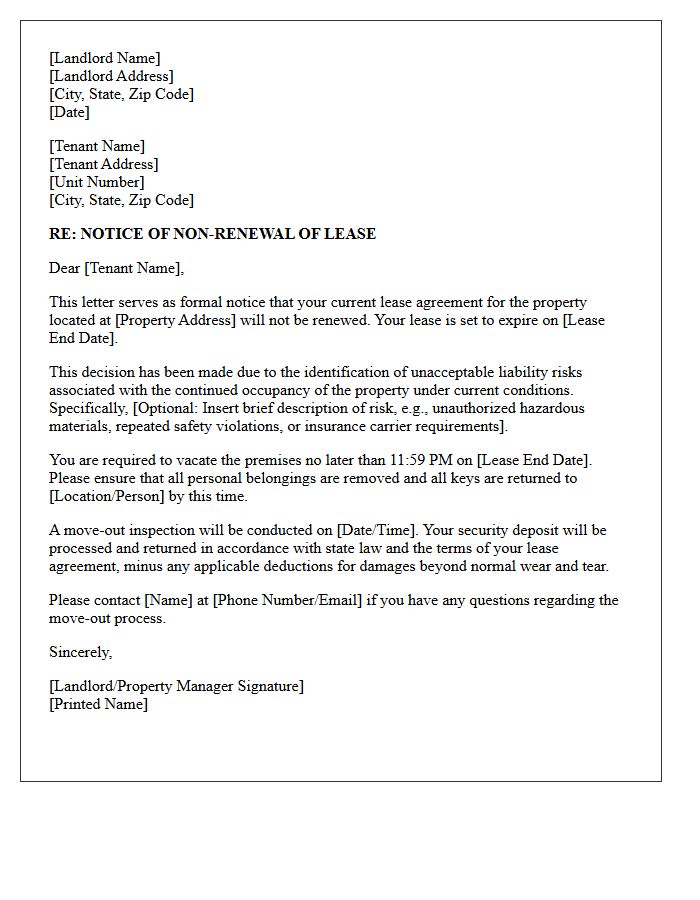
A Landlord Property Unacceptable Liability Risk Non-Renewal Letter is a formal notice terminating a lease due to high-risk conditions. This typically occurs when insurable hazards, such as aggressive pets, trampoline risks, or poor maintenance, threaten coverage. Receiving this notice means the underwriting criteria are no longer met, making the property a legal or financial burden. Landlords use this document to mitigate potential litigation and insurance cancellations. It is crucial to provide tenants with the required notice period according to local housing laws to ensure the non-renewal remains legally enforceable.
Manufacturing Facility Unacceptable Liability Risk Non-Renewal Letter
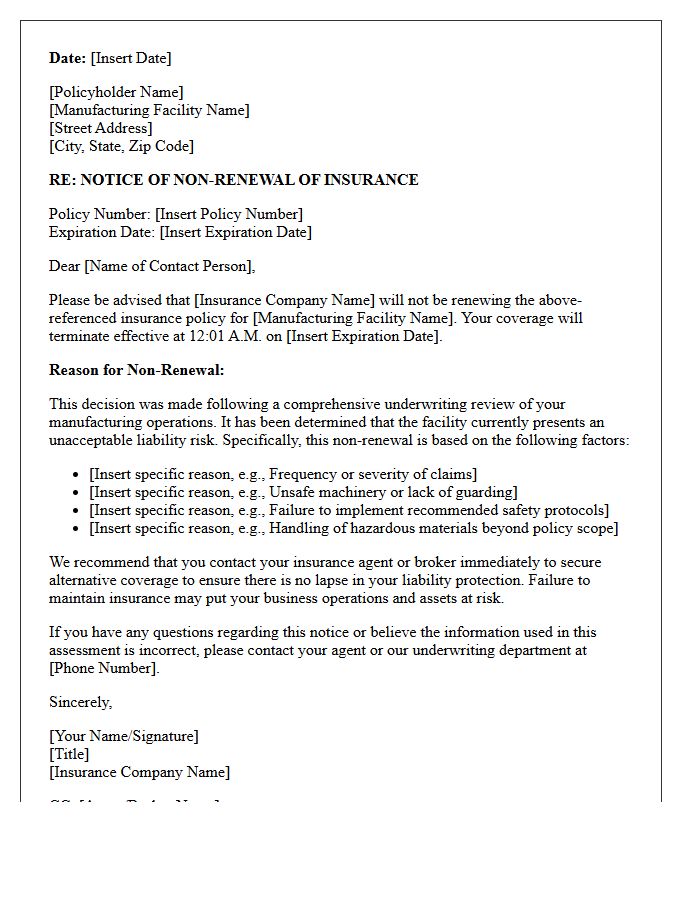
A manufacturing facility receives a non-renewal letter when an insurer identifies an unacceptable liability risk that exceeds their underwriting appetite. This formal notice signifies that coverage will cease at the policy expiration date. Common triggers include poor safety records, outdated machinery, or inadequate risk mitigation protocols. To secure new coverage, policyholders must immediately address these safety deficiencies and provide documentation of corrective actions. Failure to resolve these hazards can lead to higher premiums or total uninsurability, making proactive risk management essential for long-term operational stability and financial protection.
What is a Notice of Non-Renewal Due to Unacceptable Liability Risk?
A Notice of Non-Renewal Due to Unacceptable Liability Risk is a formal communication from an insurance carrier stating they will not extend coverage past the current policy expiration date because the policyholder's risk profile no longer meets their underwriting guidelines.
What factors cause an insurer to label a policy as an "Unacceptable Liability Risk"?
Common factors include a high frequency of claims, significant changes in business operations, failure to implement safety recommendations, or operating in a high-hazard industry that exceeds the insurer's current risk appetite.
Can I appeal a non-renewal notice based on liability concerns?
While insurance companies have the right to choose which risks they insure, you can request a formal review if you can demonstrate that the underlying safety hazards have been mitigated or if the notice was based on inaccurate loss history data.
How much time do I have to find new coverage after receiving this notice?
State laws typically require insurance companies to provide 30 to 60 days of advance notice before the policy expiration date, allowing the policyholder sufficient time to secure alternative coverage in the surplus or admitted market.
Will a non-renewal for liability risk make it harder to get insurance elsewhere?
Yes, a non-renewal can signal a higher risk profile to new carriers; however, working with a specialized broker to document improved safety protocols and risk management strategies can help you secure competitive terms with a new provider.
Comments