Moving from renting to owning requires a strategic shift in protection. A Renters to Homeowners Transition Insurance Letter helps clients navigate this change by explaining how to update coverage from personal property to full dwelling protection. This essential communication ensures no gaps in security during the closing process. Below are some ready to use templates to simplify your outreach.
Image cover: Essential Insurance Guide and Templates: Transitioning From Renting to Homeownership
Letter Samples List
- Congratulations on Your New Home Insurance Transition Letter
- Upgrading From Renters to Homeowners Insurance Letter
- First-Time Homebuyer Insurance Policy Transition Letter
- Preparing for Your Home Purchase Insurance Letter
- Converting Your Renters Policy to Homeowners Insurance Letter
- Exclusive Homeowners Insurance Quote Transition Letter
- Protecting Your New Investment Homeowners Insurance Letter
- Seamless Renters to Homeowners Insurance Transition Letter
- Understanding Your New Homeowners Insurance Needs Letter
- Bundle and Save on Your New Homeowners Insurance Letter
- Navigating the Renters to Homeowners Insurance Transition Letter
- Securing Your Escrow With Homeowners Insurance Letter
- Important Next Steps for Your Homeowners Insurance Letter
Congratulations on Your New Home Insurance Transition Letter
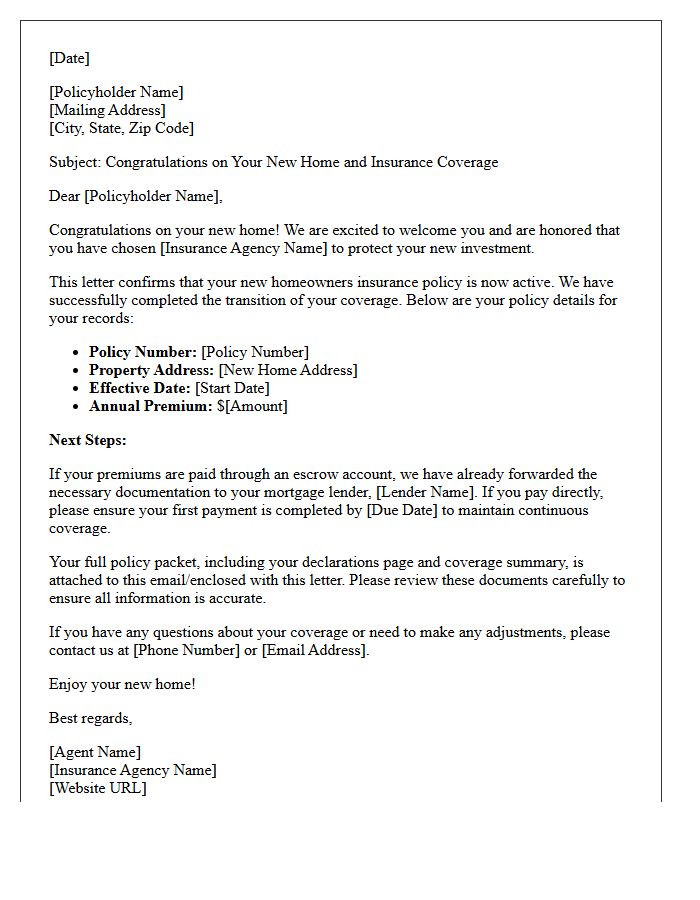
A New Home Insurance Transition Letter is a formal document confirming your coverage switch. It is crucial to verify that your effective date aligns perfectly with your closing or policy expiration to avoid protection gaps. Ensure the letter includes your mortgagee clause for the lender's records and outlines your new premium amounts. This transition ensures your property remains legally protected while potentially lowering costs or improving benefits. Always keep a copy of this notification to prove continuous insurance history for future provider evaluations.
Upgrading From Renters to Homeowners Insurance Letter
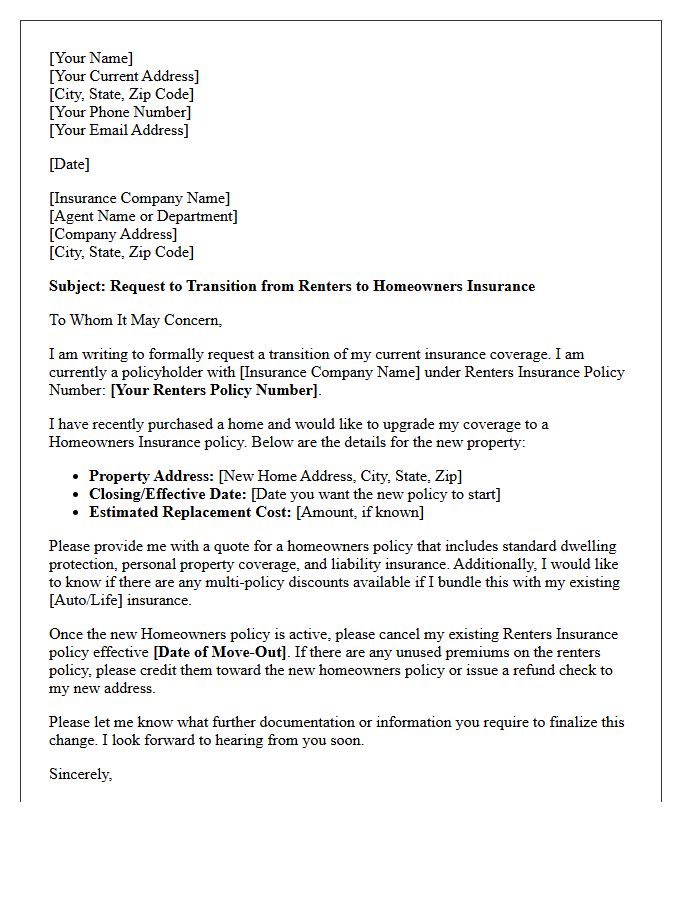
When transitioning from leasing to owning, an Upgrading From Renters to Homeowners Insurance Letter serves as formal notice to your provider. It is essential to cancel your previous tenant policy while establishing comprehensive coverage for your new property's structure and liability. Homeowners insurance offers significantly higher protection limits compared to renters' plans. Ensure your letter includes the effective date of the new policy and your new address to avoid coverage gaps. Timely communication ensures continuous protection for your investment and compliance with mortgage lender requirements during the closing process.
First-Time Homebuyer Insurance Policy Transition Letter
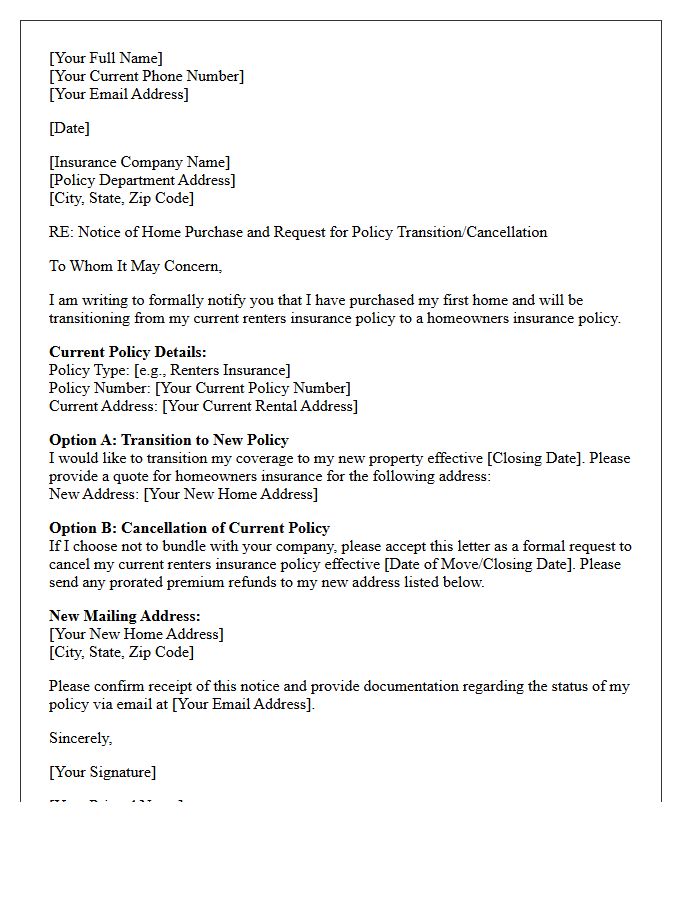
A First-Time Homebuyer Insurance Policy Transition Letter is a critical document used to transfer escrow billing responsibilities from the buyer to the mortgage lender. This letter ensures your homeowners insurance premiums are paid automatically through your monthly mortgage payment. It serves as official proof of coverage for the financial institution, confirming that the property is protected against risks. Providing this transition letter promptly prevents lapses in coverage and avoids the costly forced-place insurance that lenders might otherwise impose to protect their investment during the closing process.
Preparing for Your Home Purchase Insurance Letter
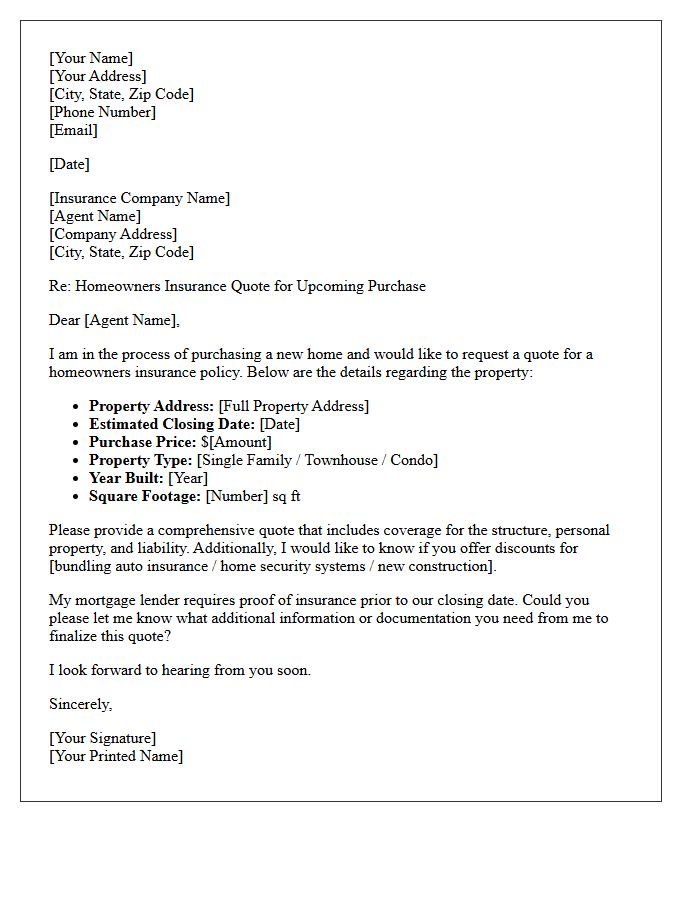
When preparing for your home purchase insurance letter, ensure you secure a binder or proof of coverage early to avoid closing delays. Lenders require this document to verify that the property is protected against hazards. Double-check that your coverage limits match the lender's specific requirements and that their mortgagee clause is listed accurately. Providing your agent with the property's age, roof condition, and safety features will help expedite the process, ensuring a smooth transition to homeownership with comprehensive financial protection.
Converting Your Renters Policy to Homeowners Insurance Letter
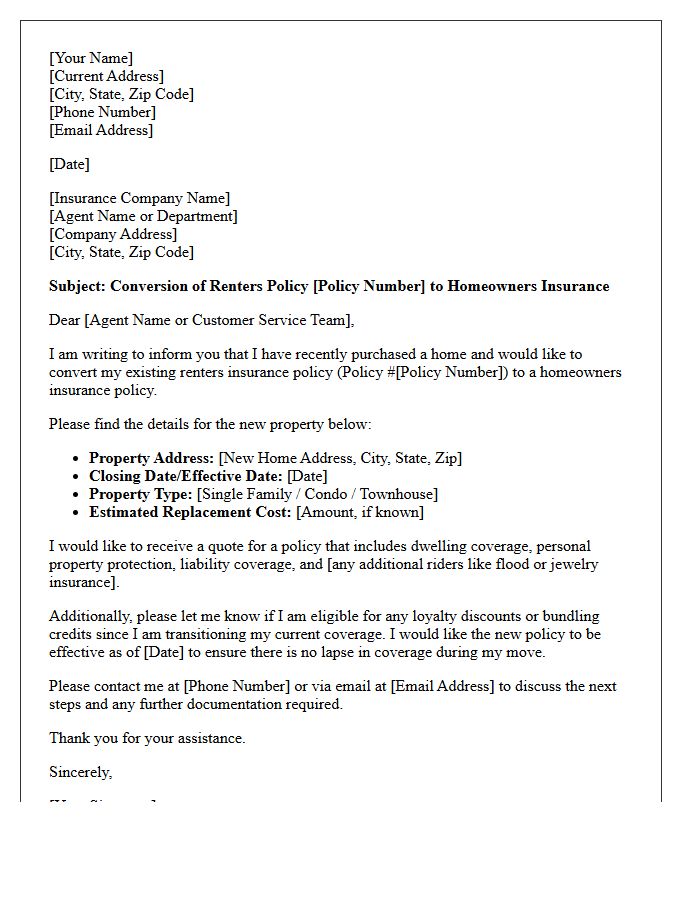
When transitioning from renting to owning, you must send a formal notification letter to your insurance provider. This document requests to convert your existing renters policy into a comprehensive homeowners plan. It is vital to specify your closing date and the new property address to ensure continuous protection. Mentioning security upgrades in your new home may also qualify you for premium discounts. Providing clear instructions ensures your liability coverage and personal property limits are appropriately adjusted for your new investment without any gaps in service.
Exclusive Homeowners Insurance Quote Transition Letter
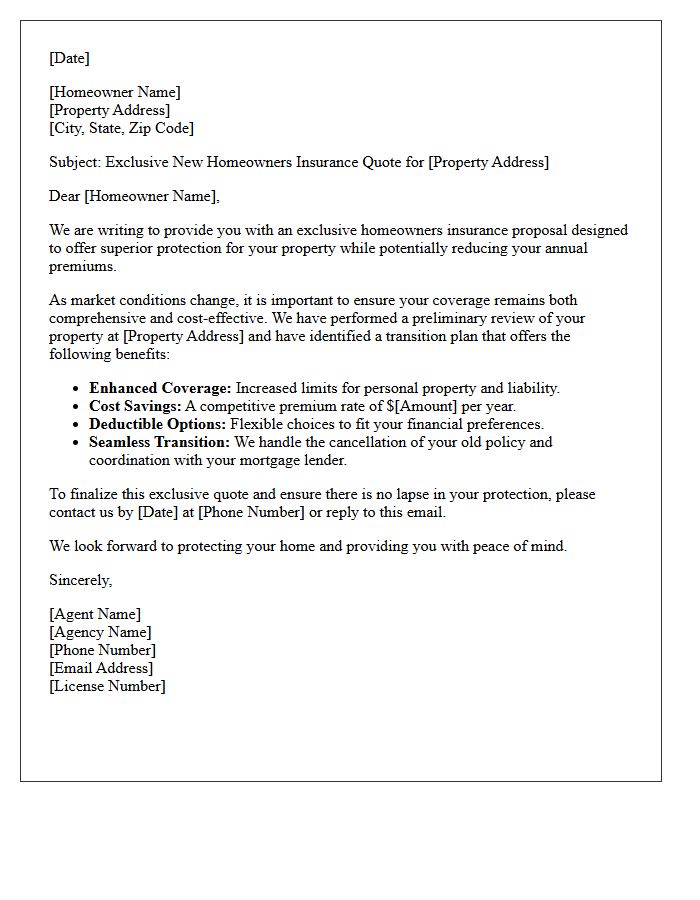
An Exclusive Homeowners Insurance Quote Transition Letter is a formal notification informing policyholders that their coverage is moving to a new provider. This document is essential for maintaining continuous protection during agency acquisitions or carrier changes. It outlines updated premium rates, policy terms, and effective dates to ensure a seamless coverage transfer. Homeowners must review these letters carefully to confirm their mortgage escrow details remain accurate and to prevent any potential lapses in insurance that could leave their property vulnerable during the transition period.
Protecting Your New Investment Homeowners Insurance Letter
A homeowners insurance letter serves as official proof of coverage required by mortgage lenders to protect your new investment. It confirms that your property is adequately insured against structural damage, theft, and liability claims. Reviewing this document ensures your policy limits align with your loan requirements and current rebuilding costs. Failing to maintain active coverage can lead to force-placed insurance, which is often more expensive and offers less protection. Always verify that your lender's clause information is correctly listed to avoid processing delays or escrow complications during your home purchase.
Seamless Renters to Homeowners Insurance Transition Letter
A transition letter facilitates a smooth shift from renters to homeowners insurance, ensuring continuous protection. It informs your provider of your new property purchase, allowing them to transfer existing credits or loyalty discounts to the new policy. This document is essential for satisfying mortgage lender requirements and preventing coverage gaps during your move. By formally requesting this update, you simplify the administrative process and may secure lower premiums through bundled policy options. Always verify the effective date to maintain seamless liability and personal property coverage throughout the transition.
Understanding Your New Homeowners Insurance Needs Letter
Receiving a Homeowners Insurance Needs Letter typically indicates a change in your property's replacement cost or coverage requirements. This notification often follows a recent inspection, inflation adjustments, or updates to local building codes. It is essential to review these changes promptly to ensure your dwelling protection aligns with current market values. Failing to address the requested updates could leave you underinsured during a total loss. Always compare the suggested limits with your actual policy to maintain comprehensive financial security and avoid potential gaps in your homeowners coverage.
Bundle and Save on Your New Homeowners Insurance Letter
Receiving a Bundle and Save letter is a key opportunity to reduce your annual premiums. By combining your homeowners insurance with an auto policy under one carrier, you unlock a multi-policy discount. This strategy simplifies your billing process while providing comprehensive coverage for your assets. To maximize these savings, always compare the total package price against separate policies to ensure you are getting the best market value. Act promptly on these offers, as bundling is the most effective way to lower your overall insurance costs without sacrificing essential protection.
Navigating the Renters to Homeowners Insurance Transition Letter
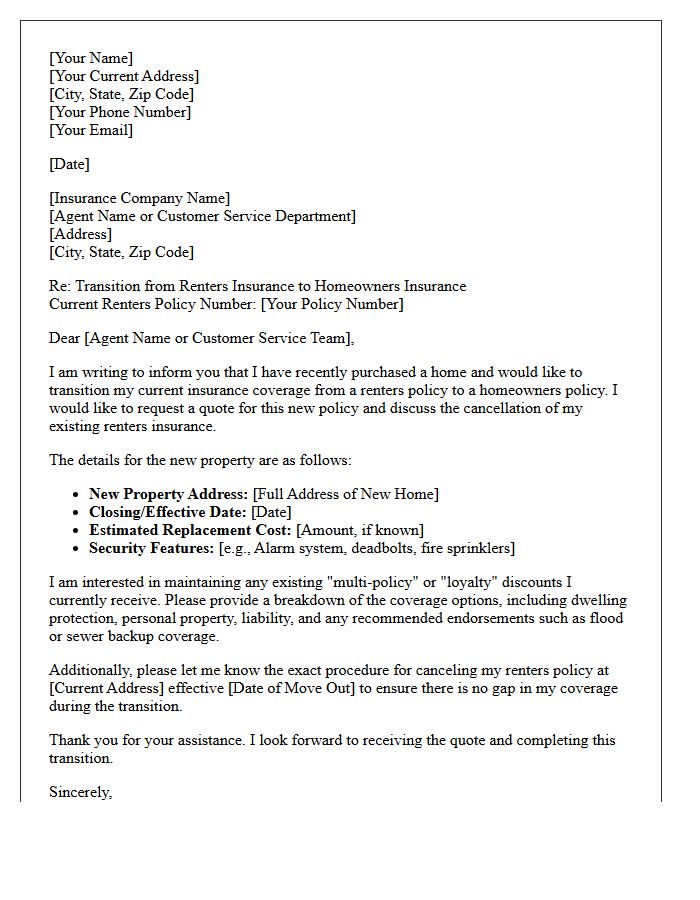
Transitioning from renters to homeowners insurance requires formal notification to your carrier. A well-structured transition letter ensures a seamless transfer of liability coverage and protects your equity from day one. You must specify your policy cancellation date and provide your new property details to avoid coverage gaps. This document serves as legal proof of change, facilitating the refund of unused premiums from your previous policy. Proactively managing this switch guarantees that your most significant investment remains fully protected during the move while maintaining continuous insurance history.
Securing Your Escrow With Homeowners Insurance Letter
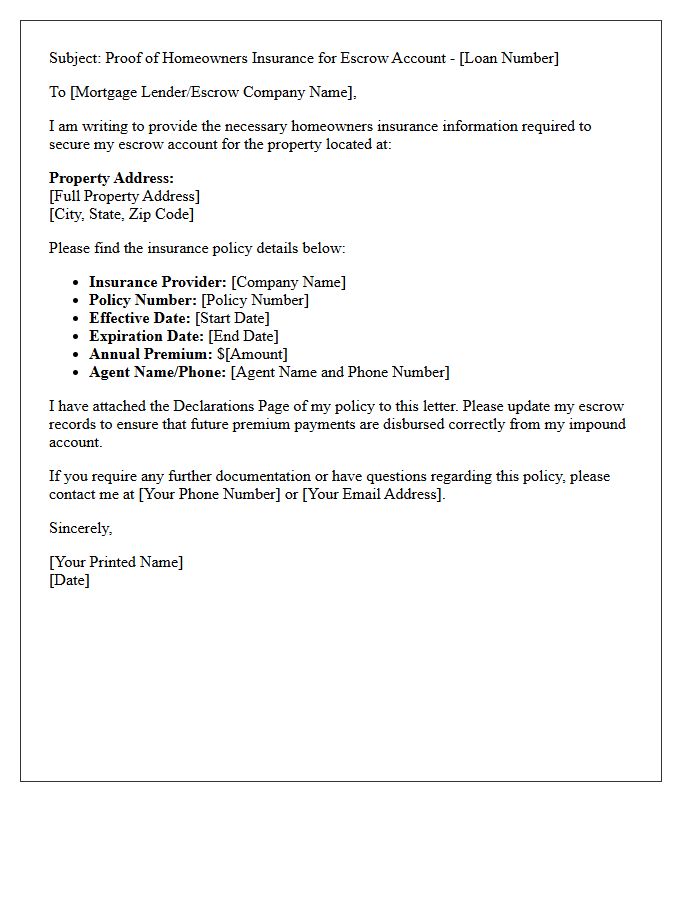
To finalize your real estate closing, providing a Homeowners Insurance Evidence of Property letter is essential. This document proves to your lender that the asset is fully protected against hazards. Ensure your policy includes an escrow billing clause, which allows the lender to manage premium payments through your monthly mortgage installment. Verifying that the mortgagee clause contains the correct lender name and address prevents delays. Securing this letter early guarantees a seamless transition and confirms your financial compliance before the loan is funded.
Important Next Steps for Your Homeowners Insurance Letter
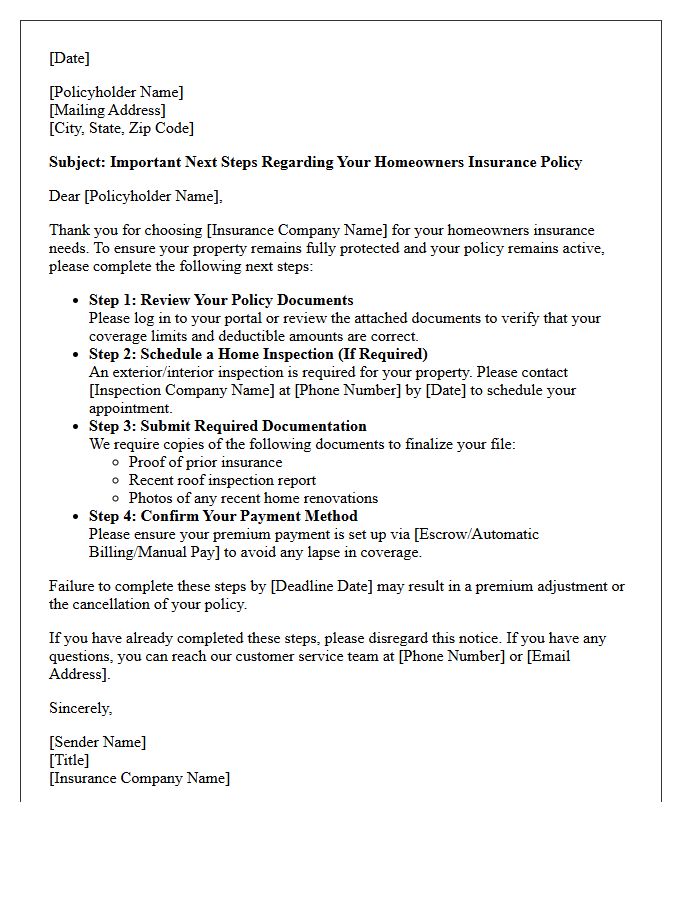
Upon receiving a homeowners insurance letter, you must immediately review your coverage limits to ensure they reflect current rebuilding costs. Closely examine the declarations page for any changes in premiums or deductibles. If the notice mentions a non-renewal or required repairs, document all property upgrades and contact your agent to discuss mitigation strategies. Timely action prevents a lapse in protection, safeguarding your property investment against unforeseen disasters. Always respond to information requests by the specified deadline to maintain valid policy status and ensure continuous financial security for your home.
What is a Renters to Homeowners Transition Insurance Letter?
A Renters to Homeowners Transition Insurance Letter is a formal document provided by an insurance carrier confirming that a policyholder is moving from a tenant policy (HO-4) to a homeowners policy (HO-3 or similar). It often serves as proof of continuous coverage and can help the policyholder secure multi-policy discounts or loyalty credits during the home-buying process.
How does transitioning from renters to homeowners insurance affect my premiums?
While homeowners insurance is more expensive than renters insurance due to the coverage of the physical structure, transitioning often triggers "tenure" or "loyalty" discounts. By providing a transition letter to your provider, you may qualify for bundle rates and a waiver of "new business" surcharges because you have a documented history of continuous coverage.
Can a transition letter help me satisfy mortgage lender requirements?
Yes. Mortgage lenders require proof of a homeowners insurance policy before closing on a property. A transition letter from your current insurer demonstrates that you have an active policy being converted to meet the new property's requirements, ensuring there is no lapse in coverage that could delay your closing date.
Do I need to cancel my renters insurance before getting homeowners insurance?
No, you should not cancel your renters insurance until the day you officially close on your new home. A transition letter coordinates the effective dates so that your renters policy expires the moment your homeowners policy begins, preventing any gaps in liability protection or personal property coverage during the move.
Does a history of renters insurance lower homeowners insurance rates?
Yes, insurance companies view applicants with a continuous insurance history as lower risk. Presenting a transition letter that proves you maintained renters insurance for several years can lead to lower "tier" placement and significantly reduced rates on your new homeowners policy compared to a first-time applicant with no prior coverage history.
Comments