Navigating Self-Employed Individual Health Coverage Options is essential for freelancers and entrepreneurs seeking reliable medical benefits. This guide outlines how to communicate effectively with insurers or employees regarding plan availability and enrollment requirements. Understanding your choices ensures financial security and comprehensive care. To simplify your administrative tasks, below are some ready to use template.
Image cover: Official Health Insurance Verification Templates for the Self-Employed
Letter Samples List
- Self-Employed Health Coverage Introduction Letter
- Open Enrollment Notification Letter for Self-Employed Individuals
- Health Insurance Tax Deduction Guide Letter for Freelancers
- COBRA Alternative Health Plan Letter for Independent Contractors
- Premium Tax Credit Eligibility Letter for Self-Employed Clients
- Annual Health Coverage Renewal Letter for Sole Proprietors
- Short-Term Health Insurance Options Letter for Gig Workers
- High-Deductible Health Plan and HSA Options Letter for Entrepreneurs
- Family Health Coverage Options Letter for Self-Employed Professionals
- Special Enrollment Period Qualification Letter for Independent Workers
- State Health Exchange Policy Update Letter for Sole Proprietorships
- Supplemental Dental and Vision Coverage Letter for Freelance Workers
Self-Employed Health Coverage Introduction Letter
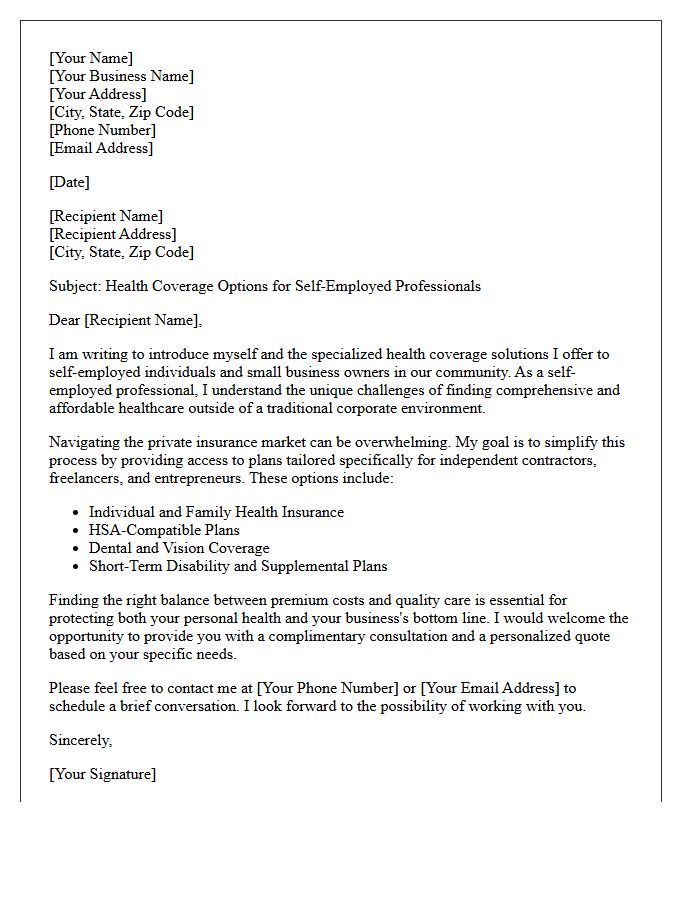
A Self-Employed Health Coverage Introduction Letter is a vital document used to verify insurance eligibility for independent workers. This formal notice confirms your status as a business owner or freelancer to providers and tax authorities. It must clearly outline your enrollment details, premium costs, and coverage effective dates. Providing accurate information ensures you qualify for the Self-Employed Health Insurance Deduction, which reduces your adjusted gross income. Always include your Tax Identification Number and legal business name to maintain compliance with current healthcare regulations and internal revenue standards.
Open Enrollment Notification Letter for Self-Employed Individuals
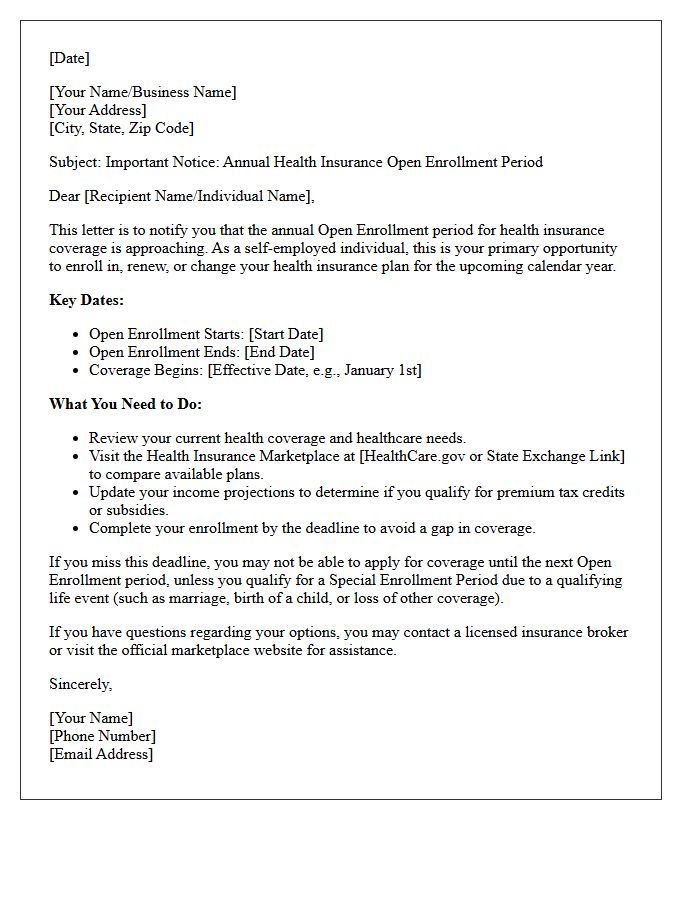
Self-employed individuals must watch for the Open Enrollment Notification Letter to secure health insurance for the upcoming year. This document outlines your eligibility for premium tax credits and provides essential deadlines for plan selection. Since you lack employer-sponsored coverage, missing this window may prevent you from enrolling until the next cycle unless you experience a qualifying life event. Carefully review your income projections to ensure your subsidy calculations remain accurate and avoid potential tax penalties while maintaining continuous healthcare protection.
Health Insurance Tax Deduction Guide Letter for Freelancers
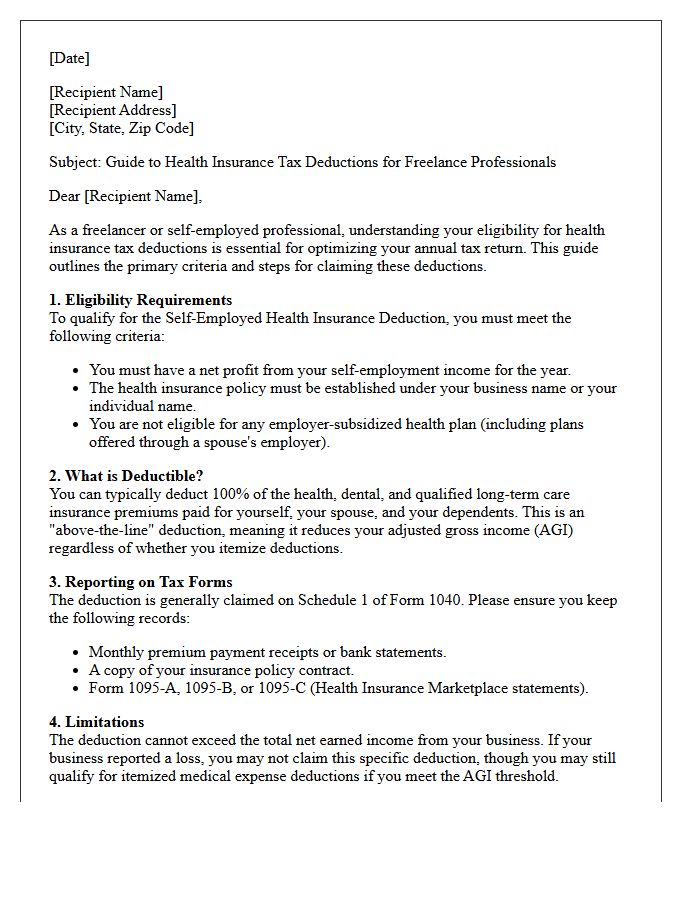
Freelancers can significantly lower their taxable income by utilizing the Self-Employed Health Insurance Deduction. This adjustment allows you to deduct 100% of health, dental, and qualified long-term care insurance premiums for yourself, your spouse, and dependents. To qualify, you must have net profit reported on Schedule C or F and not be eligible for an employer-sponsored plan through a spouse. This deduction is taken "above-the-line," meaning it reduces your adjusted gross income (AGI) even if you do not itemize expenses, providing essential tax relief for independent professionals.
COBRA Alternative Health Plan Letter for Independent Contractors
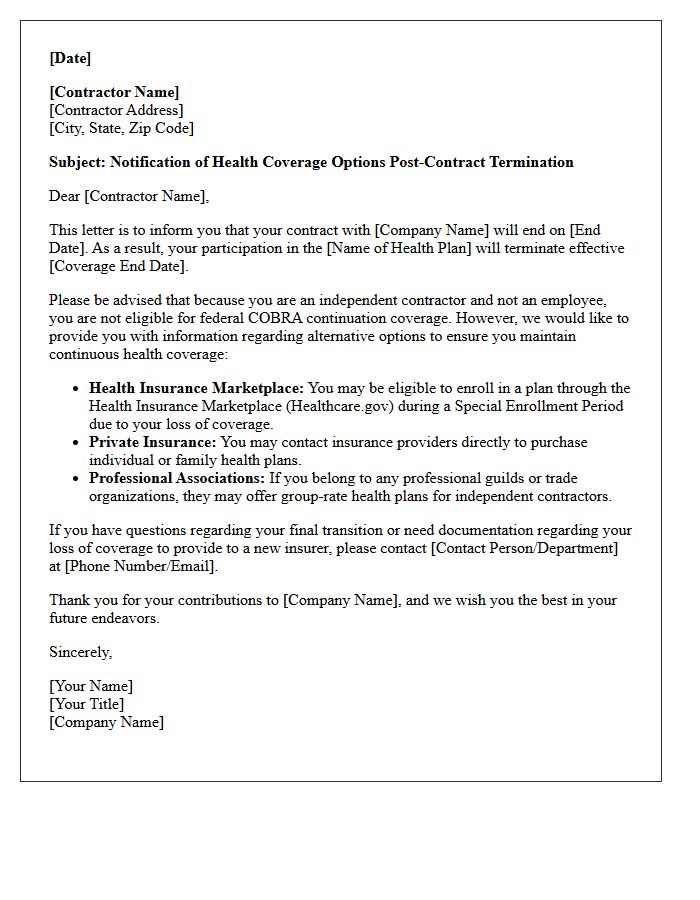
Independent contractors typically do not qualify for COBRA, as it applies only to W-2 employees. If you receive a COBRA Alternative Health Plan Letter, it serves as a formal notification regarding private insurance options available outside of employer-sponsored coverage. These alternatives often include ACA Marketplace plans, short-term health insurance, or cost-sharing programs. Understanding these enrollment windows is critical to avoiding coverage gaps, as contractors must secure independent policies to maintain healthcare protection without traditional corporate benefits.
Premium Tax Credit Eligibility Letter for Self-Employed Clients
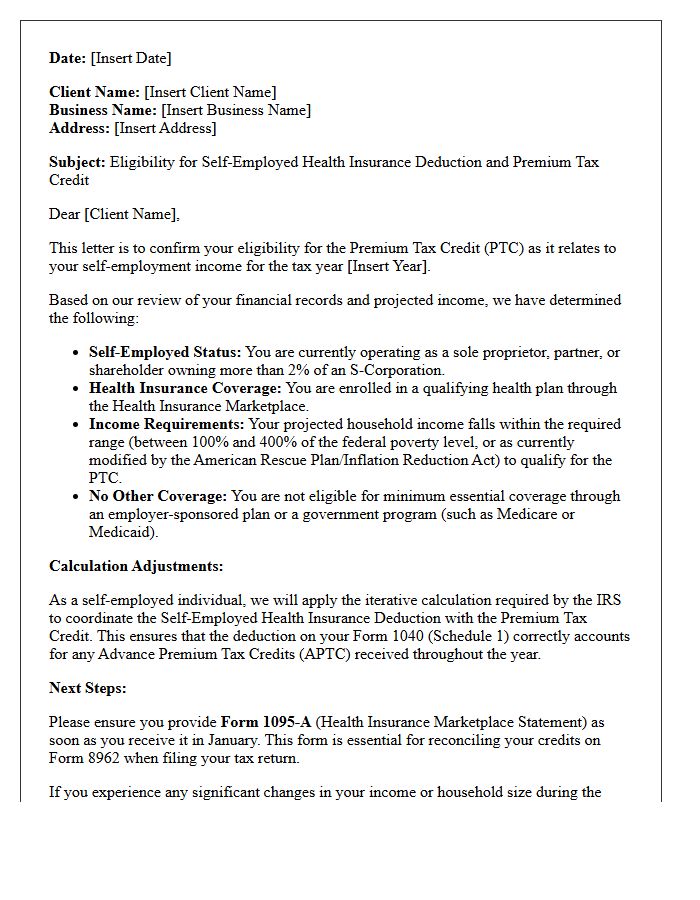
A Premium Tax Credit Eligibility Letter is a vital document for self-employed individuals to verify their projected annual income. Because freelancers lack traditional paystubs, the Health Insurance Marketplace requires this attestation to determine subsidy levels. It ensures that your estimated Net Self-Employment Income aligns with the criteria for lowered monthly premiums. Accuracy is essential to avoid potential repayment of credits during tax filing. This letter serves as formal proof of financial status, allowing entrepreneurs to access affordable coverage while maintaining compliance with federal Affordable Care Act regulations.
Annual Health Coverage Renewal Letter for Sole Proprietors
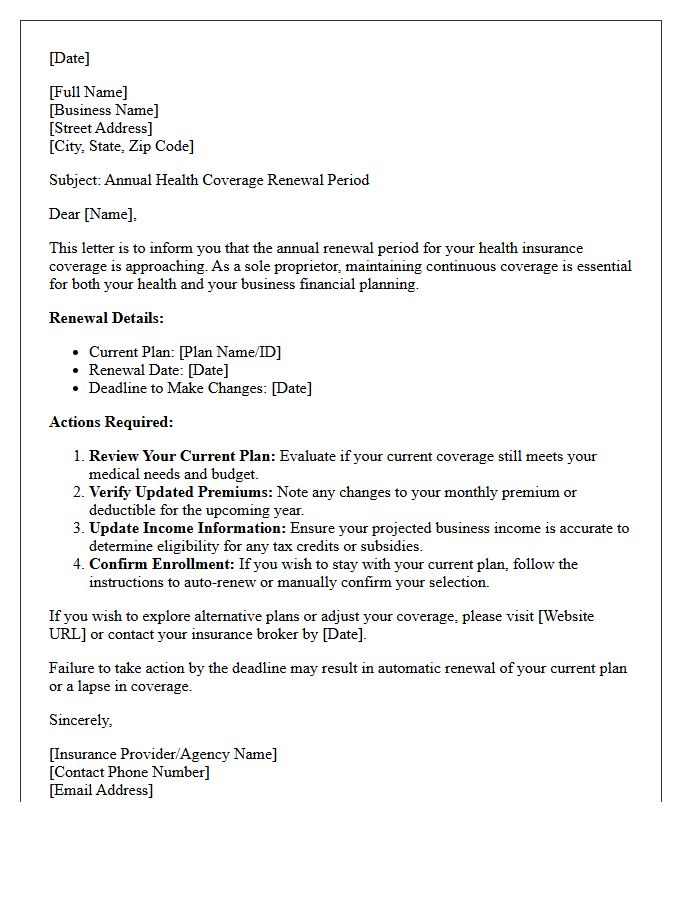
As a sole proprietor, you must prioritize the Annual Health Coverage Renewal Letter to ensure continuous insurance. This document outlines critical changes to your monthly premiums, deductible amounts, and benefit structures for the upcoming year. It is the essential notice for the Open Enrollment period, allowing you to re-evaluate your plan's cost-effectiveness. Failure to respond or update your information can lead to automatic re-enrollment in a plan that no longer fits your business budget or healthcare needs. Always verify your income estimates to maintain accurate subsidy eligibility and avoid coverage gaps.
Short-Term Health Insurance Options Letter for Gig Workers
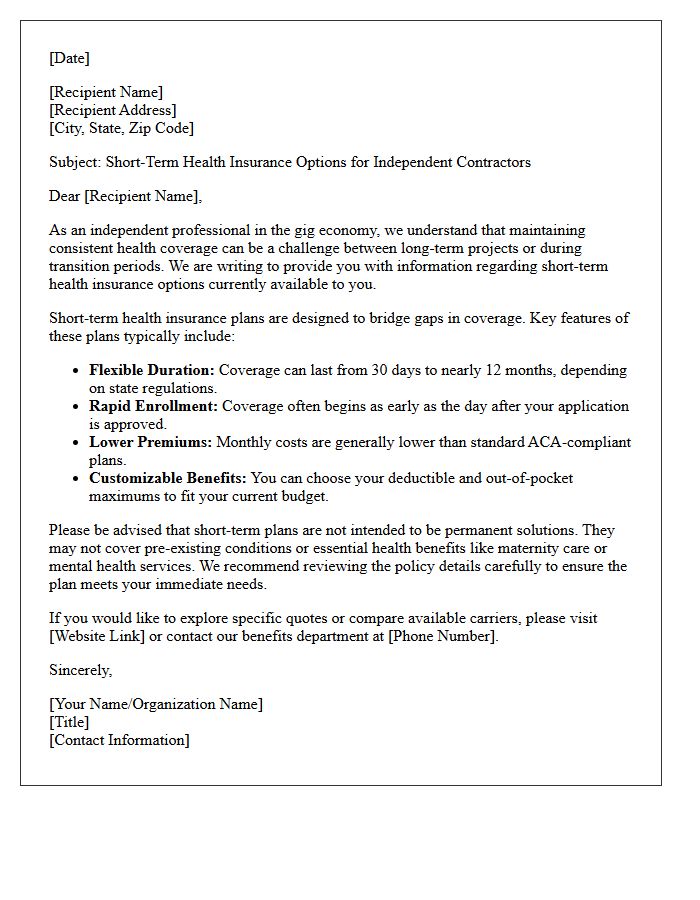
A short-term health insurance options letter provides gig workers with a vital overview of temporary medical coverage solutions. These plans offer immediate protection during employment gaps or transition periods. It is crucial to review the limitations, as short-term policies often exclude pre-existing conditions and essential benefits found in ACA-compliant plans. Understanding the duration limits and renewal terms helps independent contractors bridge the gap until permanent coverage is secured. This document serves as a guide for navigating flexible, low-cost alternatives tailored for the modern mobile workforce.
High-Deductible Health Plan and HSA Options Letter for Entrepreneurs
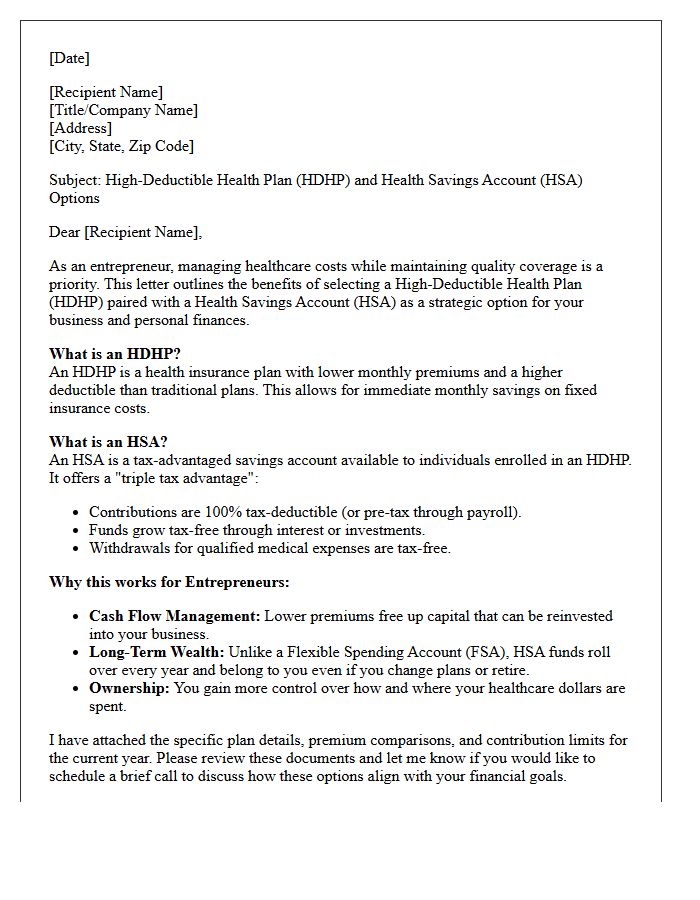
Entrepreneurs should prioritize the High-Deductible Health Plan (HDHP) to unlock tax-advantaged savings. This specific insurance structure is the only way to qualify for a Health Savings Account (HSA), which offers a triple tax benefit: contributions are tax-deductible, growth is tax-free, and withdrawals for medical expenses are untaxed. For business owners, an HSA serves as both a healthcare safety net and a long-term investment vehicle. Reviewing your HSA Options Letter ensures you select a provider with low fees and diverse investment choices to maximize your wealth while maintaining essential coverage.
Family Health Coverage Options Letter for Self-Employed Professionals
Self-employed professionals should prioritize the Family Health Coverage Options Letter to understand tax-advantaged insurance pathways. This document outlines eligibility for the Self-Employed Health Insurance Deduction, allowing individuals to lower their adjusted gross income by deducting premiums for themselves and dependents. It compares Marketplace plans with private group options, ensuring entrepreneurs find comprehensive medical protection while maximizing savings. Reviewing these options during open enrollment or qualifying life events is essential for maintaining affordable, high-quality family healthcare without traditional employer-sponsored benefits.
Special Enrollment Period Qualification Letter for Independent Workers
Independent workers qualifying for a Special Enrollment Period must provide a Qualification Letter as legal proof of a qualifying life event. This document verifies changes like losing job-based insurance, relocating, or marriage, allowing you to enroll in healthcare outside the standard window. Typically issued by an employer or previous insurer, this letter must include your name and the exact coverage end date. Submitting this eligibility notice within sixty days is critical to maintaining continuous health protection and avoiding coverage gaps while working independently.
State Health Exchange Policy Update Letter for Sole Proprietorships
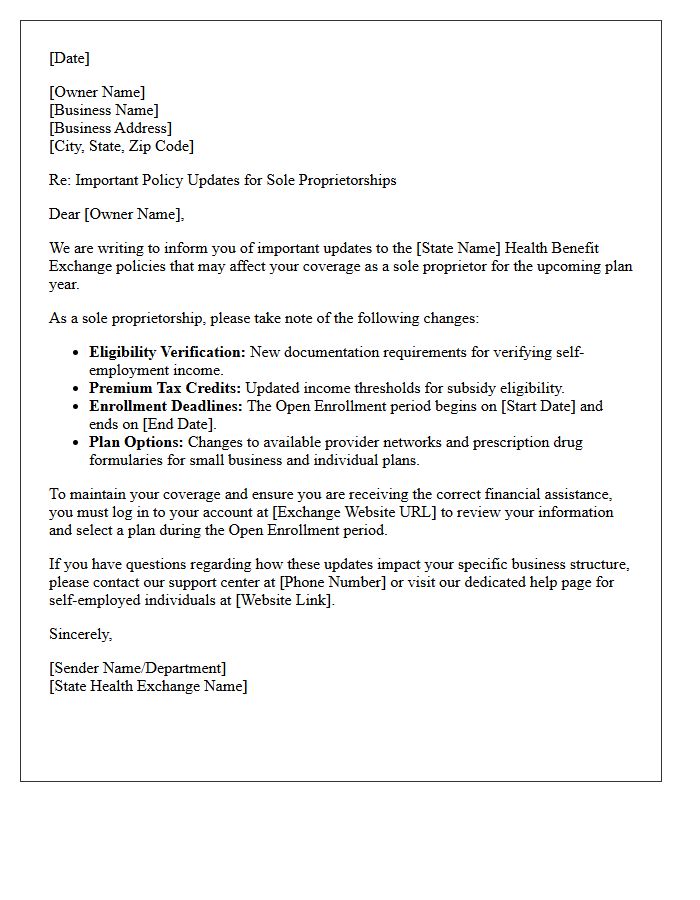
A State Health Exchange Policy Update Letter informs sole proprietorships about critical changes to coverage eligibility and enrollment periods. Under new ACA compliance guidelines, individual owners must verify if they qualify for small group markets or individual subsidies. These letters often outline updated premium rates and mandatory documentation required to maintain valid insurance status. Reviewing these updates ensures your business remains compliant while securing affordable health insurance options. Failure to respond to these notices can result in a loss of coverage or missed tax credit opportunities during the annual open enrollment cycle.
Supplemental Dental and Vision Coverage Letter for Freelance Workers
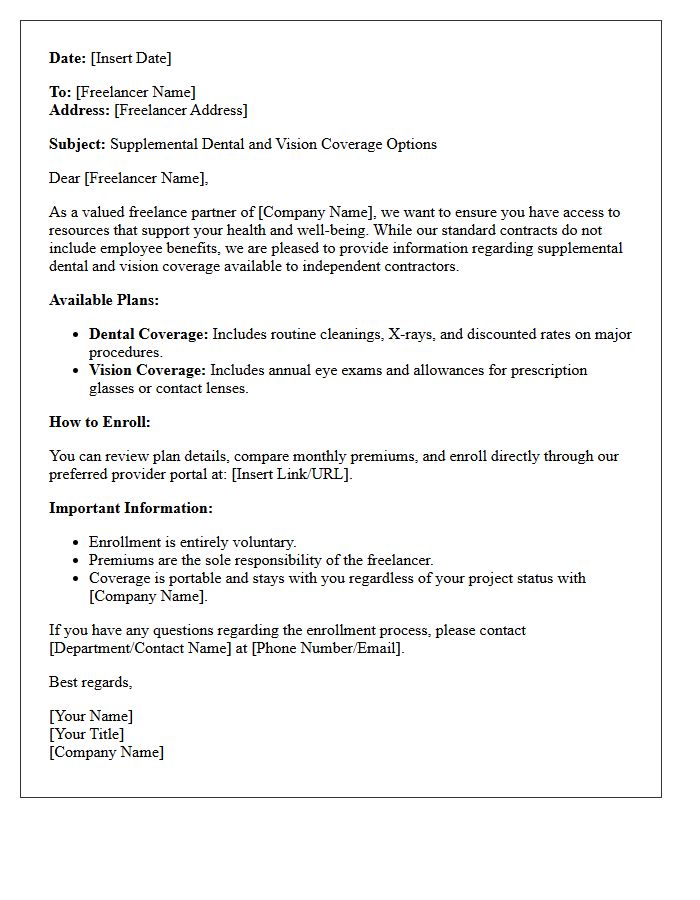
Freelance workers often lack employer-sponsored benefits, making a Supplemental Dental and Vision Coverage Letter essential for securing private insurance. This document serves as a formal notification or application to access specialized health plans tailored for independent contractors. It typically outlines coverage levels, monthly premiums, and provider networks. Understanding these options is vital for maintaining long-term wellness and managing out-of-pocket costs. Receiving this letter allows freelancers to bridge the protection gap, ensuring access to routine checkups and corrective care without the backing of a traditional corporate benefits package.
What is the Self-Employed Individual Health Coverage Options Letter?
The Self-Employed Individual Health Coverage Options Letter is a formal notification sent to self-employed persons outlining their eligibility for health insurance plans, available subsidies, and enrollment periods under the Affordable Care Act (ACA).
How can a self-employed person qualify for health insurance tax credits?
Self-employed individuals may qualify for premium tax credits if their estimated annual household income falls between 100% and 400% of the federal poverty level and they purchase a plan through the Health Insurance Marketplace.
Are health insurance premiums tax-deductible for the self-employed?
Yes, self-employed individuals can typically deduct 100% of their health insurance premiums for themselves, their spouses, and their dependents on their federal income tax return, provided they are not eligible for an employer-sponsored plan.
What enrollment options are available for self-employed individuals?
Self-employed individuals can enroll in health coverage during the annual Open Enrollment Period or during a Special Enrollment Period if they experience a qualifying life event, such as losing previous coverage, getting married, or having a child.
What documents are needed to verify income for self-employed health coverage?
To verify income for health coverage options, self-employed individuals usually need to provide their most recent federal tax return (Form 1040), Schedule C, or a ledger of business income and expenses to estimate their Modified Adjusted Gross Income (MAGI).

Comments