If traditional group coverage is too costly, a Small Business Open Enrollment Alternative Letter helps employers introduce affordable health benefits like ICHRAs or QSEHRA plans. This communication explains how staff can use tax-free stipends to purchase individual insurance during the enrollment window, ensuring compliance and transparency. To simplify your process, below are some ready to use template.
Image cover: Alternative Benefit Options: Employee Notice Templates and Letter Samples
Letter Samples List
- Small Business Open Enrollment Alternative Strategy Letter
- Level-Funded Health Plan Open Enrollment Alternative Letter
- Individual Coverage Health Reimbursement Arrangement Alternative Letter
- Off-Cycle Benefit Strategy And Alternative Open Enrollment Letter
- Qualified Small Employer Reimbursement Alternative Letter
- Professional Employer Organization Benefit Alternative Letter
- Cost-Saving Healthcare Options And Alternative Open Enrollment Letter
- Partial Self-Funding Open Enrollment Alternative Letter
- Direct Primary Care And Health Sharing Alternative Letter
- Flexible Group Benefits Open Enrollment Alternative Letter
- Early Renewal Strategy And Open Enrollment Alternative Letter
- Year-Round Benefit Solutions Alternative Open Enrollment Letter
Small Business Open Enrollment Alternative Strategy Letter
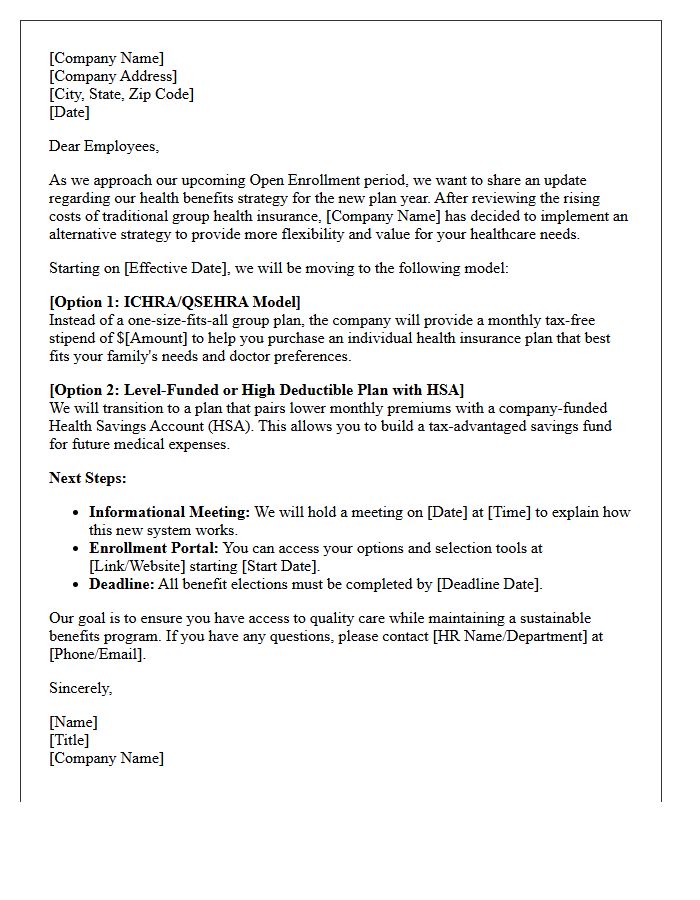
A Small Business Open Enrollment Alternative Strategy Letter is a formal document notifying employees of a shift from traditional group plans to Individual Coverage Health Reimbursement Arrangements (ICHRAs). This strategy allows employers to provide tax-free defined contributions, enabling staff to select personalized insurance via the individual marketplace. It is a critical tool for managing rising premiums while maintaining compliance. The letter ensures clear communication regarding transition timelines, enrollment steps, and how workers can access federal premium tax credits alongside employer funding to secure affordable, comprehensive healthcare coverage tailored to their needs.
Level-Funded Health Plan Open Enrollment Alternative Letter
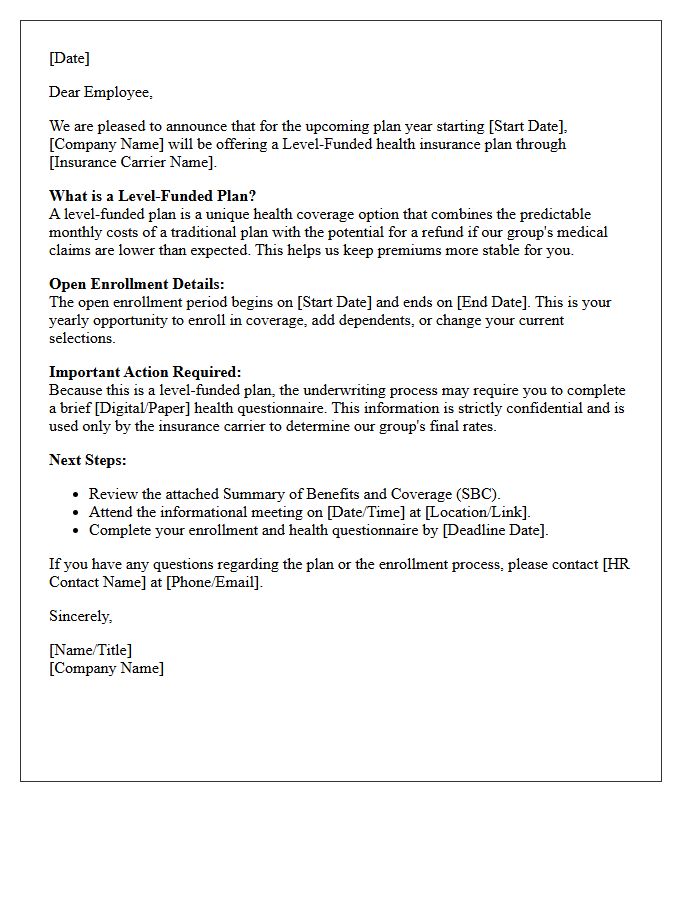
A Level-Funded Health Plan Open Enrollment Alternative Letter notifies employees about cost-effective insurance options that bypass traditional community rating. Unlike standard plans, level-funding utilizes underwriting to base premiums on the actual health of the group. This letter explains how businesses can secure predictable monthly payments while potentially receiving a surplus refund if claims remain low. It serves as a strategic alternative during renewal periods, offering greater transparency and customized coverage levels that traditional small-group markets often lack, helping employers stabilize their long-term healthcare budgets effectively.
Individual Coverage Health Reimbursement Arrangement Alternative Letter
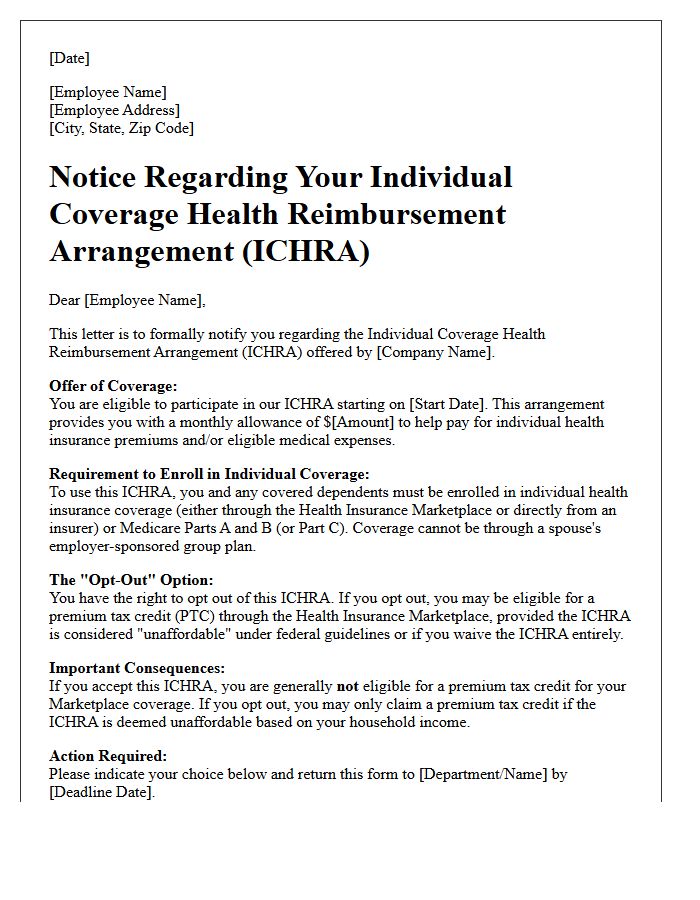
An Individual Coverage Health Reimbursement Arrangement (ICHRA) Alternative Letter is a critical document used to waive employer-sponsored coverage. Employees provide this notice to their employer to confirm they have secured individual health insurance through the marketplace instead of using company funds. This letter is essential for maintaining compliance and ensuring the employee remains eligible for Premium Tax Credits. Providing this written waiver protects the employer from mandates while allowing the individual to access personalized healthcare options outside of traditional group plans.
Off-Cycle Benefit Strategy And Alternative Open Enrollment Letter
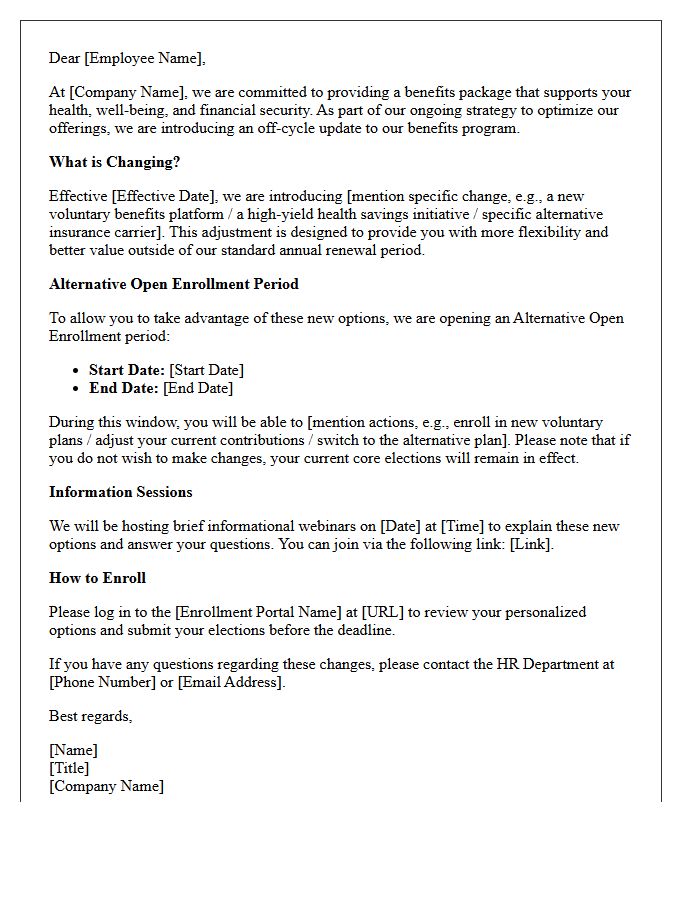
An off-cycle benefit strategy allows organizations to update insurance offerings outside the traditional calendar year, enhancing talent retention. By utilizing an alternative open enrollment letter, employers can effectively communicate these mid-year changes, ensuring employees understand new coverage options or premium adjustments. This strategic timing reduces administrative congestion and provides a competitive advantage in volatile labor markets. Proactive communication via personalized letters ensures higher engagement, helping staff make informed decisions about their healthcare and wellness benefits without the pressure of the standard year-end rush.
Qualified Small Employer Reimbursement Alternative Letter
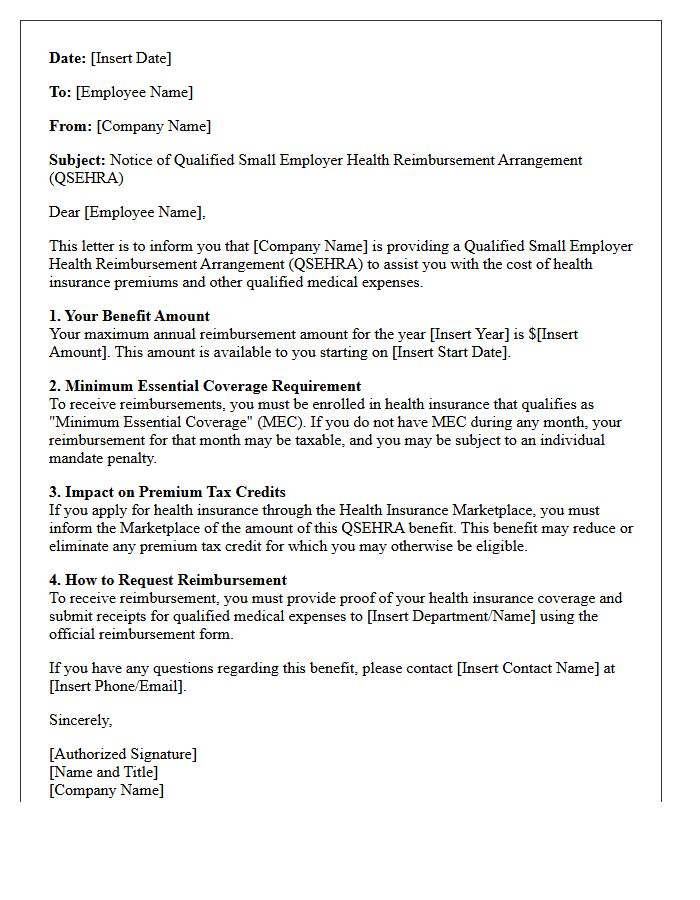
A QSEHRA notice is a mandatory legal document provided to employees at least 90 days before the start of a plan year. This letter outlines the maximum annual reimbursement amount available for healthcare premiums and qualifying medical expenses. It crucially informs staff that they must maintain Minimum Essential Coverage to receive tax-free payments. Failure to provide this notice timely can result in IRS penalties. Employees must also use this information to coordinate potential premium tax credits through the health insurance marketplace to ensure compliance with federal tax regulations.
Professional Employer Organization Benefit Alternative Letter
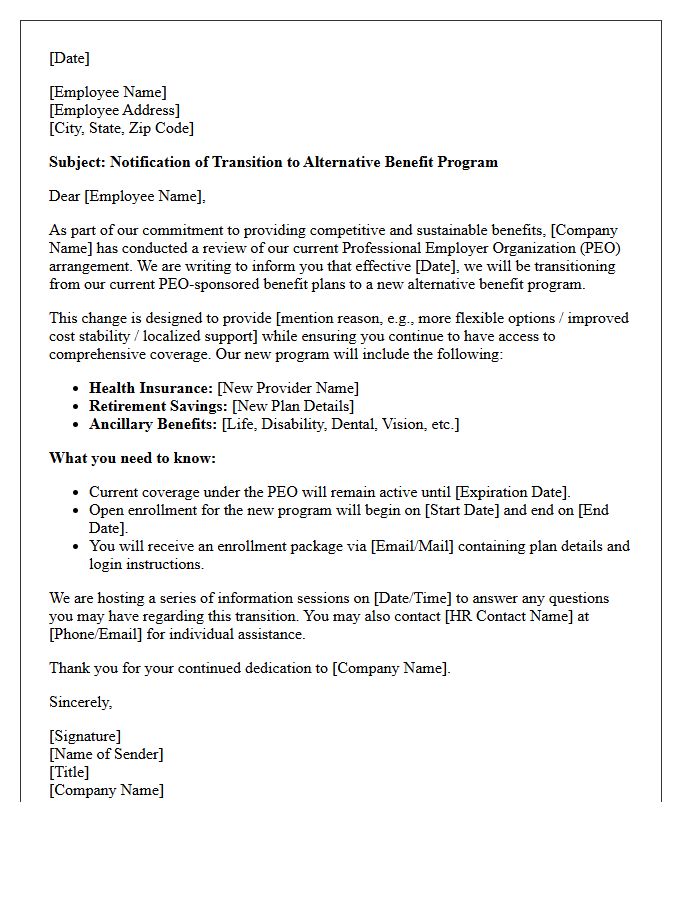
A Professional Employer Organization (PEO) Benefit Alternative Letter is a formal document used to compare private insurance markets against a PEO's bundled co-employment model. This analysis helps businesses evaluate if carving out benefits provides better cost transparency and plan flexibility. It serves as a strategic tool for brokers to demonstrate how independent employee benefit structures can potentially lower administrative overhead while maintaining high-quality coverage. Understanding this alternative is essential for companies seeking to regain control over their plan design and long-term healthcare expenditure without being tied to a PEO's rigid master policy.
Cost-Saving Healthcare Options And Alternative Open Enrollment Letter
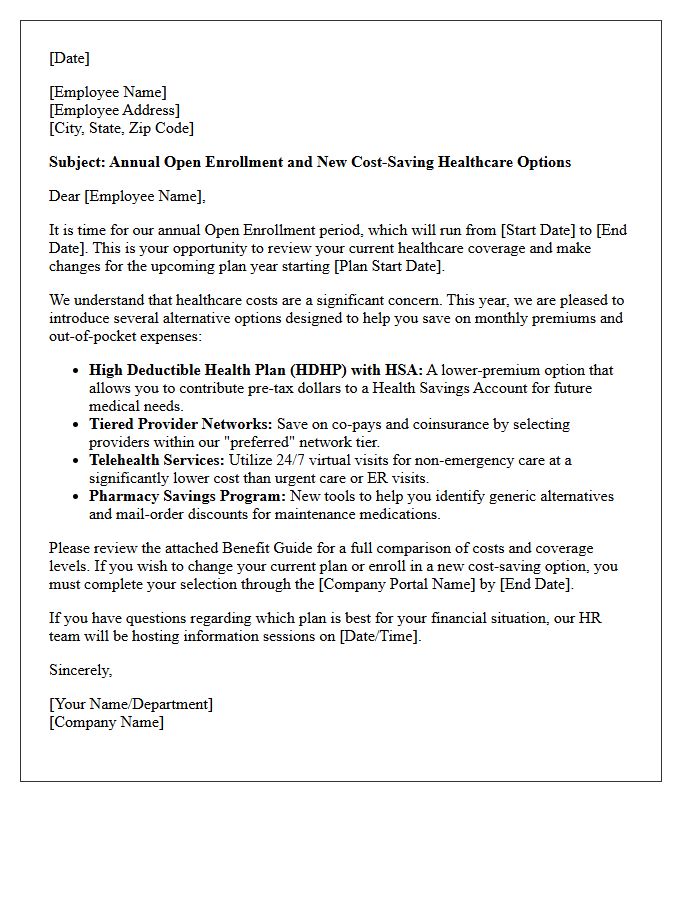
Understanding cost-saving healthcare options is essential when traditional insurance premiums rise. Your Alternative Open Enrollment Letter serves as a formal notification, detailing flexible coverage choices beyond standard marketplace plans. These alternatives often include health sharing ministries or short-term plans that provide significant financial relief. It is crucial to review these documents carefully to identify lower monthly costs and tailored benefits that fit your budget. Staying informed about these alternatives ensures you maintain quality care while maximizing your savings during the annual enrollment period.
Partial Self-Funding Open Enrollment Alternative Letter
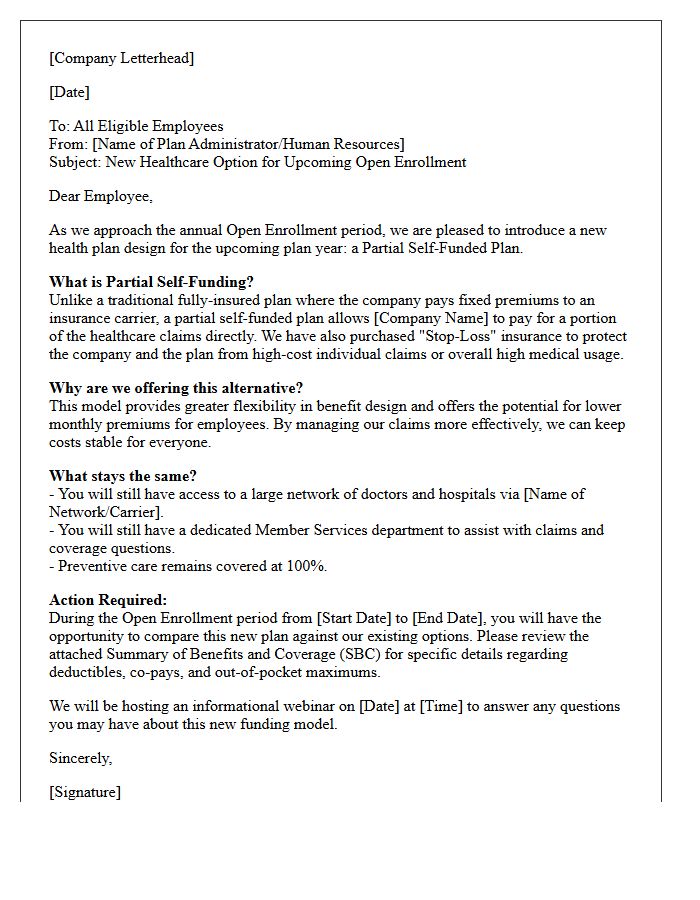
A Partial Self-Funding Open Enrollment Alternative Letter is a strategic communication sent to employees when an employer transitions from fully insured plans to a level-funded or self-insured model. This document explains how the new structure maintains current benefits while reducing premium costs and improving long-term stability. It serves as a formal notice during the enrollment period, detailing changes in plan administration, provider networks, and potential savings. Clear transparency in this letter is essential for maintaining employee trust and ensuring a smooth transition to a more flexible, data-driven healthcare strategy.
Direct Primary Care And Health Sharing Alternative Letter
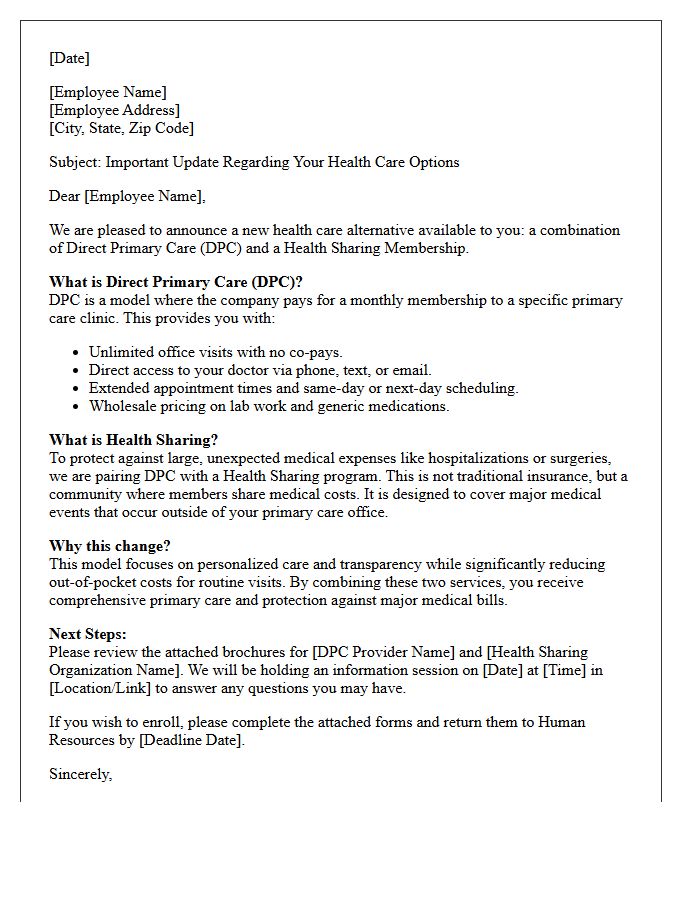
A Direct Primary Care (DPC) arrangement paired with a Health Sharing plan offers a cost-effective alternative to traditional insurance. This model provides unlimited access to a personal physician for a monthly fee, while the sharing community assists with large medical expenses. It is essential to understand that health sharing is not insurance; these programs are cooperatives where members contribute to each other's major medical needs. Combining these services ensures comprehensive everyday wellness and financial protection against emergencies without the complexity of restrictive provider networks or high premiums.
Flexible Group Benefits Open Enrollment Alternative Letter
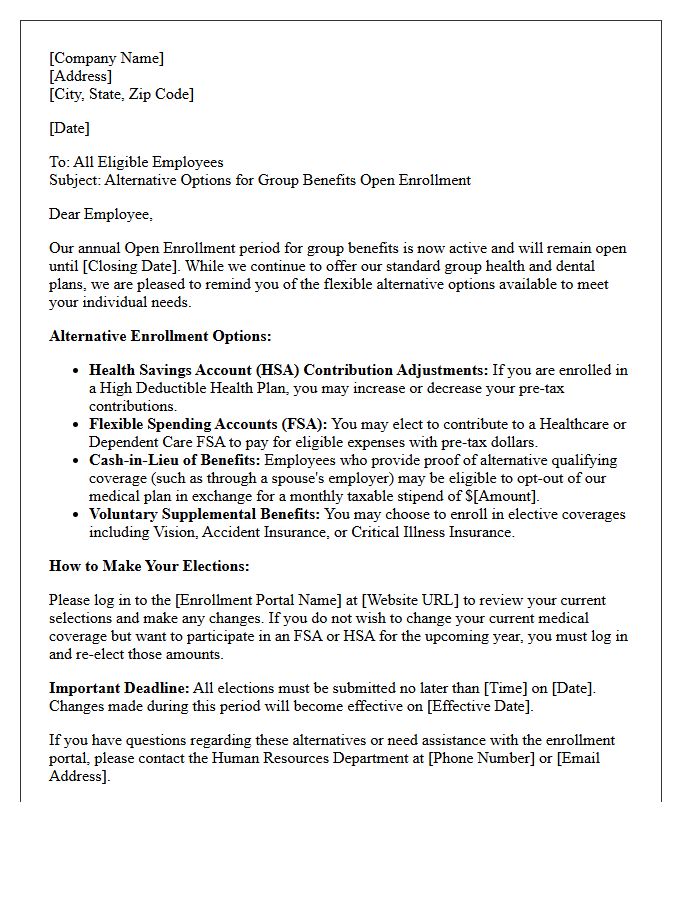
A Flexible Group Benefits Open Enrollment Alternative Letter informs employees about non-traditional coverage options when standard plans change. It serves as a formal notification detailing voluntary benefits, health savings accounts, or defined contribution models. This document is essential for maintaining compliance and ensuring staff understand their enrollment rights and deadlines. By providing clear alternatives, employers help workers make informed decisions regarding their healthcare and financial security outside of typical annual windows, effectively streamlining the benefits administration process while minimizing organizational gaps in coverage.
Early Renewal Strategy And Open Enrollment Alternative Letter
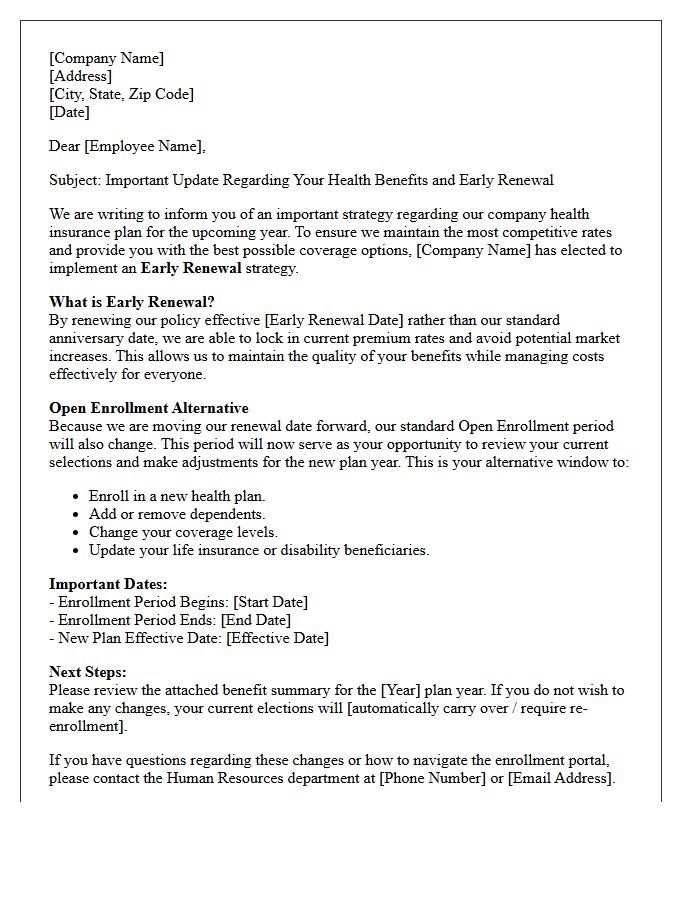
An early renewal strategy allows businesses to reset their plan year before new regulations or rate hikes take effect. This approach provides budget predictability and more control over benefit costs. Simultaneously, an open enrollment alternative letter informs employees of their options outside traditional group plans, such as individual coverage or health reimbursement arrangements. Using these tools together helps employers manage financial risk while offering staff flexible healthcare alternatives during shifting market conditions. Proactive communication ensures compliance and minimizes disruption during the transition period.
Year-Round Benefit Solutions Alternative Open Enrollment Letter
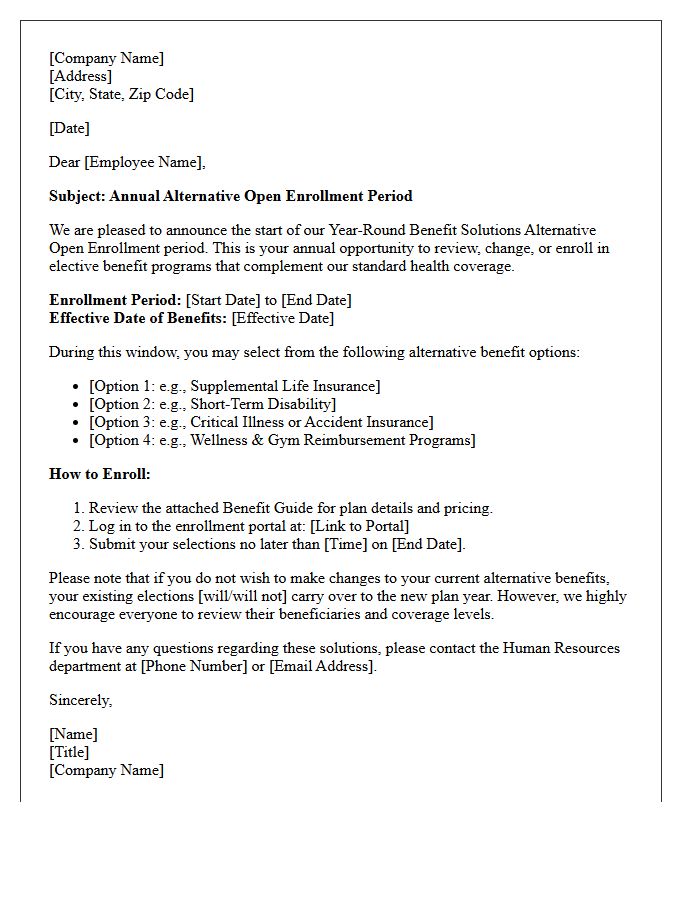
A Year-Round Benefit Solutions Alternative Open Enrollment Letter informs employees that voluntary benefits remain accessible outside the standard annual window. Unlike traditional medical plans, these supplemental insurance options-such as dental, vision, or life coverage-often allow for enrollment at any time. This communication ensures staff understand their extended eligibility and can enhance their financial protection whenever personal needs change. Utilizing this alternative letter promotes continuous engagement with workplace wellness programs, highlighting that essential coverage support is not restricted to a single yearly period.
What is a Small Business Open Enrollment Alternative Letter?
An Open Enrollment Alternative Letter is a formal notification sent to employees when a small business chooses to provide a Health Reimbursement Arrangement (HRA) or a stipend instead of a traditional group health insurance plan. It outlines how employees can purchase individual coverage and how to claim their employer-provided tax-free credits.
Is an alternative letter legally required for ICHRA or QSEHRA?
Yes, federal regulations require employers offering an Individual Coverage HRA (ICHRA) or a Qualified Small Employer HRA (QSEHRA) to provide a written notice to eligible employees at least 90 days before the beginning of the plan year. This letter ensures employees understand their rights and how the benefit affects their eligibility for premium tax credits.
How does an enrollment alternative letter affect employee tax credits?
The letter informs employees that if the HRA offer is considered "affordable" under ACA standards, they will not be eligible for premium tax credits (subsidies) on the health insurance marketplace. If the offer is unaffordable, the letter explains how employees must opt-out of the HRA to claim marketplace subsidies.
What information must be included in a small business HRA notice?
A compliant letter must include the specific dollar amount of the monthly contribution, the date the benefit becomes available, a description of the "Special Enrollment Period" it triggers, and a warning that the employee must coordinate the benefit with the health insurance exchange.
Can employees use an alternative letter to sign up for health insurance mid-year?
Yes. Providing an Open Enrollment Alternative Letter to an employee for a new HRA triggers a "Qualifying Life Event." This allows the employee to enroll in an individual health insurance plan through the marketplace outside of the standard annual open enrollment window via a 60-day Special Enrollment Period.
Comments