Writing a Short Sale Hardship Letter is a critical step in proving to your lender that financial distress prevents you from meeting mortgage obligations. This document explains your circumstances, such as job loss or medical crises, to justify a property sale for less than the balance owed. To help you draft a compelling case, below are some ready to use template.
Image cover: Proven Hardship Letter Templates and Samples for Successful Short Sales
Letter Samples List
- Unemployment Hardship Short Sale Assistance Letter
- Medical Emergency Financial Hardship Letter
- Divorce or Separation Short Sale Hardship Letter
- Mandatory Job Relocation Hardship Assistance Letter
- Death of a Spouse Mortgage Hardship Letter
- Reduced Income and Wage Cut Hardship Letter
- Unexpected Business Failure Short Sale Letter
- Active Duty Military Deployment Hardship Letter
- Adjustable Rate Mortgage Payment Increase Hardship Letter
- Natural Disaster Property Damage Assistance Letter
- Severe Illness and Disability Short Sale Letter
- Bankruptcy Filing Real Estate Hardship Letter
Unemployment Hardship Short Sale Assistance Letter
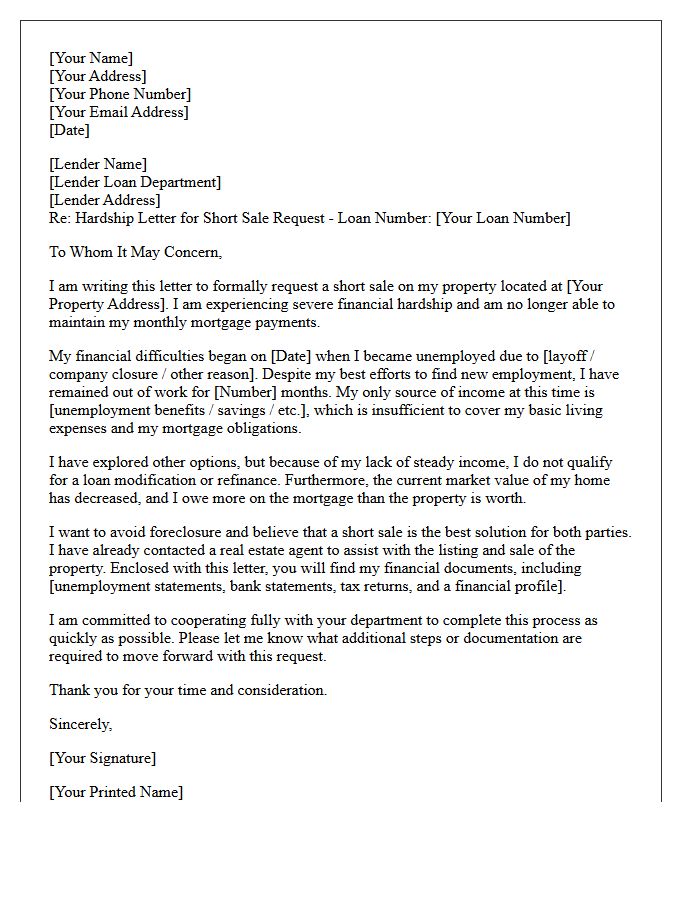
An Unemployment Hardship Short Sale Assistance Letter is a formal document explaining how job loss prevents you from meeting mortgage obligations. To be effective, the letter must clearly outline your financial insolvency and demonstrate that the hardship is permanent or long-term. Lenders require this hardship letter to consider approving a short sale, allowing you to sell the property for less than the remaining balance. Focus on providing specific dates of unemployment and attaching supporting evidence to justify the deficiency waiver request and avoid foreclosure proceedings.
Medical Emergency Financial Hardship Letter
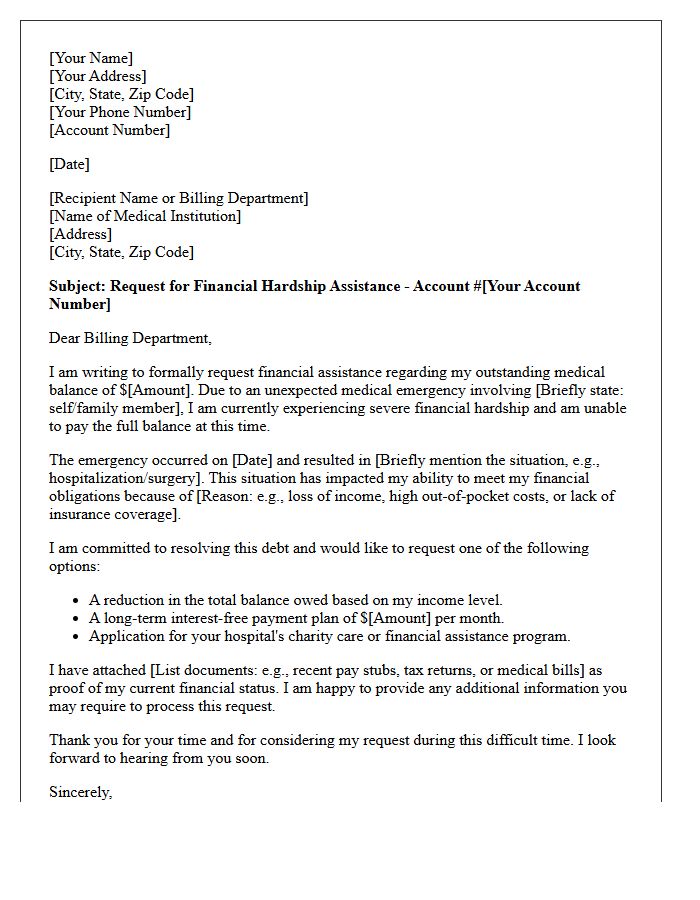
A Medical Emergency Financial Hardship Letter is a formal request sent to healthcare providers or billing departments to negotiate debt reduction or payment plans. It must clearly document your inability to pay due to unexpected illness, injury, or loss of income. To be effective, include specific details about your diagnosis, total balance, and a realistic settlement offer. Attaching financial evidence, such as bank statements or tax returns, strengthens your case for a waiver or charity care, helping prevent medical debt from affecting your credit score.
Divorce or Separation Short Sale Hardship Letter
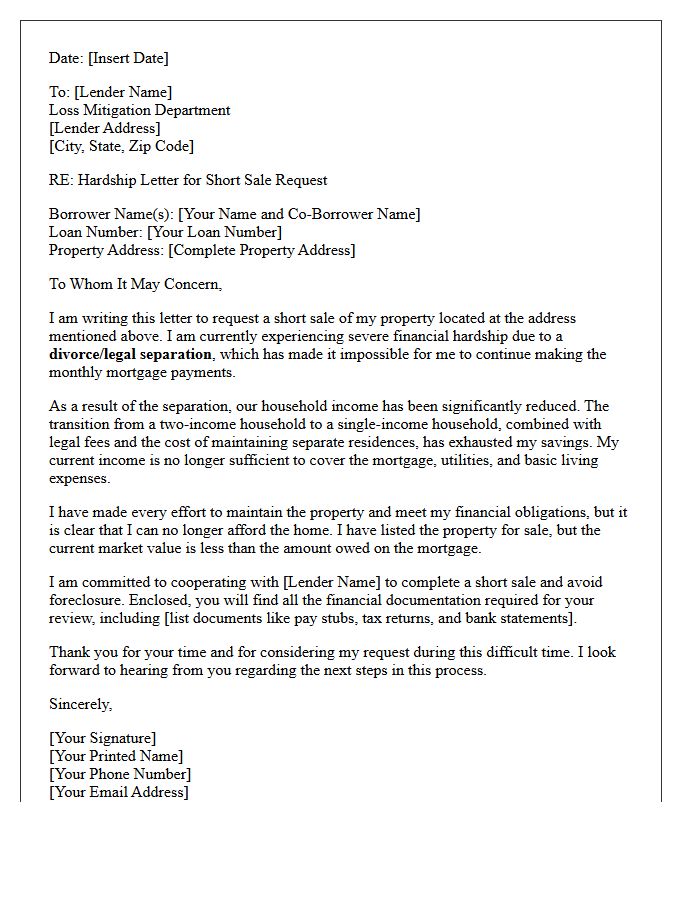
When writing a hardship letter for a short sale due to divorce or separation, clarity is essential. You must explicitly state how the legal dissolution of the relationship has caused a permanent financial shortfall. Lenders need documented proof, such as a divorce decree or separation agreement, to verify that the household income can no longer support the mortgage payments. Focus on the inability to maintain the property under new living arrangements. This professional explanation is the key to demonstrating that a short sale is a necessary resolution for your financial situation.
Mandatory Job Relocation Hardship Assistance Letter
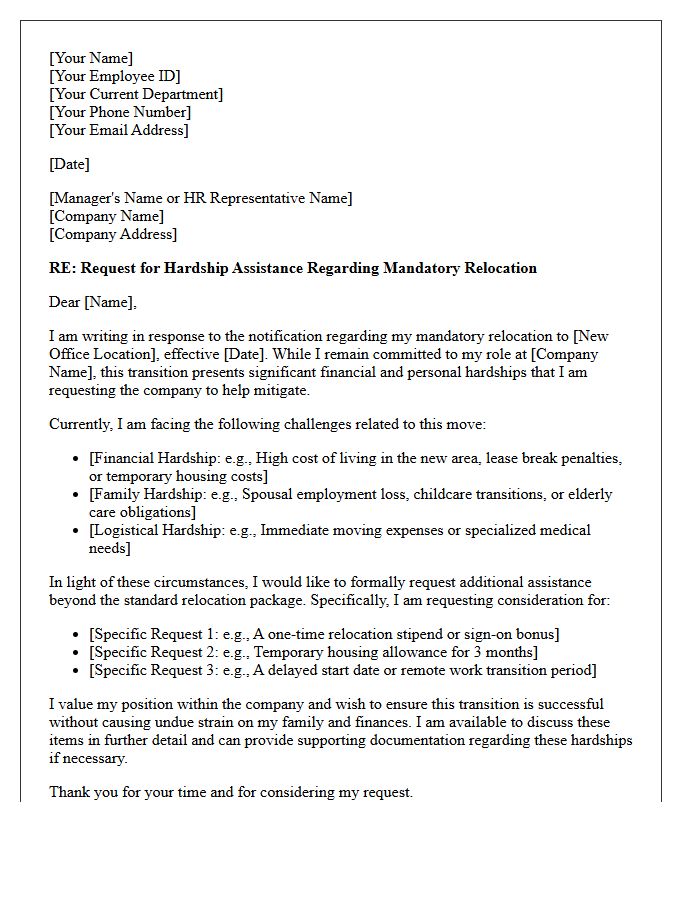
A Mandatory Job Relocation Hardship Assistance Letter is a formal request for support when an employer requires a move that causes financial or personal strain. It should clearly outline specific extenuating circumstances, such as family obligations, medical needs, or significant costs. The goal is to negotiate a relocation package or a policy exception. To be effective, provide evidence of potential hardships and propose solutions, such as extended deadlines or additional stipends. Professionalism is key to securing assistance while maintaining your career standing during a forced transition.
Death of a Spouse Mortgage Hardship Letter
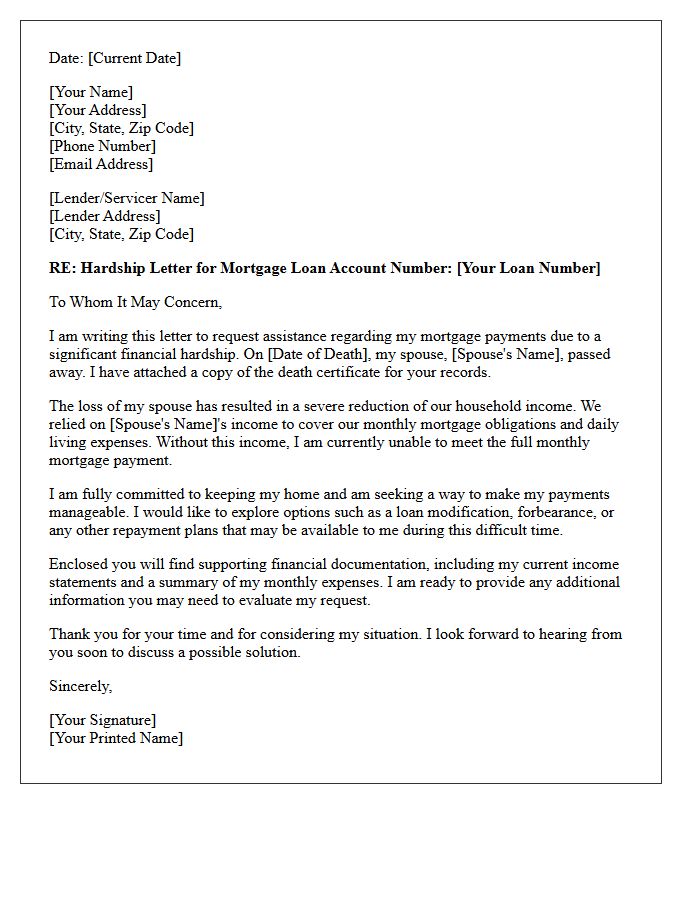
A death of a spouse mortgage hardship letter is a formal request for loan modification or forbearance following a partner's passing. To ensure foreclosure prevention, clearly state your financial change, provide the date of death, and include a certified death certificate. Focus on how the loss of income impacts your ability to make monthly payments. Being transparent about your financial hardship helps lenders evaluate options like payment reductions or term extensions, allowing you to maintain homeownership during a difficult transition. Prompt communication with your mortgage servicer is essential.
Reduced Income and Wage Cut Hardship Letter
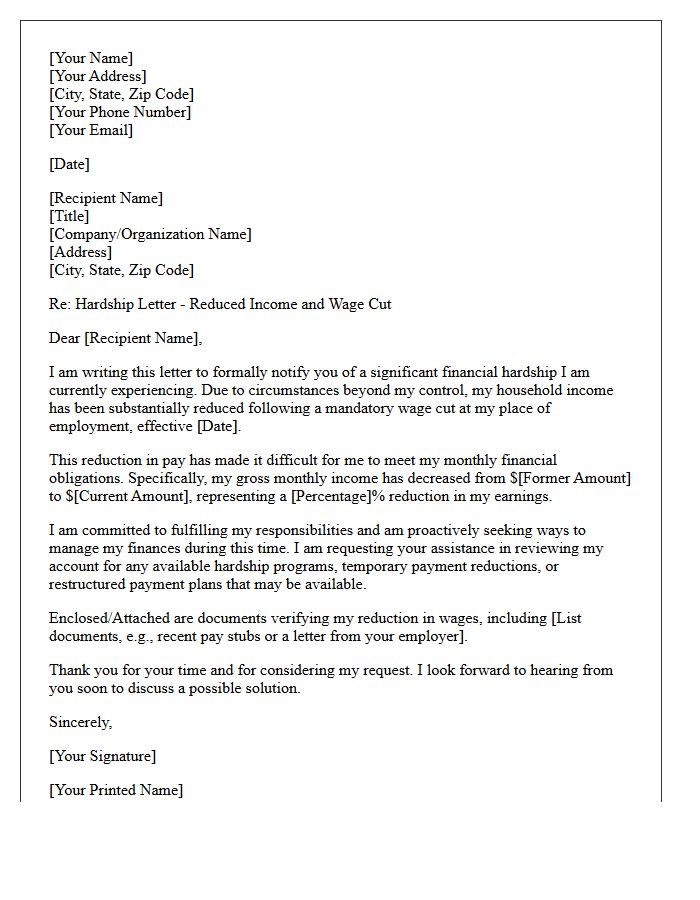
A hardship letter for reduced income or a wage cut is a formal request for financial relief. Clearly state the reason for your salary reduction, such as company layoffs, reduced hours, or economic downturn. Provide specific figures comparing your previous and current earnings. Attach pay stubs or an employer letter as evidence. Be concise, professional, and propose a realistic repayment plan or temporary loan modification. Demonstrating a proactive willingness to meet obligations despite financial setbacks increases the likelihood that lenders or creditors will approve your request for assistance.
Unexpected Business Failure Short Sale Letter
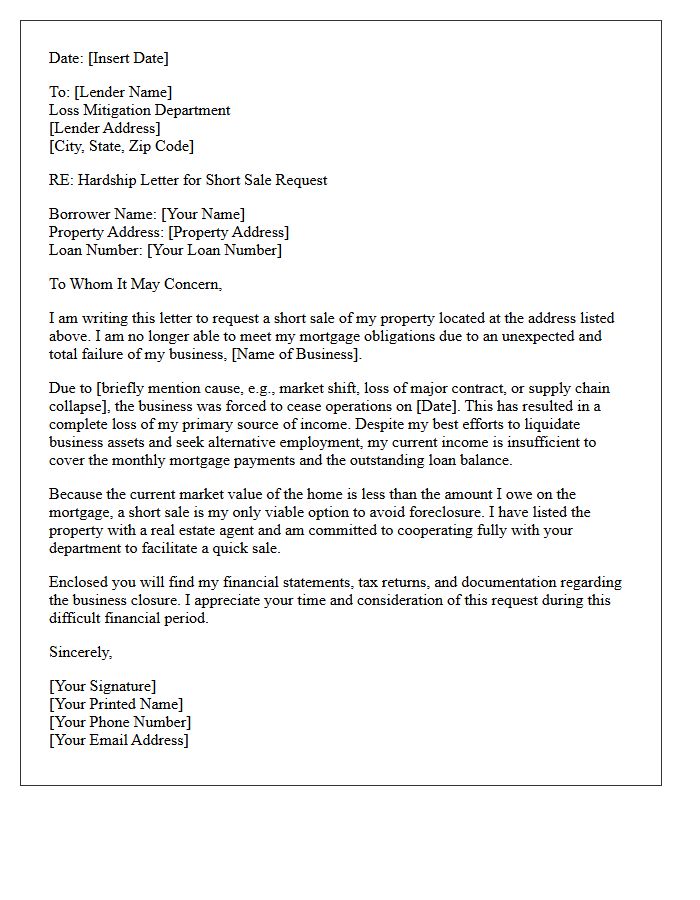
An unexpected business failure short sale letter is a critical hardship letter used to justify why a borrower can no longer meet mortgage obligations. It must clearly explain the financial insolvency caused by the company's collapse, providing specific details on the loss of income. To be effective, include supporting evidence like tax returns or closure notices. This document persuades lenders to accept a short sale, mitigating the impact of debt by proving the situation is both involuntary and permanent.
Active Duty Military Deployment Hardship Letter
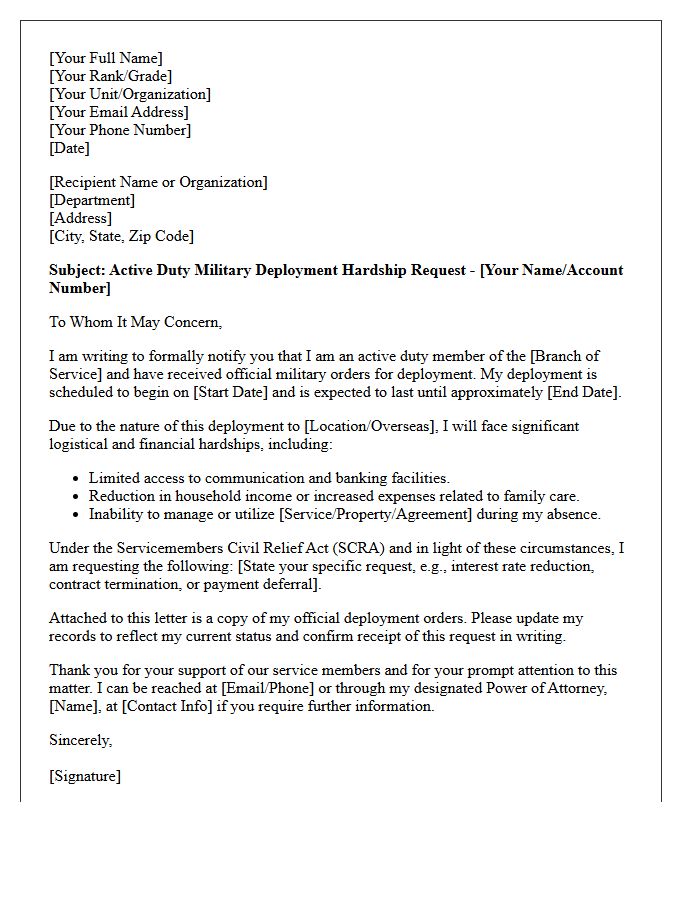
An Active Duty Military Deployment Hardship Letter is a formal request for financial or contractual relief due to service-related obligations. To ensure effectiveness, clearly document how deployment creates specific financial strain or prevents personal management of affairs. Attach official deployment orders as verification to support your case. Under the Servicemembers Civil Relief Act (SCRA), this letter helps terminate leases, lower interest rates, or pause obligations. Keep the tone professional, concise, and focused on the unforeseeable challenges arising from your military service to secure necessary accommodations.
Adjustable Rate Mortgage Payment Increase Hardship Letter
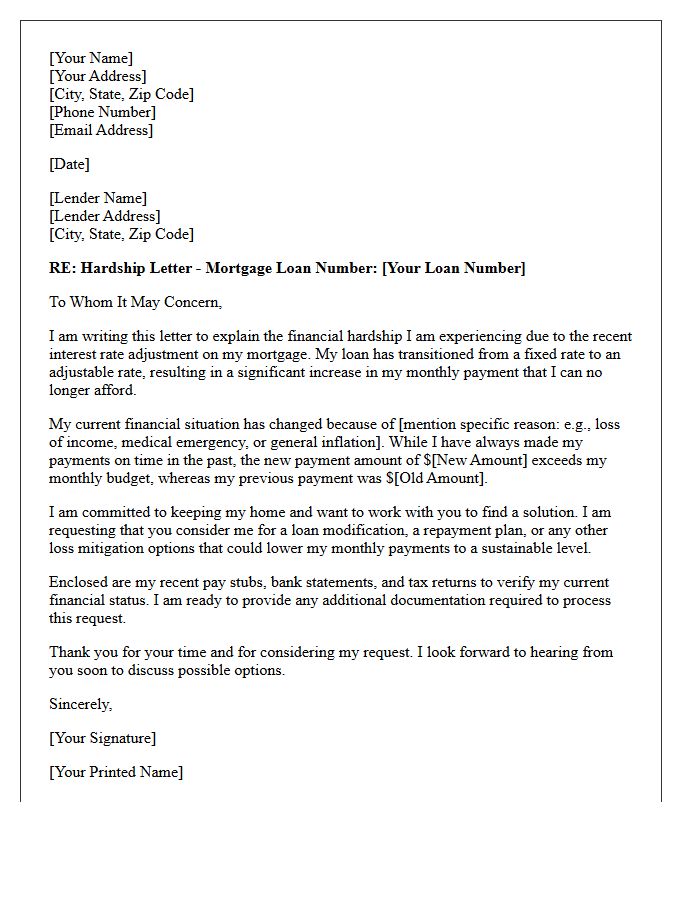
An Adjustable Rate Mortgage (ARM) hardship letter is a formal request for loan modification when rising interest rates cause financial distress. To be effective, clearly document your specific financial hardship-such as job loss or medical expenses-that makes the new monthly payment unaffordable. Provide a detailed budget analysis and evidence of your income to prove you can sustain a modified plan. Focusing on your commitment to homeownership and providing a clear call to action helps lenders understand why a permanent rate adjustment or fixed-term conversion is necessary to prevent foreclosure.
Natural Disaster Property Damage Assistance Letter
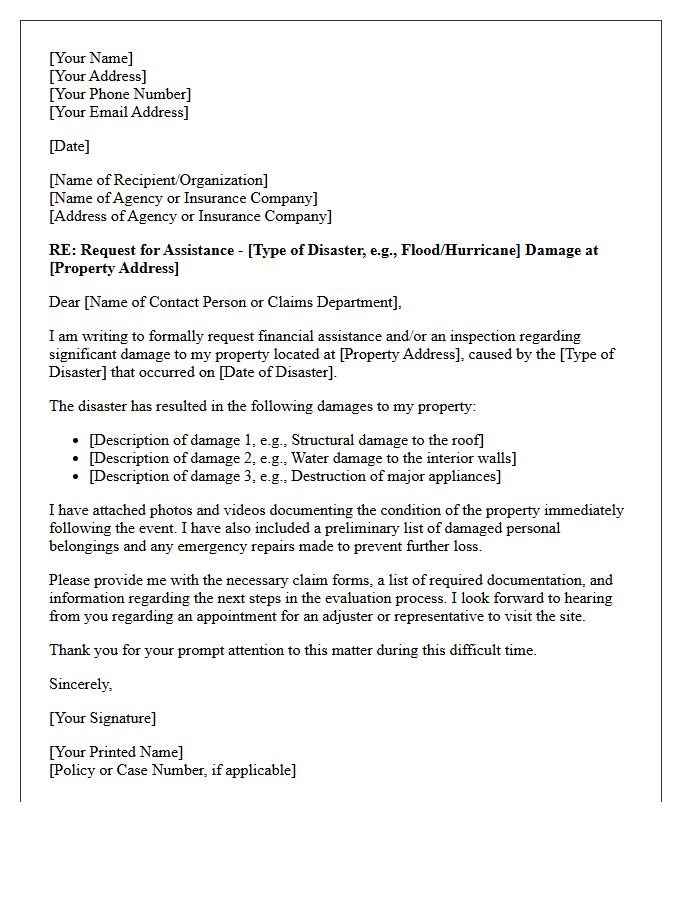
A Natural Disaster Property Damage Assistance Letter is a formal request sent to insurance providers or government agencies to initiate claims. It must clearly document the date of the event, a detailed list of structural damages, and include photographic evidence. Using precise language helps expedite financial recovery and ensures you receive the maximum reimbursement allowed. Always include your policy number and current contact information to prevent delays. Timely submission is critical to meeting strict filing deadlines and securing essential funds for property repairs and stabilization after a catastrophic event.
Severe Illness and Disability Short Sale Letter
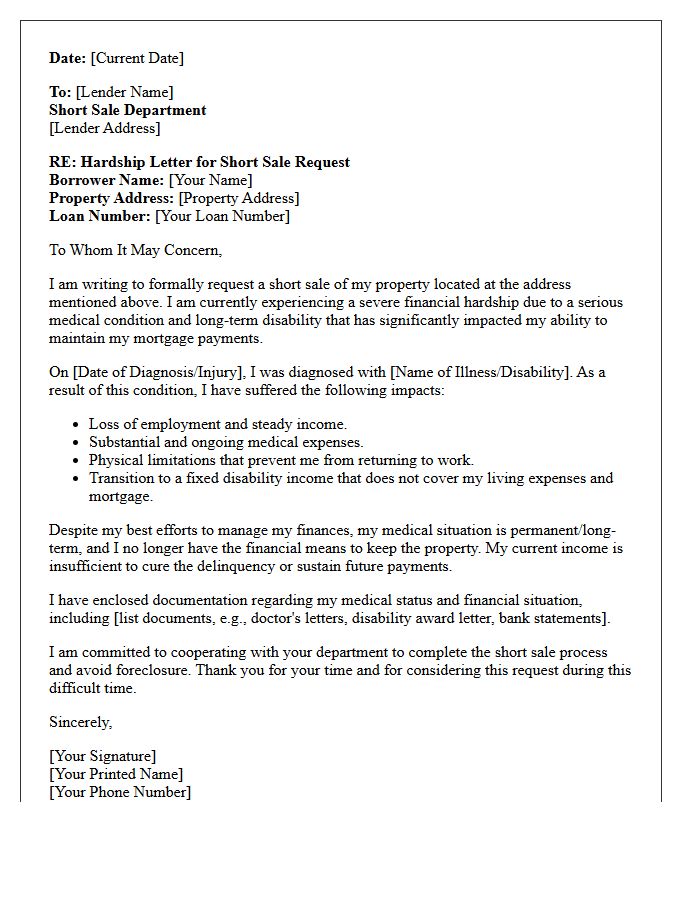
A Severe Illness and Disability Short Sale Letter is a critical hardship letter sent to mortgage lenders to justify a property sale for less than the owed balance. It must clearly document how a medical crisis has compromised the homeowner's ability to maintain payments. By providing clinical evidence and financial proof, this letter persuades the bank to accept a short sale as a pragmatic alternative to foreclosure. Including specific details about long-term disability or treatment costs demonstrates that the financial hardship is permanent, making the lender more likely to approve the settlement.
Bankruptcy Filing Real Estate Hardship Letter
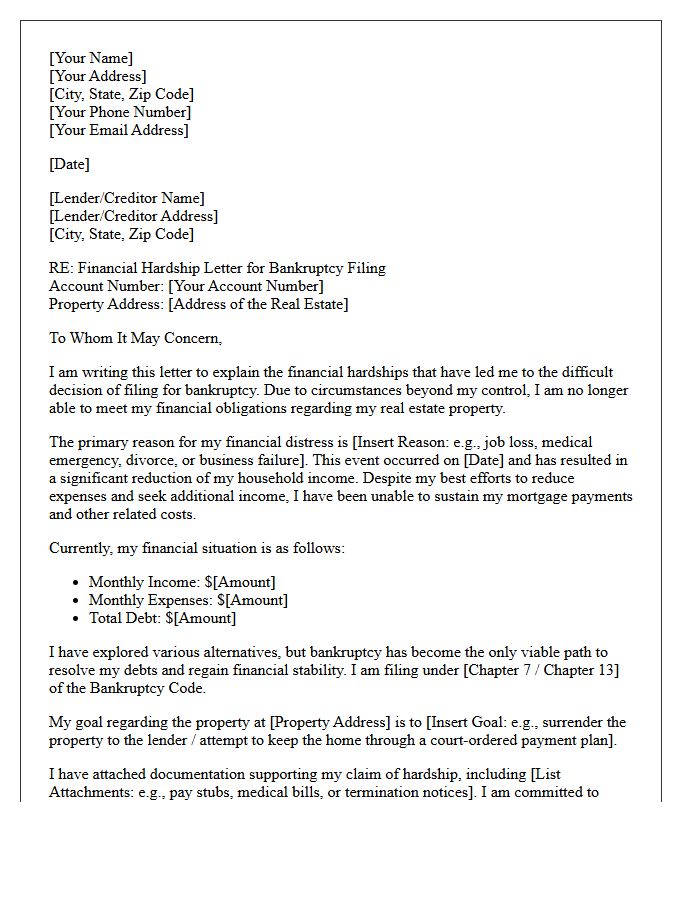
A bankruptcy hardship letter is a critical document explaining the financial insolvency leading to your filing. For real estate, it must clearly detail extenuating circumstances like job loss, medical crises, or divorce that prevent mortgage payments. To be effective, provide a concise, honest narrative supported by evidence. Lenders and courts use this sworn statement to assess your sincerity and eligibility for debt restructuring. Demonstrating a proactive intent to resolve delinquent obligations can significantly influence the outcome of your bankruptcy case and potential property retention strategies.
What is a short sale hardship assistance letter?
A short sale hardship assistance letter is a formal document written by a homeowner to their mortgage lender explaining the financial difficulties that prevent them from making mortgage payments. This letter serves as the core justification for requesting a short sale, where the lender agrees to accept less than the total balance owed on the loan.
What types of financial hardships qualify for a short sale?
Lenders typically recognize several "involuntary" hardships for short sale approval, including job loss or significant income reduction, divorce or legal separation, medical emergencies and mounting bills, mandatory job relocation, or the death of a primary wage earner. The letter must clearly demonstrate that the financial situation is permanent or long-term.
How do I structure a short sale hardship letter for the best results?
To optimize for lender approval, the letter should be concise (one page) and include your loan number, a clear explanation of what caused the financial distress, when the hardship began, and a statement confirming that you have no other assets to pay the deficiency. It should conclude with a direct request for a short sale as the only viable alternative to foreclosure.
What documentation should accompany my hardship letter?
A hardship letter is most effective when supported by a full financial package. This usually includes the last two years of tax returns, recent W-2s, the last two months of bank statements, a detailed monthly expense budget, and evidence of the hardship itself, such as medical bills, a layoff notice, or a divorce decree.
Can a short sale hardship letter be denied by the lender?
Yes, a lender may deny the request if the hardship is deemed "strategic" or voluntary, if the homeowner has significant liquid assets (cash in savings/investments) that could cover the mortgage, or if the financial documentation does not match the claims made in the letter. Accuracy and honesty are critical for passing the lender's underwater mortgage review.

Comments