An Appraisal Shortfall Solution Letter is a formal proposal sent to a seller when a home valuation comes in lower than the agreed purchase price. This document outlines strategic options like price renegotiation, increased down payments, or gap coverage to keep the real estate deal on track. To help you navigate this challenge, below are some ready to use template.
Image cover: Bridging the Gap: Appraisal Shortfall Resolution Letter Templates
Letter Samples List
- Appraisal Rebuttal and Reconsideration of Value Letter
- Seller Price Reduction Request Letter Due to Appraisal Shortfall
- Buyer Appraisal Gap Coverage Commitment Letter
- Mutual Compromise and Purchase Price Renegotiation Letter
- Second Appraisal Request and Justification Letter
- Contract Termination Due to Appraisal Shortfall Letter
- Seller Concession Request for Appraisal Shortfall Letter
- Alternative Financing Notification Letter for Appraisal Gap
- Seller Financing Proposal Letter for Appraisal Gap
- Split the Difference Appraisal Shortfall Agreement Letter
- Comparable Sales Submission Letter for Appraisal Review
- Earnest Money Release Letter Following Appraisal Shortfall
Appraisal Rebuttal and Reconsideration of Value Letter
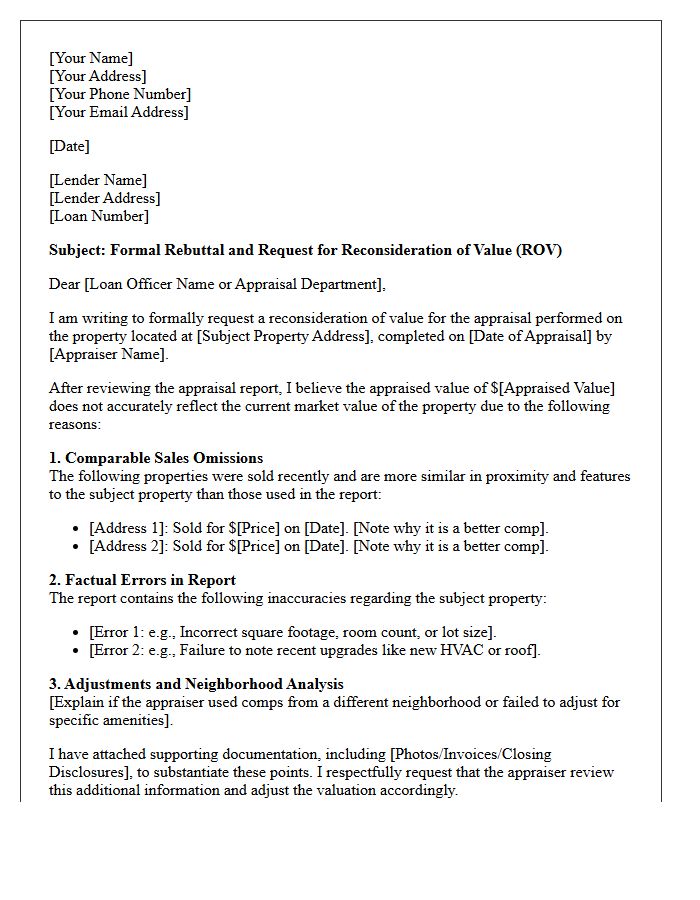
An Appraisal Rebuttal, or Reconsideration of Value (ROV), is a formal request to challenge a low home valuation. To be successful, the letter must provide factual evidence of inaccuracies in the original report, such as incorrect square footage or overlooked features. It should also include comparable sales (comps) that are more recent or geographically relevant than those used by the appraiser. This process ensures the property reflects its true market value, which is critical for securing mortgage approval and finalizing real estate transactions without unexpected funding gaps.
Seller Price Reduction Request Letter Due to Appraisal Shortfall
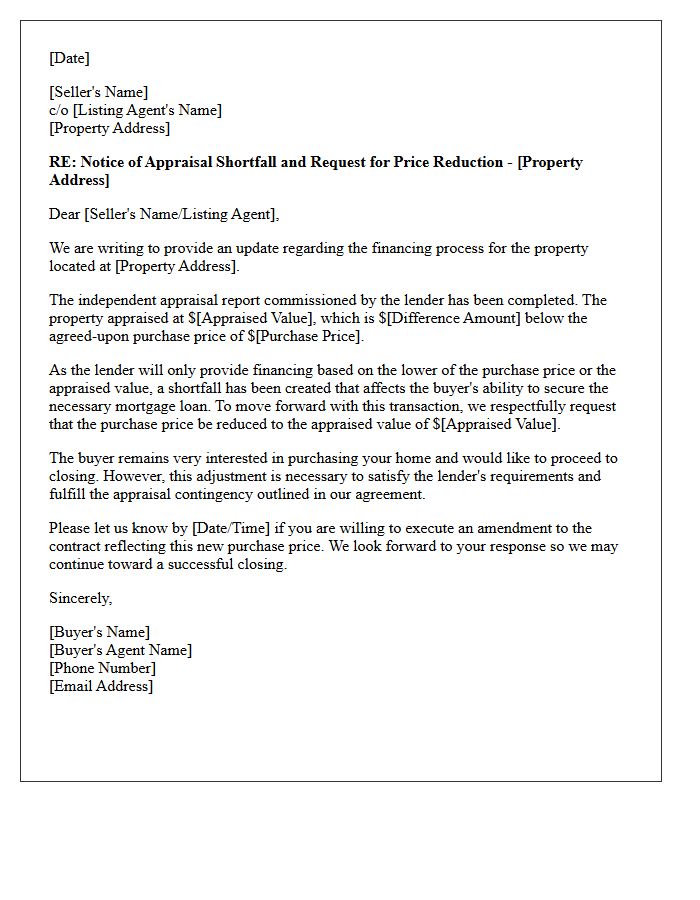
A seller price reduction request letter is a critical negotiation tool when a home appraisal comes in lower than the agreed purchase price. This document informs the seller of the appraisal shortfall, which often creates a financing gap for the buyer's mortgage. The letter professionally requests a price adjustment to match the fair market value, preventing the deal from collapsing. By highlighting the risk of future low appraisals from other lenders, it encourages the seller to lower their asking price to ensure a successful real estate closing.
Buyer Appraisal Gap Coverage Commitment Letter
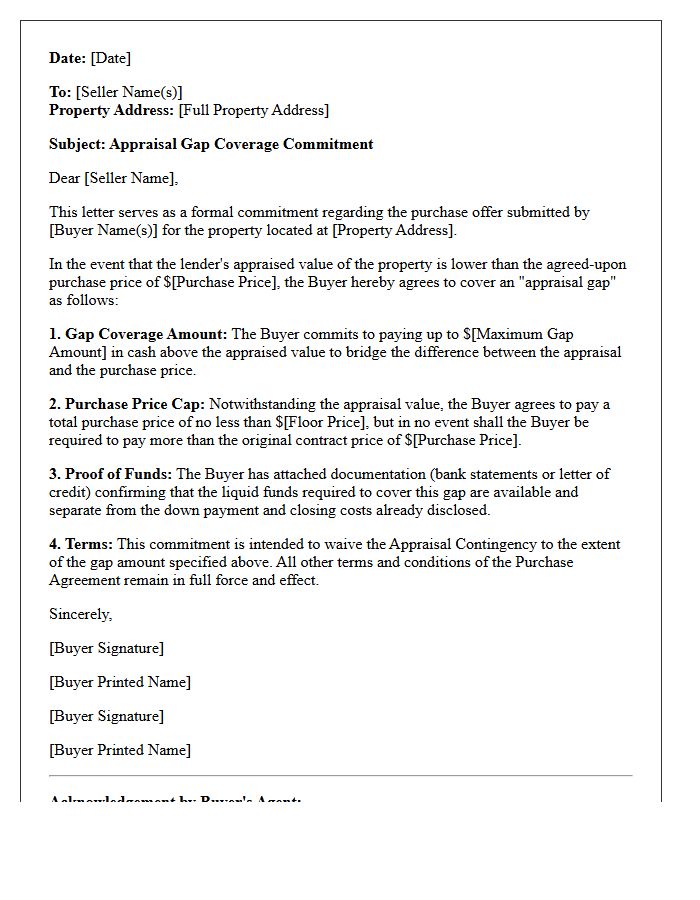
A Buyer Appraisal Gap Coverage Commitment Letter is a critical document used in competitive real estate markets. It serves as a legal guarantee that the purchaser will pay the difference out-of-pocket if the property's appraised value falls below the agreed purchase price. This commitment strengthens an offer by providing the seller financial security, ensuring the deal won't collapse due to a valuation shortfall. It proves the buyer has the liquid funds necessary to cover the discrepancy, making their bid significantly more attractive to sellers.
Mutual Compromise and Purchase Price Renegotiation Letter
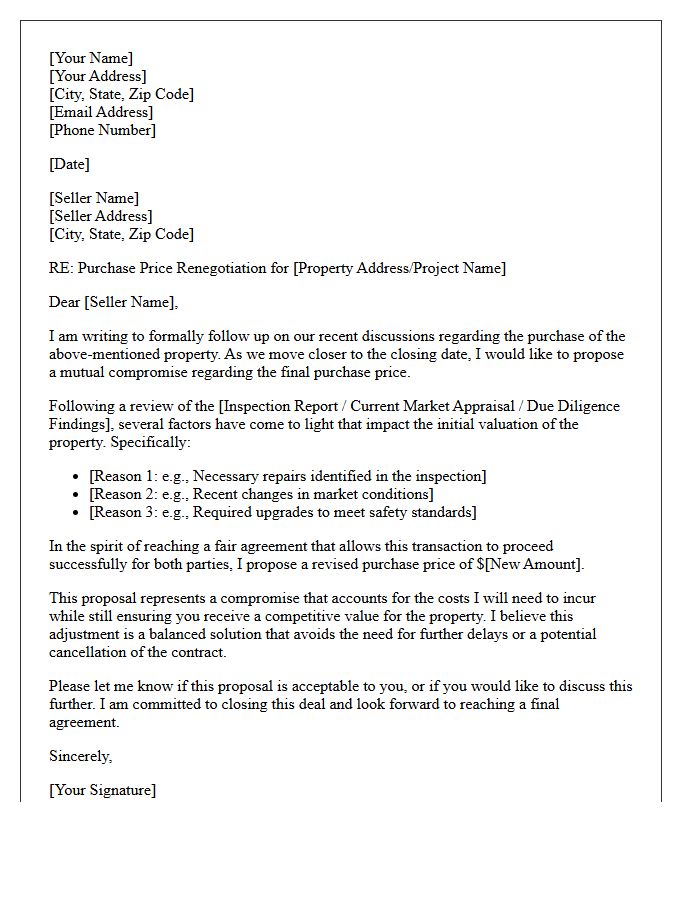
A Mutual Compromise and Purchase Price Renegotiation Letter is a formal document used to adjust a property's sale price following a home inspection or appraisal. It outlines specific defects or valuation gaps that justify a lower cost. Both parties must sign this amendment to make the new terms legally binding within the real estate contract. Effective communication via this letter helps avoid transaction failure by finding a financial middle ground that satisfies both the buyer's budget and the seller's closing goals.
Second Appraisal Request and Justification Letter
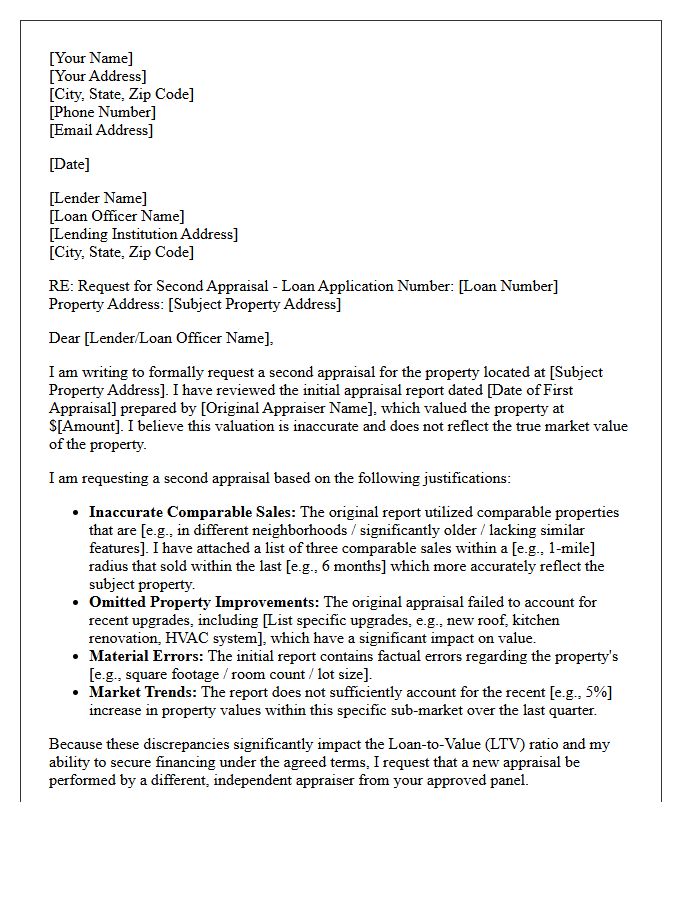
A Second Appraisal Request is a formal appeal used when a property valuation is inaccurate. To succeed, you must provide a Justification Letter highlighting objective errors, such as incorrect square footage or omitted comparable sales. Borrowers cannot request a new appraisal simply due to a low value; instead, they must prove material deficiencies or bias in the original report. Lenders review these requests to ensure the collateral value aligns with market realities, protecting both the buyer and the financial institution during the mortgage process.
Contract Termination Due to Appraisal Shortfall Letter
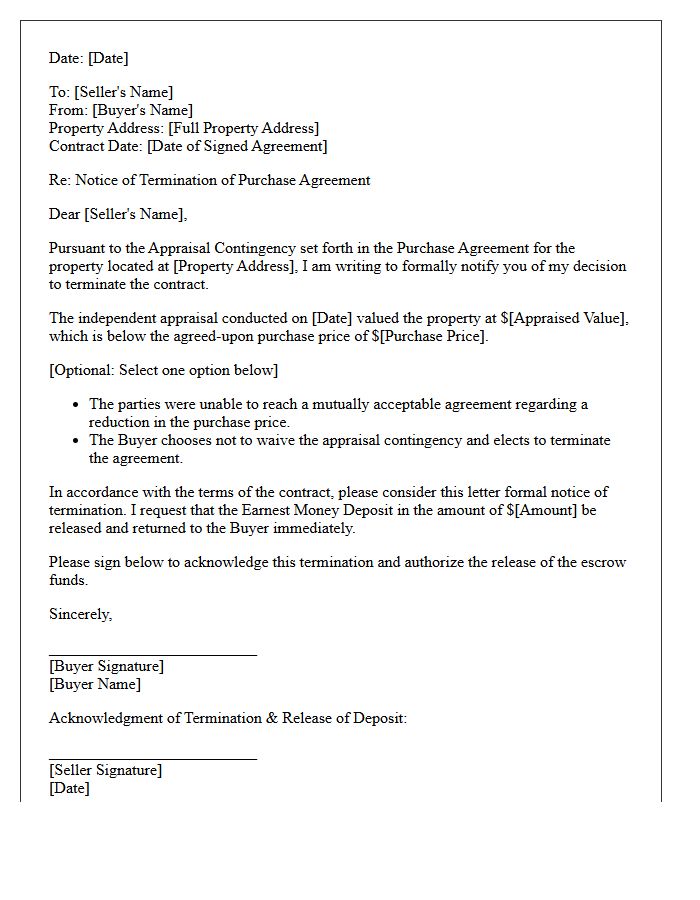
A Contract Termination Due to Appraisal Shortfall Letter is a formal notice used by buyers to cancel a real estate purchase when the property's appraised value is lower than the agreed price. This document is essential when an appraisal contingency exists, allowing the buyer to withdraw legally without losing their earnest money deposit. It serves as official proof that the valuation gap could not be resolved through price renegotiation or additional funding, ensuring a transparent contract cancellation process between all parties involved in the transaction.
Seller Concession Request for Appraisal Shortfall Letter
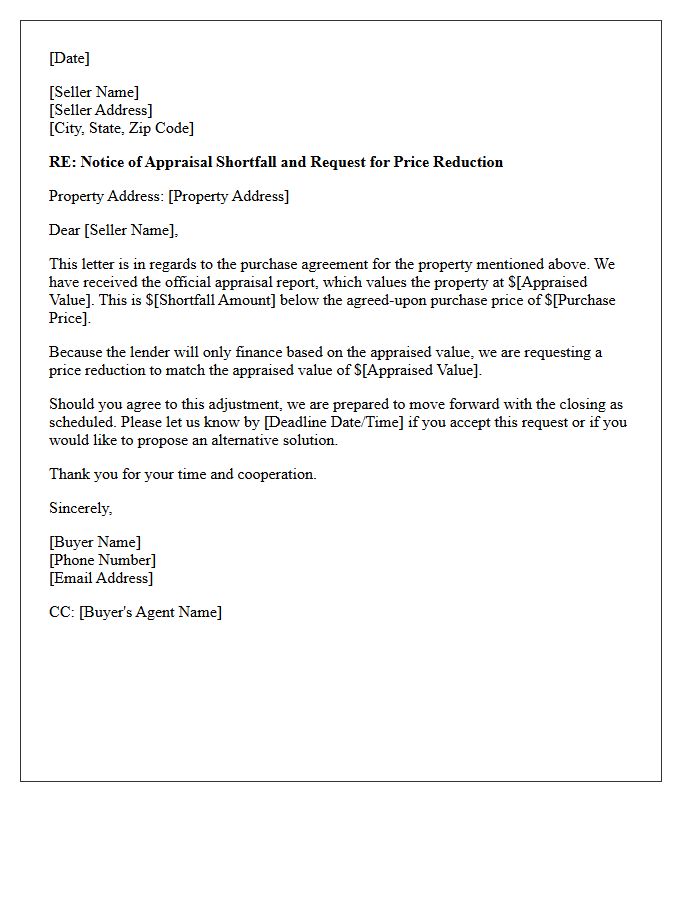
A seller concession request for an appraisal shortfall letter is a formal proposal used when a property's appraised value is lower than the agreed purchase price. It asks the seller to cover the valuation gap by reducing the sale price or offering financial credits. This document is essential for securing financing, as lenders only fund based on the appraised amount. A well-drafted letter emphasizes market data and buyer commitment to negotiate a compromise, preventing the real estate transaction from collapsing due to insufficient loan coverage or lack of personal funds.
Alternative Financing Notification Letter for Appraisal Gap
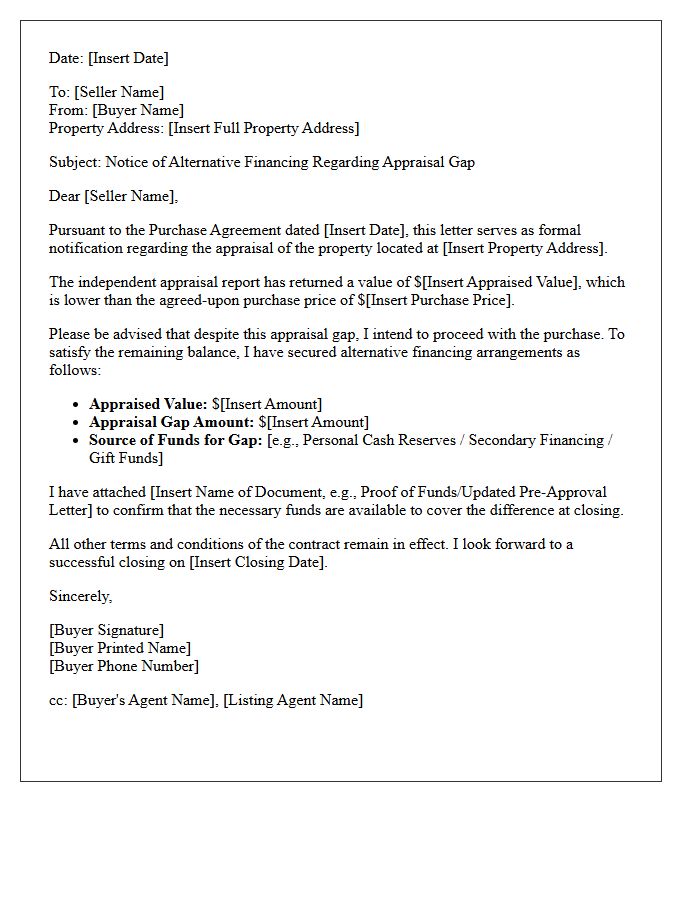
An Alternative Financing Notification Letter is a formal document issued when a property's valuation falls below the purchase price. It informs the seller that the buyer will utilize alternative funding sources-such as a larger down payment or a different loan product-to cover the appraisal gap. This letter ensures the transaction remains viable by confirming the buyer's financial ability to bridge the deficit. Providing this notice promptly is essential to maintain contractual compliance and reassure the seller that the closing will proceed despite the lower appraisal value.
Seller Financing Proposal Letter for Appraisal Gap
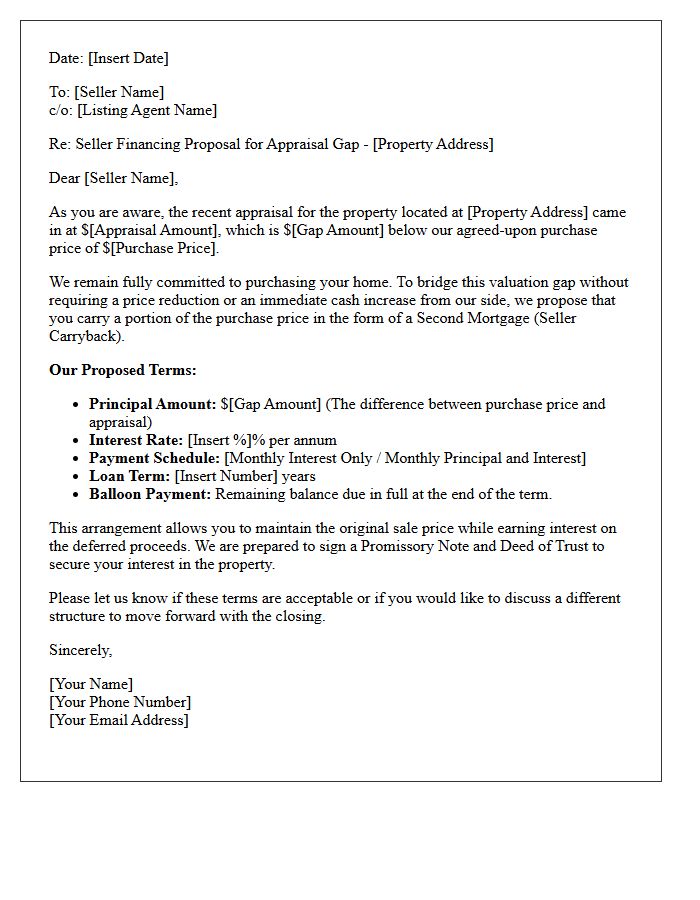
A seller financing proposal letter for an appraisal gap offers a strategic solution when a property's value falls below the purchase price. Instead of requesting a price reduction, the buyer proposes a promissory note to cover the shortfall. This arrangement allows the seller to maintain their desired exit price while the buyer avoids immediate out-of-pocket costs. Key elements include the interest rate, repayment schedule, and maturity date. Clear communication ensures the seller understands how this debt instrument secures the transaction and bridges the financing bridge effectively.
Split the Difference Appraisal Shortfall Agreement Letter
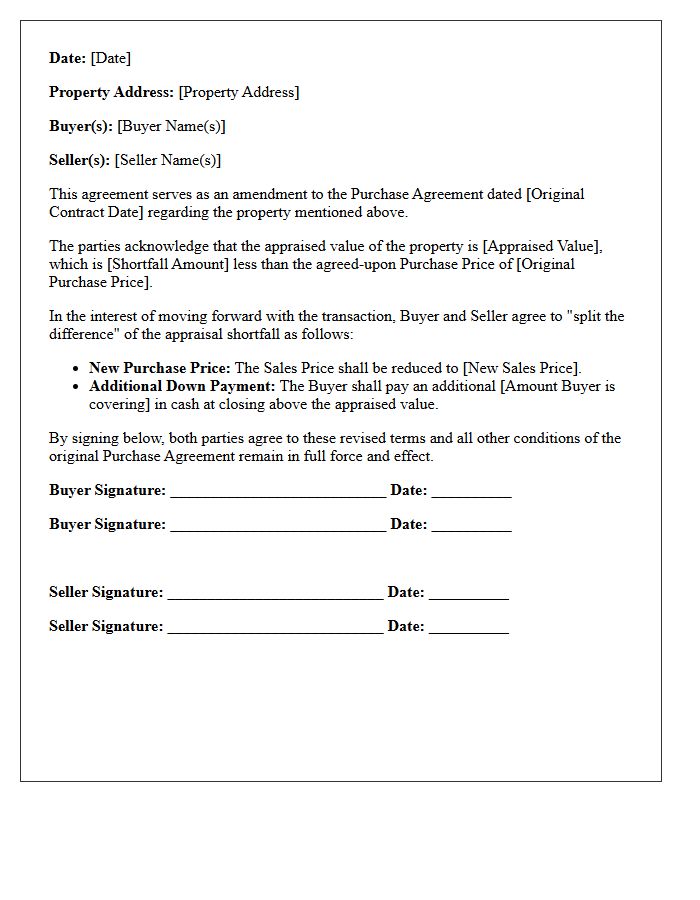
A Split the Difference Appraisal Shortfall Agreement Letter is a legal contract used when a property's appraised value is lower than the purchase price. It establishes a compromise where the buyer and seller share the financial gap. Instead of the buyer covering the entire shortfall or the seller lowering the price fully, both parties agree to contribute specific amounts to ensure the real estate closing proceeds. This document protects both parties by clearly defining the adjusted sale price and additional cash requirements, preventing the deal from collapsing due to financing limitations.
Comparable Sales Submission Letter for Appraisal Review
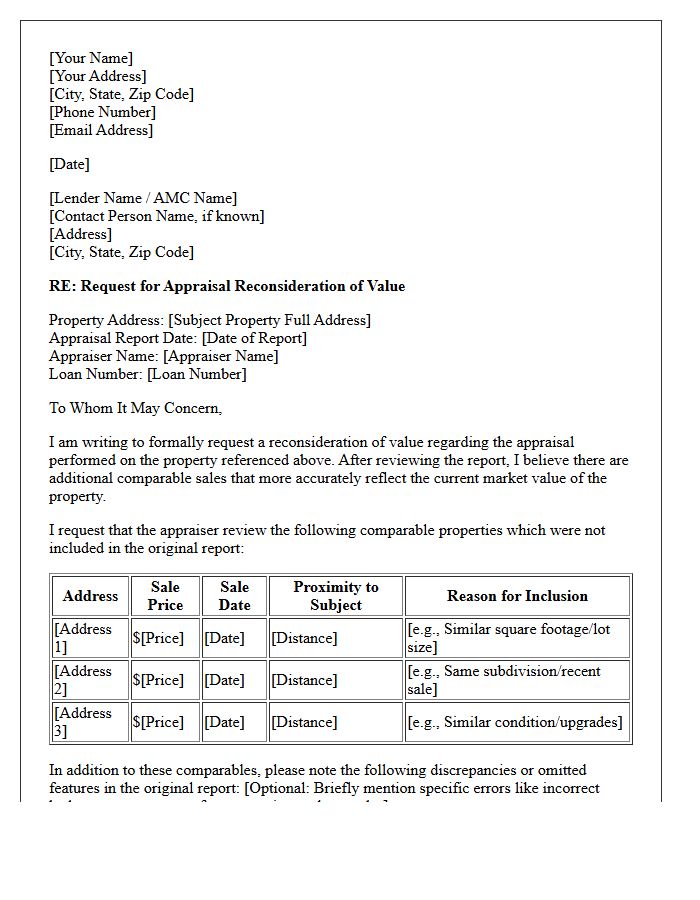
A Comparable Sales Submission Letter is a formal document used to challenge an appraisal by providing alternative market data. It is essential to include verified closed sales that are more recent, geographically closer, or physically similar to the subject property than those in the original report. To be effective, the letter must provide a factual narrative explaining why these new comparables offer a more accurate reflection of fair market value. Clear documentation helps an appraiser or lender reconsider the valuation based on superior evidence.
Earnest Money Release Letter Following Appraisal Shortfall
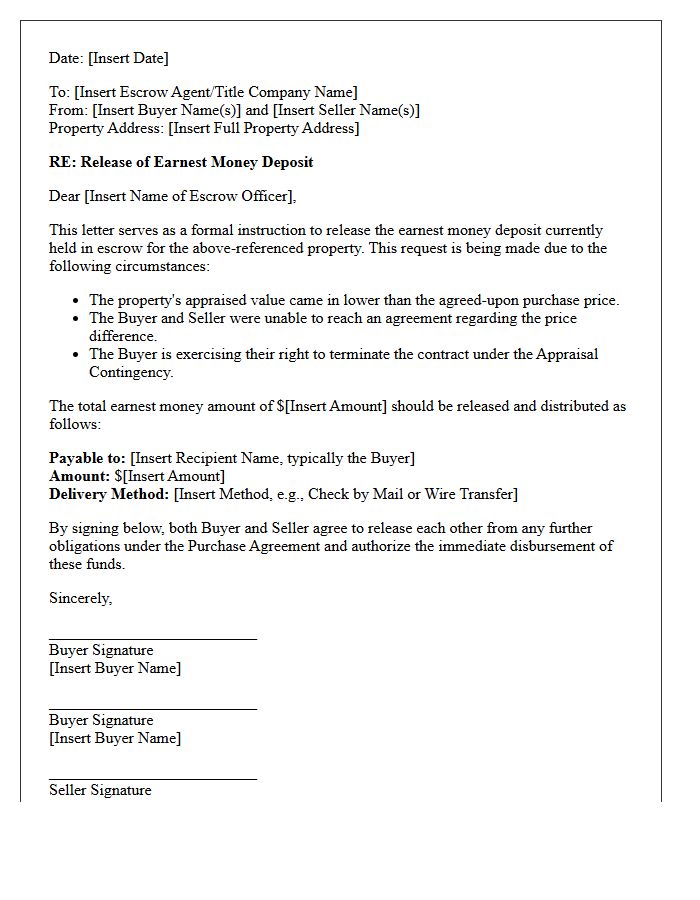
An Earnest Money Release Letter is a legal document used to return a security deposit to the buyer after a real estate deal fails. When a property's appraisal shortfall occurs, and the value is lower than the purchase price, the buyer may exercise their appraisal contingency to cancel the contract. This signed letter provides formal authorization for the escrow agent to distribute the held funds back to the buyer, ensuring a clean legal break and protecting the buyer's capital from forfeiture when financing terms cannot be met.
What is an Appraisal Shortfall Solution Letter?
An Appraisal Shortfall Solution Letter is a formal proposal sent to a seller or lender when a property's appraised value comes in lower than the agreed-upon purchase price. It outlines specific financial strategies to bridge the valuation gap, such as requesting a price reduction, offering an additional cash down payment, or contesting the appraisal results.
How do I write a letter to resolve an appraisal gap?
To write an effective appraisal shortfall letter, clearly state the appraised value versus the contract price, provide evidence of the discrepancy, and propose a specific solution. Professional solutions include asking the seller to lower the sales price to match the appraisal, split the difference, or requesting a Reconsideration of Value (ROV) based on more accurate comparable sales data.
What are the best strategies to include in an appraisal shortfall proposal?
Common strategies include a "price match" request where the seller reduces the cost, a "cash gap coverage" where the buyer pays the difference out of pocket, or a hybrid approach. You may also suggest a "mortgage insurance restructuring" or a new appraisal if you can prove the initial report contained factual errors or overlooked premium features of the home.
Can a seller refuse to negotiate after receiving an appraisal shortfall letter?
Yes, a seller can refuse to negotiate. If the purchase agreement includes an appraisal contingency, the buyer typically has the right to cancel the contract and receive their earnest money back. However, if the buyer waived the contingency, they are legally obligated to cover the shortfall or risk losing their deposit for breach of contract.
How does an Appraisal Shortfall Solution Letter impact mortgage approval?
Lenders base the maximum loan-to-value (LTV) ratio on the lesser of the purchase price or the appraised value. This letter serves as a roadmap for the lender to see how the loan will remain viable despite the lower valuation, ensuring that the buyer's down payment and financing terms meet the bank's strict underwriting requirements.
Comments